Tax Policy Roundup: Foreign Investment, Demolition Expenses, Data Centers, and Partnership Taxes
September 18, 2026
The Real Estate Roundtable (RER) submitted recommendations this week aimed at removing barriers to foreign investment in US real estate and reforming the tax treatment of demolition costs, as lawmakers introduced data center tax legislation and a federal appeals court ruled on the self-employment tax treatment of limited partners.
FIRPTA: RER Requests Repeal of IRS Notice
This week, RER submitted a letter to Treasury Secretary Scott Bessent requesting revocation of IRS Notice 2007-55, citing its negative impact on foreign investment in U.S. commercial real estate. (Letter, Sept. 15)
The IRS Notice took the position that REIT distributions are not exempt from tax under the tax exemption for foreign governments (section 892). It also treats REIT liquidating distributions as sales of real property subject to tax under the Foreign Investment in Real Property Tax Act (FIRPTA).
The letter notes that nearly 20 years have passed without regulations implementing the Notice. Since that time, statutory changes to FIRPTA have eliminated much of its original rationale, and foreign capital’s importance to U.S. real estate investment and jobs has only increased. (Letter, Sept. 15)
RER contends that the Notice creates unnecessary transaction costs, limits investment flexibility, and discourages otherwise productive transactions. (Letter, Sept. 15)
“[S]ound legal reasoning, good governance, and favorable economic policy strongly support an administrative action to revoke Notice 2007-55,” wrote RER President and CEO Jeffrey DeBoer. “Repeal of the Notice would align squarely with the Administration’s stated priority of ‘unleashing prosperity through deregulation.’”
Property Redevelopment and Demolition Costs: Coalition Seeks Tax Reforms
On Wednesday, RER and 13 other national real estate organizations sent Congress a letter encouraging changes to the tax treatment of demolished buildings and demolition expenses. (Letter, Sept. 15)
Current treatment: Section 280B generally requires both demolition expenses and a demolished building’s remaining tax basis to be added to the basis of nondepreciable land. Owners typically cannot recover those amounts for tax purposes until the land is sold, potentially years or decades later.
“This treatment can delay or deter redevelopment projects that would otherwise support increased housing supply and commercial activity, particularly in high-cost areas and downtown corridors facing elevated vacancy rates,” the 14 organizations wrote. (Letter, Sept. 15)
Proposed changes: The coalition recommends allowing taxpayers to deduct as a loss any remaining tax basis of a demolished building and allowing taxpayers to deduct the actual demolition expenses. The reforms should be paired with reasonable guardrails to protect historic buildings and ensure timely redevelopment of the property.
The issue was recently highlighted in an op-ed written by RER Tax Policy Advisory Committee Chairman Joshua Parker and published in The Hill. (The Hill, Aug. 30 | Roundtable Weekly, Sept. 11)
Future legislation in this area could also restore the deductibility of environmental remediation expenses.
The recently enacted, bipartisan ROAD to Housing Act removed many barriers to creating new housing. The organizations’ proposal would continue building on these efforts by promoting productive real estate investment.
Data Centers: House Democrats Propose Tax Restrictions
Reps. Kristen McDonald Rivet (D-MI) and Don Davis (D-NC) introduced the Reverse Big Ugly Tax Breaks for Data Centers Act on Sept. 16, seeking to exclude covered data centers from investment incentives expanded in the 2025 tax law. (Politico | Rep. Rivet Press Release, Sept. 16)
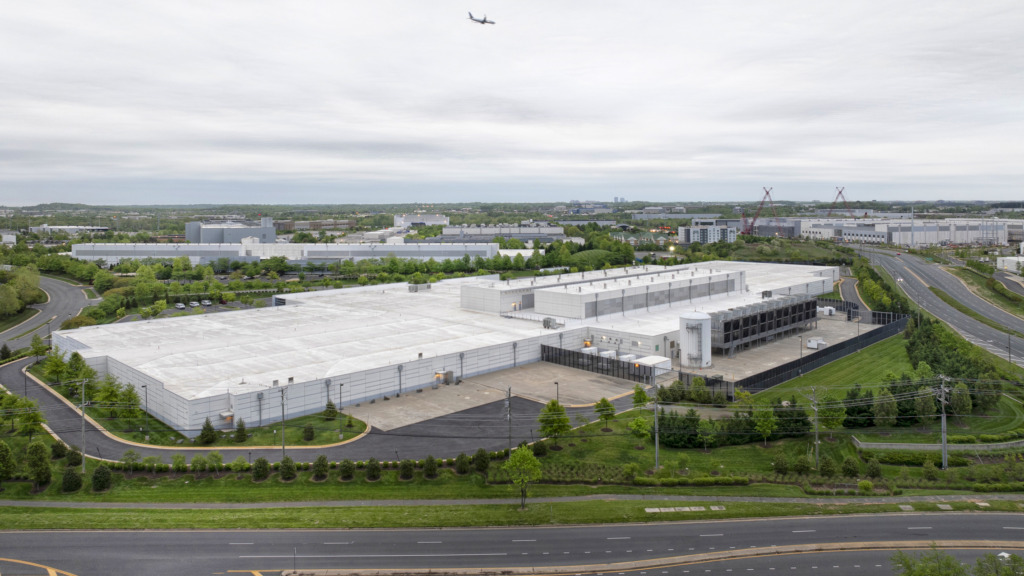
The bill would deny 100% bonus depreciation and Opportunity Zone eligibility to covered data-center property. Its definition covers facilities exceeding 50 megawatts of maximum rated power capacity or total peak power load, including property dedicated to their operation. (Bill text)
The legislation follows an August white paper from Senate Finance Committee Ranking Member Ron Wyden (D-OR) addressing bonus depreciation, Opportunity Zones and REIT treatment for data centers, along with a proposed excise tax on operators. (Senate Finance proposal, Aug. 6 | Roundtable Weekly, Aug. 7)
Partnership Taxes: Second Circuit Rules in Soroban
The U.S. Court of Appeals for the Second Circuit on Sept. 17 affirmed the Tax Court’s decision in Soroban Capital Partners LP v. Commissioner, holding that three principals did not qualify for the limited partner exception from self-employment tax because they exercised managerial control over the firm. (Opinion, Sept. 17)
The court focused on the partners’ actual responsibilities, including managing investments, serving on governing committees, and directing personnel decisions. It clarified that partners may provide some services and still qualify for the exception if those activities do not involve controlling, managing or running the business. (Bloomberg Law, Sept. 17)
The opinion appears to align, at least in significant part, with the Fifth Circuit’s revised approach in K Alain, formerly Sirius Solutions. (Court Opinion | JD Supra, Aug. 12)
RER filed an amicus brief supporting the taxpayer in Soroban as part of its broader challenge to the IRS’s restrictive interpretation of the limited partner exception from self-employment tax. RER also filed briefs supporting taxpayers in Sirius Solutions in the Fifth Circuit and Denham Capital in the First Circuit. (Roundtable Weekly, Jan. 30 | Feb. 13 | Sept. 11)
RER will continue working with Congress, Treasury and the IRS to advance tax policies that expand access to capital, encourage redevelopment and support long-term economic growth.


 Menu
Close
 About Us