NEWS: Higher Rates and Global Uncertainty Weigh on CRE Confidence in Q4

(WASHINGTON, D.C.) — The Real Estate Roundtable (RER) today released its Fourth Quarter 2026 Sentiment Index, a quarterly measure of confidence among senior commercial real estate (CRE) executives. The overall index fell 10 points from the previous quarter to 53 as higher interest rates and geopolitical uncertainty weighed on valuations and led investors to hold off on deals, even as property operations remained healthy across most sectors.

The Current Index fell 16 points to 47, while the Future Index declined 5 points to 58. 42% of respondents said market conditions were worse than a year ago, while 41% expect conditions to improve over the next year.

Current perceptions do not meet the expectations outlined 12 months ago, when 70% of participants anticipated an improvement in general market conditions, with only 30% of Q4 2026 participants believing conditions have in fact improved. (Q4 2025 report)

 “Higher interest rates, tariffs and geopolitical uncertainty are weighing on investment decisions,” said Jeffrey DeBoer, President and CEO of The Real Estate Roundtable. “With the midterm elections behind us, both parties have a chance to give businesses a clearer sense of what to expect from Washington. Affordability, energy prices, and data center growth will stay high on the policy agenda. Preserving key tax and regulatory rules, and streamlining permitting would give businesses more confidence to commit capital to new housing and infrastructure.”

The Q4 Sentiment Index topline findings include:

  • The Q4 2026 Real Estate Roundtable Sentiment Index registered an overall score of 53, a 10-point drop from the previous quarter. The Current Index registered 47, a 16-point decrease from Q3 2026. The Future Index posted a score of 58 points, a decrease of 5 points from the previous quarter. The decreased sentiment this quarter can be attributed to rising interest rates and ongoing geopolitical uncertainty weighing on the market. Interviewees noted a widening gap between how properties are performing and how the market is pricing them, and although operating conditions remain healthy across most sectors, higher rates have unsettled valuations and sent investors back to the sidelines. Most participants expect the setback to pass once rates stabilize. Some see the dislocation as a buying opportunity, though few are ready to commit capital until then.
  • Views continue to vary widely by property type. Open-air retail and industrial have held their value, supported by limited new supply. Office sentiment is improving in select gateway markets, helped in part by leasing from AI companies and the firms benefiting from them. Data centers continue to attract strong demand, though interviewees flagged growing political resistance and questions about long-term need. Multifamily drew the most divided views. Some participants pointed to oversupply in the Sun Belt and the risk that job losses could pressure rents. Others see the recent price declines and early occupancy gains as an attractive entry point.
  • More than half (56%) of respondents believe asset values are lower compared to a year ago, while 29% feel they are unchanged and 15% feel values have increased. Asset values continue to face downward pressure amid interest rate volatility and pricing uncertainty, though the extent of further declines varies by asset quality and sector, with sellers adjusting expectations to facilitate transactions. Looking ahead, the outlook is mixed: 27% expect asset prices to rise over the next year, 42% believe asset values will remain stable, and 31% anticipate that values will decrease.
  • Perceptions on equity capital are down, with 51% believing availability is worse compared to a year ago, 15% thinking it is better, and 34% feeling it is the same. On the other hand, sentiment around debt capital is somewhat positive, as 44% said the availability of debt capital has improved from last year. Looking forward, 28% of respondents believe that equity capital availability will be better in one year and 17% believe debt capital availability will be better.

Sample responses from participants in the Sentiment Index’s Q4 survey include:

“Geopolitical risk is top of mind for everybody. Between Iran, the midterms, and the divides within both parties, there is a great deal of uncertainty, and uncertainty is bad for business.”

“Data centers continue to do well, but the political backlash is building. There are real questions about how many data centers we need, since the technology changes quickly and these buildings have no adaptive reuse.”

“The price reset won’t be massive, and everyone knows it’s coming. What matters is that the whole industry makes it together.”

Data for the Q4 survey was gathered by Chicago-based Ferguson Partners on RER’s behalf in October. See the full Q4 report.

# # #
Commercial Real Estate Confidence Holds Steady as Market Stabilizes, Q4 Sentiment Index Shows

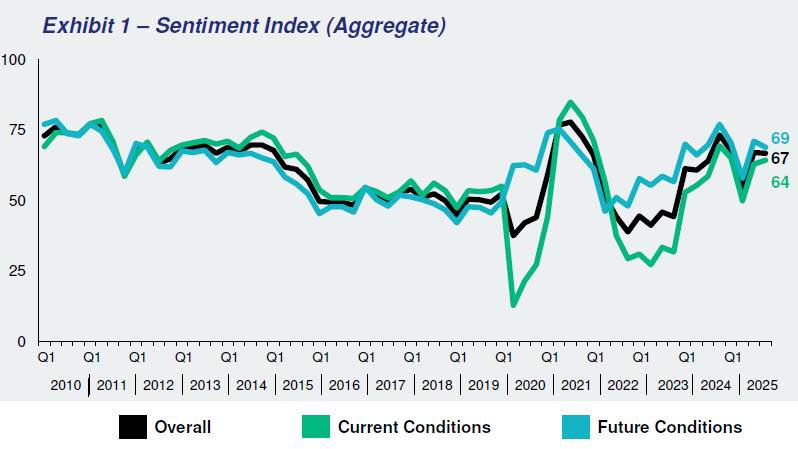
The Real Estate Roundtable’s (RER) Q4 2025 Sentiment Index registered an overall score of 67, equivalent to the prior quarter, reflecting that commercial real estate executives’ sentiment has shifted from caution toward guarded optimism as markets stabilize, transaction activity resumes, and expectations build for easing interest rates in 2026.

Topline Findings

The Q4 Sentiment Index topline findings include:

  • The Q4 2025 Real Estate Roundtable Sentiment Index registered an overall score of 67, equivalent to the previous quarter. The Current Index registered a score of 64, a 1-point increase from Q3 2025. The Future Index posted a score of 69 points, a 2-point decrease from the previous quarter, reflecting sentiment that the market has largely stabilized and is now transitioning from caution to guarded optimism. Many participants anticipate stronger transaction activity in 2026 as interest rates ease and confidence builds, yet acknowledge that political and policy uncertainty continue to temper near-term enthusiasm.
  • Although perspectives vary by asset class, overall market sentiment remains positive. Only 13% of respondents believe that general market conditions are worse than this time last year, while 63% believe that general market conditions are better than this time last year. More than two-thirds (70%) of Q4 survey participants expect general market conditions to show improvement one year from now. Leaders reported continued strength in residential sectors, alongside steady improvement in retail and hospitality. Office remains the most challenged asset class, though signs of stabilization are emerging in top-tier markets.
  • 43% of respondents believe asset values are roughly unchanged compared to a year ago. A large minority of participants see green shoots, with 42% believing asset prices have increased and only 15% believing they have declined. Looking ahead, the outlook is optimistic: 72% expect asset prices to rise over the next year, 24% believe asset values will remain stable, and only 4% anticipate a slight decline.
  • Perceptions on the availability of equity capital relative to last quarter are muted, although nearly half (48%) of respondents still believe equity availability is better compared to a year ago. On the other hand, sentiment around debt capital has risen significantly, as 78% said the availability of debt capital has improved from last year. Looking forward, 64% of respondents believe that equity capital availability will be better in one year and 56% believe debt capital availability will be better.

Roundtable View

  • RER President and CEO Jeffrey DeBoer said, “Real estate executives see encouraging momentum. Roundtable members are reporting steady improvement and renewed confidence across sectors. Despite improvements, tariffs continue to drive up development costs and complicate business planning. Moreover, the record-long government shutdown is disrupting infrastructure and construction permitting, and access to current economic data that companies rely on to plan”
  • He added, “Clear, consistent, and coordinated policies from Washington are essential to unlock capital and support long-term economic growth in communities nationwide.”

Data for the Q4 survey was gathered by Chicago-based Ferguson Partners on RER’s behalf in October. See the full Q4 report.

CRE Executives Report Ongoing Financing and Liquidity Issues Causing Price Discovery Difficulties

Industry executives report commercial real estate asset classes continue to face a variety of challenges centered around higher financing costs, increased illiquidity, and uncertain post-pandemic user demand. Reduced transaction volume has also contributed to difficult price discovery, according to The Real Estate Roundtable’s Q4 2023 Sentiment Index. (RER news release, Nov. 3)

 Pressures on CRE Assets

  • Roundtable President and CEO Jeffrey DeBoer said, “Commercial real estate is at the front line of change in how people use the built environment in a post-pandemic society. Steep interest rate increases and diminished liquidity caused by regulatory pressures have led to much lower transaction volume and continued uncertainty in price discovery. The challenges facing different asset classes in the broad, complex CRE landscape is reflected in our Q4 Sentiment Index.”
  • The Roundtable’s Sentiment Index—a measure of senior executives’ confidence and expectations about the commercial real estate market environment—is scored on a scale of 1 to 100 by averaging the scores of Current and Future Sentiment Indices.­­­­ Any score over 50 is viewed as positive. ­­­­
  • The Q4 Index comes days after the Federal Reserve left its benchmark interest rate unchanged at a 22-year high of 5.4% and stated it remains open to future increases. “The good news is we’re making progress,” Chair Jerome Powell said.” (Associated Press, Fed press release and Fed news conference video, Nov. 1)

Q4 Sentiment Index Topline Findings:

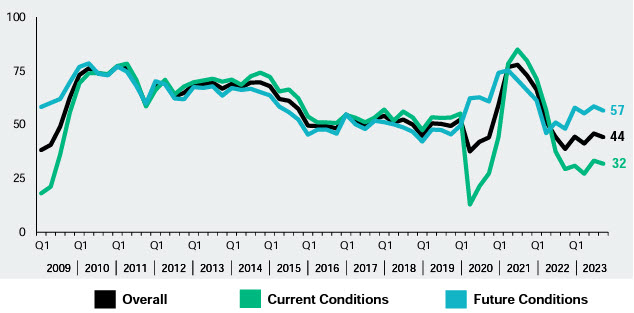
  • The Q4 2023 Real Estate Roundtable Sentiment Index registered an overall score of 44, a decrease of two points from the previous quarter. The Current Index registered 32, a one-point decrease from Q3 2023, and the Future Index posted a score of 57 points, a decrease of two points from the previous quarter. These stable indices highlight the persistent challenges faced by participants in the real estate market.
  • Although there are variations among asset classes and even within specific property types, ongoing uncertainty within the broader commercial real estate industry persists due to concerns about liquidity, capital availability, interest rates, and remote work. Bright spots exist in smaller classes, such as data centers, outlet malls, and hotels, while multifamily and industrial continue to attract interest.  Within the office sector, class “A” properties with top-of-the-line amenities are the lone high performers.
  • An overwhelming 92% of survey participants indicate that asset values have decreased compared to the previous year. The valuation process has been challenging due to limited transactions, and the combination of current cap rates and fluctuating interest rates has further complicated pricing, ultimately leading to a view that asset values have decreased relative to one year ago.
  • Survey participants express ongoing concerns about the capital markets landscape, with 70% indicating that the availability of equity capital has worsened compared to a year ago, and 86% believing the availability of debt capital is also worse.
Jeffrey DeBoer, Real Estate Roundtable President and CEO(
  • DeBoer, above, added, “We welcome efforts at all levels of government to incentivize conversions of commercial use to residential use. Yet various CRE markets and asset classes need more time to adapt to the new preferences of clients; more flexibility to restructure their asset financing; and patience while adjusting to the evolving valuation landscape. In addition to conversion activities, The Roundtable continues to urge the federal government to return to the workplace and support measures to assist loan modifications and increase liquidity available to all asset classes and their owners. We also remain opposed to regulatory proposals that impede capital formation.”
  • Some sample responses from participants in the Sentiment Index’s Q4 Survey include:

“Your perspective depends on what assets you hold and the strength of your balance sheet.”

“The distribution of capital is highly dependent on specific sectors and asset quality.”

“There will be a ‘great revaluation’ cycle with more real estate assets priced lower. There haven’t been enough transactions to collect good data, and the transactions that are happening are in the most dire of circumstances, which is driving erratic and less reliable market information.”

Data for the Q4 survey was gathered in October by Chicago-based Ferguson Partners on behalf of The Roundtable. See the full Q4 report.

#  #  #

NEWS: CRE Executives Report Ongoing Financing and Liquidity Issues Causing Price Discovery Difficulties

(WASHINGTON, D.C.) — Industry executives report commercial real estate asset classes continue to face a variety of challenges centered around higher financing costs, increased illiquidity, and uncertain post-pandemic user demand. Reduced transaction volume has also contributed to difficult price discovery, according to The Real Estate Roundtable’s Q4 2023 Sentiment Index.

Roundtable President and CEO Jeffrey DeBoer said, “Commercial real estate is at the front line of change in how people use the built environment in a post-pandemic society. Steep interest rate increases and diminished liquidity caused by regulatory pressures have led to much lower transaction volume and continued uncertainty in price discovery. The challenges facing different asset classes in the broad, complex CRE landscape is reflected in our Q4 Sentiment Index.”

The Roundtable’s Sentiment Index—a measure of senior executives’ confidence and expectations about the commercial real estate market environment—is scored on a scale of 1 to 100 by averaging the scores of Current and Future Sentiment Indices. Any score over 50 is viewed as positive.

The Q4 Sentiment Index topline findings include:

• The Q4 2023 Real Estate Roundtable Sentiment Index registered an overall score of 44, a decrease of two points from the previous quarter. The Current Index registered 32, a one-point decrease from Q3 2023, and the Future Index posted a score of 57 points, a decrease of two points from the previous quarter. These stable indices highlight the persistent challenges faced by participants in the real estate market.

• Although there are variations among asset classes and even within specific property types, ongoing uncertainty within the broader commercial real estate industry persists due to concerns about liquidity, capital availability, interest rates, and remote work. Bright spots exist in smaller classes, such as data centers, outlet malls, and hotels, while multifamily and industrial continue to attract interest. Within the office sector, class “A” properties with top of-the-line amenities are the lone high performers.

• An overwhelming 92% of survey participants indicate that asset values have decreased compared to the previous year. The valuation process has been challenging due to limited transactions, and the combination of current cap rates and fluctuating interest rates has further complicated pricing, ultimately leading to a view that asset values have decreased relative to one year ago.

• Survey participants express ongoing concerns about the capital markets landscape, with 70% indicating that the availability of equity capital has worsened compared to a year ago, and 86% believing the availability of debt capital is also worse.

DeBoer added, “We welcome efforts at all levels of government to incentivize conversions of commercial use to residential use. Yet various CRE markets and asset classes need more time to adapt to the new preferences of clients; more flexibility to restructure their asset financing; and patience while adjusting to the evolving valuation landscape. In addition to conversion activities, The Roundtable continues to urge the federal government to return to the workplace and support measures to assist loan modifications and increase liquidity available to all asset classes and their owners. We also remain opposed to regulatory proposals that impede capital formation.”

Some sample responses from participants in the Sentiment Index’s Q4 Survey include:

“Your perspective depends on what assets you hold and the strength of your balance sheet.”

“The distribution of capital is highly dependent on specific sectors and asset quality.”

“There will be a ‘great revaluation’ cycle with more real estate assets priced lower. There haven’t been enough transactions to collect good data, and the transactions that are happening are in the most dire of circumstances, which is driving erratic and less reliable market information.”

Responses by survey participants reflect recent, persistent challenges facing certain sectors and assets. In comparison to last quarter, sentiments on current conditions are down by 1 point, perceptions of future conditions are down by 2 points, and overall conditions are down by 2 points.

Regarding sentiment on the state of current asset values, 92% of respondents believe they are lower than one year ago, 3% feel they are higher, and 5% believe asset values have remained the same compared to a year ago. This contrasts with the Sentiment Survey one year ago, when only 59% of participants expected asset values would be lower in this Q4 2023, indicating a steep decline in current perceptions of asset values.

Survey participants also commented on the availability of equity capital, with 70% noting it is worse compared to one year ago, 3% stating it has improved, and 27% that the availability of equity remains the same. For the availability of debt capital, 86% of participants believe it is worse compared to one year ago, 2% feel it has improved, and 12% believe the availability of debt remains the same.

Data for the Q4 survey was gathered in October by Chicago-based Ferguson Partners on behalf of The Roundtable. See the full Q4 report.

The Real Estate Roundtable brings together leaders of the nation’s top publicly-held and privately owned real estate ownership, development, lending and management firms with the leaders of major national real estate trade associations to jointly address key national policy issues relating to real estate and the overall economy.

# # #