Tax Policy Roundup: Foreign Investment, Demolition Expenses, Data Centers, and Partnership Taxes

FIRPTA

The Real Estate Roundtable (RER) submitted recommendations this week aimed at removing barriers to foreign investment in US real estate and reforming the tax treatment of demolition costs, as lawmakers introduced data center tax legislation and a federal appeals court ruled on the self-employment tax treatment of limited partners.

FIRPTA: RER Requests Repeal of IRS Notice

  • This week, RER submitted a letter to Treasury Secretary Scott Bessent requesting revocation of IRS Notice 2007-55, citing its negative impact on foreign investment in U.S. commercial real estate. (Letter, Sept. 15)
  • The IRS Notice took the position that REIT distributions are not exempt from tax under the tax exemption for foreign governments (section 892). It also treats REIT liquidating distributions as sales of real property subject to tax under the Foreign Investment in Real Property Tax Act (FIRPTA).
  • The letter notes that nearly 20 years have passed without regulations implementing the Notice. Since that time, statutory changes to FIRPTA have eliminated much of its original rationale, and foreign capital’s importance to U.S. real estate investment and jobs has only increased. (Letter, Sept. 15)
  • RER contends that the Notice creates unnecessary transaction costs, limits investment flexibility, and discourages otherwise productive transactions. (Letter, Sept. 15)
  • “[S]ound legal reasoning, good governance, and favorable economic policy strongly support an administrative action to revoke Notice 2007-55,” wrote RER President and CEO Jeffrey DeBoer. “Repeal of the Notice would align squarely with the Administration’s stated priority of ‘unleashing prosperity through deregulation.’”

Property Redevelopment and Demolition Costs: Coalition Seeks Tax Reforms
  • On Wednesday, RER and 13 other national real estate organizations sent Congress a letter encouraging changes to the tax treatment of demolished buildings and demolition expenses.  (Letter, Sept. 15)
  • Current treatment: Section 280B generally requires both demolition expenses and a demolished building’s remaining tax basis to be added to the basis of nondepreciable land. Owners typically cannot recover those amounts for tax purposes until the land is sold, potentially years or decades later.
  • “This treatment can delay or deter redevelopment projects that would otherwise support increased housing supply and commercial activity, particularly in high-cost areas and downtown corridors facing elevated vacancy rates,” the 14 organizations wrote. (Letter, Sept. 15)
  • Proposed changes: The coalition recommends allowing taxpayers to deduct as a loss any remaining tax basis of a demolished building and allowing taxpayers to deduct the actual demolition expenses. The reforms should be paired with reasonable guardrails to protect historic buildings and ensure timely redevelopment of the property.

  • The issue was recently highlighted in an op-ed written by RER Tax Policy Advisory Committee Chairman Joshua Parker and published in The Hill. (The Hill, Aug. 30 | Roundtable Weekly, Sept. 11)
  • Future legislation in this area could also restore the deductibility of environmental remediation expenses.
  • The recently enacted, bipartisan ROAD to Housing Act removed many barriers to creating new housing. The organizations’ proposal would continue building on these efforts by promoting productive real estate investment.

Data Centers: House Democrats Propose Tax Restrictions
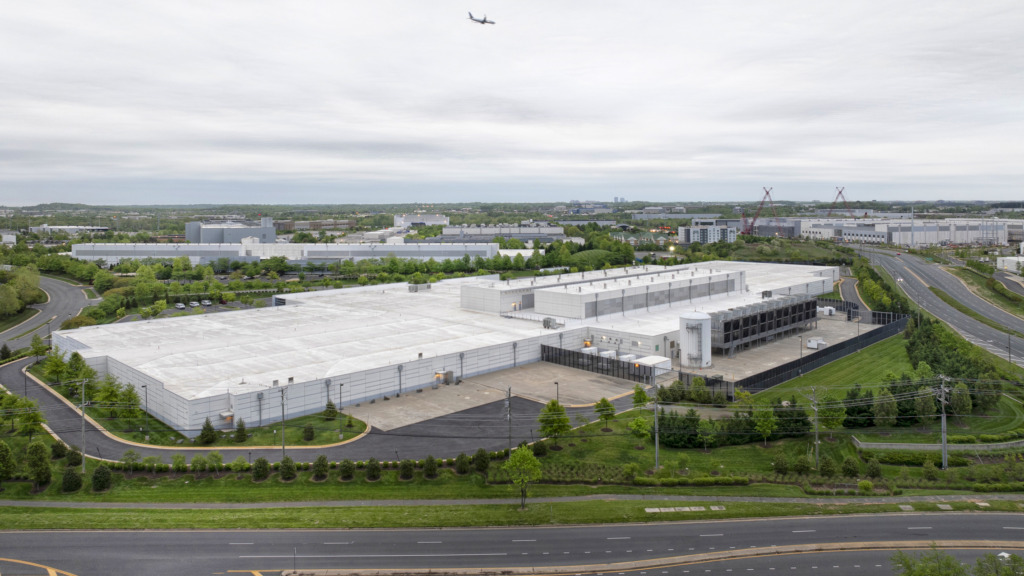
  • Reps. Kristen McDonald Rivet (D-MI) and Don Davis (D-NC) introduced the Reverse Big Ugly Tax Breaks for Data Centers Act on Sept. 16, seeking to exclude covered data centers from investment incentives expanded in the 2025 tax law. (Politico |  Rep. Rivet Press Release, Sept. 16)
  • The bill would deny 100% bonus depreciation and Opportunity Zone eligibility to covered data-center property. Its definition covers facilities exceeding 50 megawatts of maximum rated power capacity or total peak power load, including property dedicated to their operation. (Bill text)
  • The legislation follows an August white paper from Senate Finance Committee Ranking Member Ron Wyden (D-OR) addressing bonus depreciation, Opportunity Zones and REIT treatment for data centers, along with a proposed excise tax on operators. (Senate Finance proposal, Aug. 6 | Roundtable Weekly, Aug. 7)

Partnership Taxes: Second Circuit Rules in Soroban

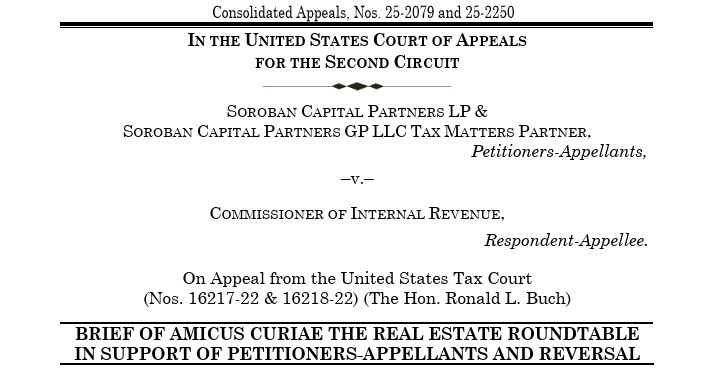
  • The U.S. Court of Appeals for the Second Circuit on Sept. 17 affirmed the Tax Court’s decision in Soroban Capital Partners LP v. Commissioner, holding that three principals did not qualify for the limited partner exception from self-employment tax because they exercised managerial control over the firm. (Opinion, Sept. 17)
  • The court focused on the partners’ actual responsibilities, including managing investments, serving on governing committees, and directing personnel decisions. It clarified that partners may provide some services and still qualify for the exception if those activities do not involve controlling, managing or running the business. (Bloomberg Law, Sept. 17)
  • The opinion appears to align, at least in significant part, with the Fifth Circuit’s revised approach in K Alain, formerly Sirius Solutions. (Court Opinion | JD Supra, Aug. 12)
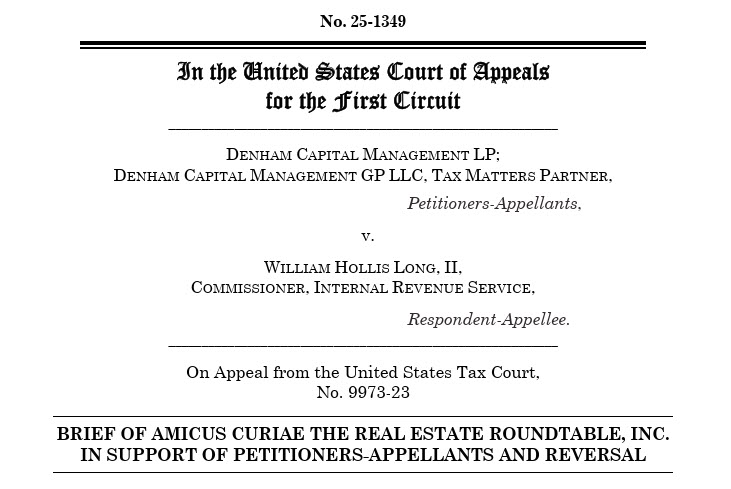
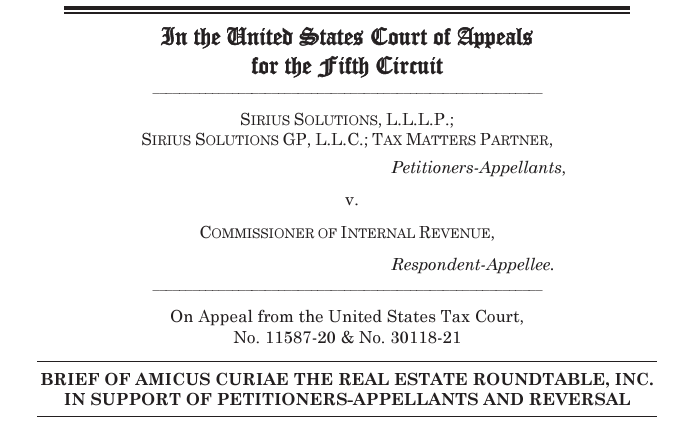
  • RER filed an amicus brief supporting the taxpayer in Soroban as part of its broader challenge to the IRS’s restrictive interpretation of the limited partner exception from self-employment tax. RER also filed briefs supporting taxpayers in Sirius Solutions in the Fifth Circuit and Denham Capital in the First Circuit. (Roundtable Weekly, Jan. 30 | Feb. 13 | Sept. 11)

RER will continue working with Congress, Treasury and the IRS to advance tax policies that expand access to capital, encourage redevelopment and support long-term economic growth.

Tax Policy Roundup: Community Revitalization, Opportunity Zones, Foreign Investment, and Judicial Developments

As Congress returns to Washington, The Real Estate Roundtable (RER) is working to advance several tax policy initiatives aimed at expanding housing supply, revitalizing communities, and removing barriers to capital formation for real estate investment.

Tax Policies to Support Community Revitalization

  • On August 30, RER’s Tax Policy Advisory Committee (TPAC) Chairman Joshua Parker published an op-ed in The Hill newspaper setting forth a three-part framework for how lawmakers should think about potential tax policies to support community revitalization. (The Hill, Aug. 30)
  • “Preserve buildings that can serve again,” wrote Parker. “Convert those that can meet a new need. Clear those that cannot and require the land to be rebuilt.”
  • Parker’s op-ed outlines three actionable tax changes advocated by RER to advance this framework: (1) reforming the tax treatment of demolition costs, including the lost tax basis when a building is torn down; (2) strengthening the historic tax credit, and (3) incentivizing commercial-to-residential conversions through the bipartisan Revitalizing Downtowns and Main Streets Act (H.R. 2410).

Opportunity Zones

  • RER is continuing to encourage Treasury and the IRS to move forward with transitional tax guidance that will provide much-needed clarity to Opportunity Zone (OZ) investors pursuing new housing and other real estate projects that straddle the pre- and post-2025 OZ statutory regimes.
  • IRS Notice 2026-40, released in June, embraced several RER recommendations and clarified certain key issues for taxpayers with OZ projects in expiring census tracts. (Roundtable Weekly, June 26)
  • RER followed up the Notice with additional suggestions, and met virtually with Treasury and IRS staff, along with other stakeholders, on Aug. 27. Formal proposed regulations from Treasury are expected before the end of the year. (Letter, July 29 | Roundtable Weekly, July 31)
  • This week, Treasury and the IRS issued proposed regulations implementing new reporting requirements for Qualified Opportunity Funds and Qualified Opportunity Zone Businesses. (PoliticoPro, Sept. 10)

FIRPTA and Tax Barriers to Foreign Investment in US Real Estate

FIRPTA
  • RER is finalizing a request to Treasury to revoke outdated administrative guidance (IRS Notice 2007-55) that creates unnecessary hurdles and tax burdens for foreign investors seeking to deploy capital in US real estate.
  • Notice 2007-55 treats REIT liquidating distributions as a sale of real property rather than the sale of stock, thus subjecting the transactions to tax under FIRPTA. The Notice also treats REIT distributions as ineligible for the section 892 foreign government tax exemption.
  • RER believes the Notice’s conclusions were incorrect at the time, and more recent events strongly favor its repeal.
  • These include changes in the FIRPTA statute since the Notice was issued, growth in the importance of foreign capital to U.S. real estate jobs and investment, and the corrosive effect of 20 year-old sub-regulatory guidance that has never been subject to the formal rulemaking process.

SECA Limited Partner Exception

  • On Aug. 12, the Fifth Circuit withdrew its January opinion in Sirius Solutions and issued a substitute opinion holding that the self-employment tax exception applies to a limited partner who plays “no significant role in managing or running a business.” (JD Supra, Sept. 9)
  • The new standard is a step back from the court’s earlier ruling, which based eligibility on limited liability and state-law limited partner status. However, the court again rejected the Tax Court’s stricter “passive investor” test and remanded the case for further consideration. (Grant Thornton, Aug. 17)
  • RER has filed amicus briefs supporting taxpayers in Sirius and two related appeals—Denham Capital in the First Circuit and Soroban Capital Partners in the Second Circuit. (Roundtable Weekly, Jan. 30 | Feb. 13)

RER will continue engaging with Congress, Treasury, and the IRS to advocate for clear, effective tax rules that expand access to capital, encourage investment and redevelopment, and support long-term economic growth.
First Circuit Hears Denham Oral Argument as SECA Limited Partner Fight Continues

The legal dispute over the tax code’s limited partner exception from self-employment (SECA) taxes remains very much alive, with the issue now in various stages of litigation before three federal appellate courts. The IRS is asserting that a limited partner must be a passive investor.

Denham Oral Arguments

  • On Feb. 5, the First Circuit heard oral argument in Denham Capital Management LP, et al. v. Commissioner (No. 25-1349), while a related appeal in Soroban Capital Partners LP v. Commissioner is pending in the Second Circuit. The Fifth Circuit also recently issued a significant decision in Sirius Solutions, L.L.L.P. v. Commissioner (No. 24-60240). (Roundtable Weekly, Jan. 30)
  • The First Circuit heard oral arguments in Denham before Chief Judge David Barron, Judge Kermit Lipez, and Judge Lara Montecalvo Rikelman. Most of the argument focused on jurisdictional issues, which could allow the court to resolve the case without reaching the merits.
  • On the merits, the panel posed tough questions to Denham and the IRS. The discussion focused on the meaning of a limited partner in 1977 when the exception was enacted, prior case law, relevant dictionary definitions, the Revised Uniform Limited Partnership Act, and the provision’s legislative history.
  • In the course of the argument, Denham emphasized state law developments leading up to the 1977 amendments and, notably, cited The Real Estate Roundtable’s (RER) amicus brief in support of its position. (RER Amicus Brief, Aug. 15; Roundtable Weekly, Sept. 12, 2025)

Why It Matters

  • Income-producing real estate is predominantly owned and operated through partnerships, and the IRS’s litigation campaign creates risk for long-standing structures relied on by real estate and other pass-through businesses.
  • A circuit split among the First, Second, and Fifth Circuits could accelerate Supreme Court review of the issue.

RER Advocacy

  • RER is actively engaged across the circuits to oppose the IRS’s restrictive “passive investor” approach:
  • First Circuit (Denham): RER filed an amicus brief in August 2025 supporting the taxpayer’s challenge to the Tax Court’s judge-made “passive investor” test and explaining the long-standing reliance of real estate partnerships on state-law limited partner status.
  • Second Circuit (Soroban): RER filed an amicus brief in December 2025 urging reversal of the Tax Court’s Soroban approach and warning that a new federal “passivity” overlay would inject uncertainty and increase tax burdens for partnership-based businesses. (Roundtable Weekly, Dec. 19, 2025)
  • Fifth Circuit (Sirius): RER filed an amicus brief in 2024, and the Fifth Circuit’s Jan. 16, 2026 decision rejected the Tax Court’s passivity-focused framework in favor of a status-based analysis tied to limited liability.  (Roundtable Weekly, Jan. 30)

What’s Next

  • The First Circuit’s decision in Denham could turn on jurisdictional challenges, but the merits questions at argument underscored that the government’s “passive investor” theory remains contested and unstable across the courts.

RER will continue pressing its position through amicus advocacy to protect the flexibility inherent in partnership tax rules and preserve the long-standing tax exemption for limited partners.

Fifth Circuit Reverses Tax Court, Sides with Taxpayer and Roundtable in Limited Partnership Tax Dispute

The U.S. Court of Appeals for the Fifth Circuit issued a 2-1 decision in Sirius Solutions, L.L.L.P. v. Commissioner (No. 24-60240) on Jan. 16, restricting the federal government’s effort to extend self-employment taxes to a broad range of limited partners in limited partnerships. The Real Estate Roundtable (RER) submitted an amicus brief in the case, and the Court’s ruling closely aligns with the RER’s position.

Court Ruling

  • Since 1977, the tax code has exempted limited partners from self-employment taxes. In recent years, the IRS has asserted a new and more restrictive test to determine whether a limited partner qualifies for the exclusion.
  • The Fifth Circuit held that the Section 1402(a)(13) “limited partner” exception from self-employment (SECA) tax applies to a partner in a state-law limited partnership who has limited liability. (TaxNotes, Jan. 27)
  • The ruling vacates and remands the Tax Court decision that followed Soroban Capital Partners LP v. Commissioner (No. 25-2079), and applied a “functional analysis” of partner roles and activities to determine whether the SECA exclusion applies. (Sullivan Cromwell, Jan. 27)
  • The Fifth Circuit rejected that approach and held that “limited partner” in Section 1402(a)(13) is a status-based, state-law concept tied to limited liability, not an activity test.
  • The decision is the first appellate ruling to reach the issue and reverse the Tax Court’s restrictive interpretation. (Reuters, Jan. 21)
  • This ruling has set a precedent for future SECA tax cases, with significant consequences for real estate and other industries that use limited partnerships for business purposes.

Roundtable Advocacy

  • In August 2024, RER submitted an amicus brief to the Fifth Circuit. The brief argued that the IRS’s interpretation was flawed and inconsistent with decades of state law recognizing that limited partners can provide services while retaining limited partner status. (Roundtable Weekly, Sept. 6, 2024)
  • The brief emphasized that pre-1977 state court decisions and the IRS’s own 1994 proposed regulations contradict the government’s position that limited partners must be passive to avoid SECA taxes.
  • RER argued the Tax Court’s “passive investor” test is found nowhere in the statute and reflects a misunderstanding of partnership law that real estate and other businesses have relied on for decades.
  • RER has continued this advocacy across the circuits. In Dec. 2025, RER filed an amicus brief with the Second Circuit in Soroban, challenging the IRS’s restrictive interpretation of the “limited partner exception” under Section 1402(a)(13). (Roundtable Weekly, Dec. 19, 2025)
  • This successful outcome in the Sirius case supports RER’s position and could reduce momentum for formal tax guidance that would broaden the reach of SECA taxes.

What’s Next

  • Related appeals are pending in the First Circuit (Denham) and Second Circuit (Soroban). (TaxNotes, Jan. 27)
  • Divergent outcomes could create a circuit split and increase the odds of Supreme Court review. (Skadden Arps, Jan. 27)
  • The First Circuit is scheduled to hear oral arguments in Denham on Feb. 5. (TaxNotes, Jan. 27)

RER remains committed to protecting entrepreneurs’ ability to flexibly organize in partnerships and other pass-through entities that promote capital formation, risk-taking, and economic growth, and it will remain engaged as the SECA dispute moves forward.

Roundtable Urges Second Circuit Court of Appeals to Preserve Employment Tax Exemption for Limited Partners

The Real Estate Roundtable (RER) filed an amicus brief this week with the Second Circuit Court of Appeals in Soroban Capital Partners LP v. Commissioner, a case that challenges the IRS’s restrictive interpretation of the “limited partner exception” from self-employment (SECA) taxes under section 1402(a)(13) of the tax code. (Amicus Brief, Dec. 15)

Why It Matters

  • Income-producing real estate—rental housing, neighborhood shopping centers, office buildings, etc.—is predominantly owned and operated in partnership form. In 2022, there were over 2.2 million real estate partnerships in the United States, with nearly 9.6 million partners.
  • The Self-Employment Contributions Act (SECA) imposes Social Security and Medicare taxes on net earnings from self-employment. The SECA tax rate on earnings above $250,000 is 3.8%. While the tax applies to a broad range of trade or business income, Congress expressly exempted limited partners from SECA in the Social Security Amendments of 1977.
  • Legislative proposals and proposed regulations have unsuccessfully attempted to extend the 3.8% SECA tax or the 3.8% net investment income tax to limited partners.
  • The IRS has undertaken an aggressive effort to redefine what it means to be a limited partner by challenging taxpayers and litigating the issue in several cases before the Tax Court.

Roundtable View

  • Real estate partnerships have relied for decades on longstanding tax law as it relates to limited partners and the SECA exception.
  • In Soroban and related cases, the Tax Court has imposed a judge-made test and concluded contrary to decades of established state law that a limited partner must be a ‘passive investor,’ notes the RER amicus brief.
  • The Tax Court’s 2023 Soroban ruling wrongly introduced a federal “passivity” requirement that is unmoored from statute, legislative history, and Treasury’s own prior interpretations. However, limited partners have routinely provided business services to their partnerships without losing their limited liability status. (Roundtable Weekly, Sept. 12)
  • “A shift in the federal tax definition of a limited partner could alter underlying partnership economics, increase tax burdens, and create significant uncertainty for real estate and other pass-through businesses,” said RER President and CEO Jeffrey DeBoer. “Such changes need to go through Congress and withstand legislative scrutiny.”

Background

  • RER’s amicus brief was drafted by litigation counsel at Sullivan & Cromwell LLP, in consultation with RER’s Tax Policy Advisory Committee (TPAC). RER also filed an amicus brief in August
    with the First Circuit Court of Appeals in a related case, Denham Capital Management LP v. Commissioner. (Roundtable Weekly, Sept. 12)

Next Steps

The decision in any of the pending cases could have nationwide implications for how partnerships are treated under SECA. A ruling against the Tax Court’s passive investor test would reinforce state law’s central role in defining “limited partner” status.