Tax Policy Roundup: Foreign Investment, Demolition Expenses, Data Centers, and Partnership Taxes

FIRPTA

The Real Estate Roundtable (RER) submitted recommendations this week aimed at removing barriers to foreign investment in US real estate and reforming the tax treatment of demolition costs, as lawmakers introduced data center tax legislation and a federal appeals court ruled on the self-employment tax treatment of limited partners.

FIRPTA: RER Requests Repeal of IRS Notice

  • This week, RER submitted a letter to Treasury Secretary Scott Bessent requesting revocation of IRS Notice 2007-55, citing its negative impact on foreign investment in U.S. commercial real estate. (Letter, Sept. 15)
  • The IRS Notice took the position that REIT distributions are not exempt from tax under the tax exemption for foreign governments (section 892). It also treats REIT liquidating distributions as sales of real property subject to tax under the Foreign Investment in Real Property Tax Act (FIRPTA).
  • The letter notes that nearly 20 years have passed without regulations implementing the Notice. Since that time, statutory changes to FIRPTA have eliminated much of its original rationale, and foreign capital’s importance to U.S. real estate investment and jobs has only increased. (Letter, Sept. 15)
  • RER contends that the Notice creates unnecessary transaction costs, limits investment flexibility, and discourages otherwise productive transactions. (Letter, Sept. 15)
  • “[S]ound legal reasoning, good governance, and favorable economic policy strongly support an administrative action to revoke Notice 2007-55,” wrote RER President and CEO Jeffrey DeBoer. “Repeal of the Notice would align squarely with the Administration’s stated priority of ‘unleashing prosperity through deregulation.’”

Property Redevelopment and Demolition Costs: Coalition Seeks Tax Reforms
  • On Wednesday, RER and 13 other national real estate organizations sent Congress a letter encouraging changes to the tax treatment of demolished buildings and demolition expenses.  (Letter, Sept. 15)
  • Current treatment: Section 280B generally requires both demolition expenses and a demolished building’s remaining tax basis to be added to the basis of nondepreciable land. Owners typically cannot recover those amounts for tax purposes until the land is sold, potentially years or decades later.
  • “This treatment can delay or deter redevelopment projects that would otherwise support increased housing supply and commercial activity, particularly in high-cost areas and downtown corridors facing elevated vacancy rates,” the 14 organizations wrote. (Letter, Sept. 15)
  • Proposed changes: The coalition recommends allowing taxpayers to deduct as a loss any remaining tax basis of a demolished building and allowing taxpayers to deduct the actual demolition expenses. The reforms should be paired with reasonable guardrails to protect historic buildings and ensure timely redevelopment of the property.

  • The issue was recently highlighted in an op-ed written by RER Tax Policy Advisory Committee Chairman Joshua Parker and published in The Hill. (The Hill, Aug. 30 | Roundtable Weekly, Sept. 11)
  • Future legislation in this area could also restore the deductibility of environmental remediation expenses.
  • The recently enacted, bipartisan ROAD to Housing Act removed many barriers to creating new housing. The organizations’ proposal would continue building on these efforts by promoting productive real estate investment.

Data Centers: House Democrats Propose Tax Restrictions
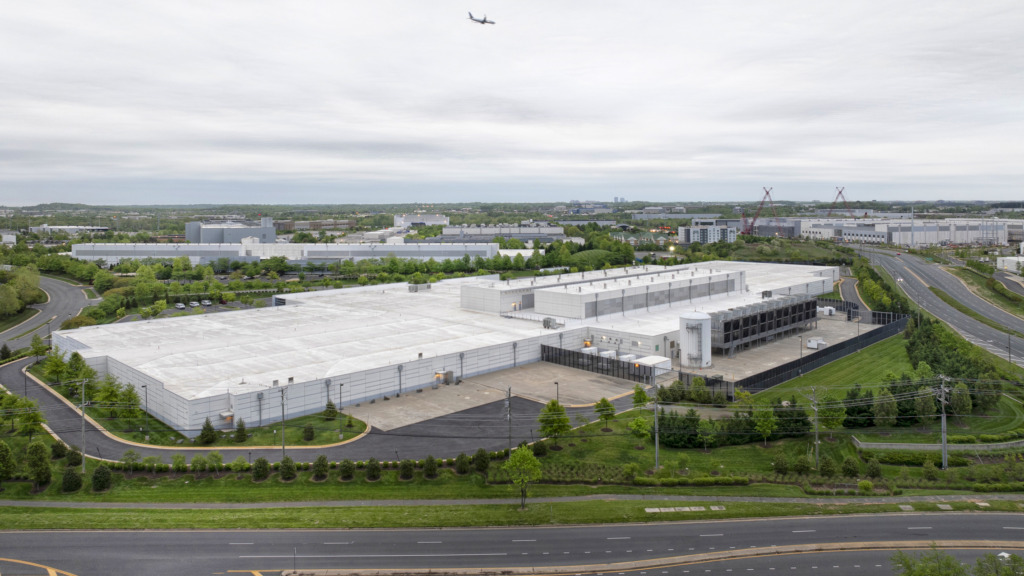
  • Reps. Kristen McDonald Rivet (D-MI) and Don Davis (D-NC) introduced the Reverse Big Ugly Tax Breaks for Data Centers Act on Sept. 16, seeking to exclude covered data centers from investment incentives expanded in the 2025 tax law. (Politico |  Rep. Rivet Press Release, Sept. 16)
  • The bill would deny 100% bonus depreciation and Opportunity Zone eligibility to covered data-center property. Its definition covers facilities exceeding 50 megawatts of maximum rated power capacity or total peak power load, including property dedicated to their operation. (Bill text)
  • The legislation follows an August white paper from Senate Finance Committee Ranking Member Ron Wyden (D-OR) addressing bonus depreciation, Opportunity Zones and REIT treatment for data centers, along with a proposed excise tax on operators. (Senate Finance proposal, Aug. 6 | Roundtable Weekly, Aug. 7)

Partnership Taxes: Second Circuit Rules in Soroban

  • The U.S. Court of Appeals for the Second Circuit on Sept. 17 affirmed the Tax Court’s decision in Soroban Capital Partners LP v. Commissioner, holding that three principals did not qualify for the limited partner exception from self-employment tax because they exercised managerial control over the firm. (Opinion, Sept. 17)
  • The court focused on the partners’ actual responsibilities, including managing investments, serving on governing committees, and directing personnel decisions. It clarified that partners may provide some services and still qualify for the exception if those activities do not involve controlling, managing or running the business. (Bloomberg Law, Sept. 17)
  • The opinion appears to align, at least in significant part, with the Fifth Circuit’s revised approach in K Alain, formerly Sirius Solutions. (Court Opinion | JD Supra, Aug. 12)
  • RER filed an amicus brief supporting the taxpayer in Soroban as part of its broader challenge to the IRS’s restrictive interpretation of the limited partner exception from self-employment tax. RER also filed briefs supporting taxpayers in Sirius Solutions in the Fifth Circuit and Denham Capital in the First Circuit. (Roundtable Weekly, Jan. 30 | Feb. 13 | Sept. 11)

RER will continue working with Congress, Treasury and the IRS to advance tax policies that expand access to capital, encourage redevelopment and support long-term economic growth.

Tax Policy Roundup: Community Revitalization, Opportunity Zones, Foreign Investment, and Judicial Developments

As Congress returns to Washington, The Real Estate Roundtable (RER) is working to advance several tax policy initiatives aimed at expanding housing supply, revitalizing communities, and removing barriers to capital formation for real estate investment.

Tax Policies to Support Community Revitalization

  • On August 30, RER’s Tax Policy Advisory Committee (TPAC) Chairman Joshua Parker published an op-ed in The Hill newspaper setting forth a three-part framework for how lawmakers should think about potential tax policies to support community revitalization. (The Hill, Aug. 30)
  • “Preserve buildings that can serve again,” wrote Parker. “Convert those that can meet a new need. Clear those that cannot and require the land to be rebuilt.”
  • Parker’s op-ed outlines three actionable tax changes advocated by RER to advance this framework: (1) reforming the tax treatment of demolition costs, including the lost tax basis when a building is torn down; (2) strengthening the historic tax credit, and (3) incentivizing commercial-to-residential conversions through the bipartisan Revitalizing Downtowns and Main Streets Act (H.R. 2410).

Opportunity Zones

  • RER is continuing to encourage Treasury and the IRS to move forward with transitional tax guidance that will provide much-needed clarity to Opportunity Zone (OZ) investors pursuing new housing and other real estate projects that straddle the pre- and post-2025 OZ statutory regimes.
  • IRS Notice 2026-40, released in June, embraced several RER recommendations and clarified certain key issues for taxpayers with OZ projects in expiring census tracts. (Roundtable Weekly, June 26)
  • RER followed up the Notice with additional suggestions, and met virtually with Treasury and IRS staff, along with other stakeholders, on Aug. 27. Formal proposed regulations from Treasury are expected before the end of the year. (Letter, July 29 | Roundtable Weekly, July 31)
  • This week, Treasury and the IRS issued proposed regulations implementing new reporting requirements for Qualified Opportunity Funds and Qualified Opportunity Zone Businesses. (PoliticoPro, Sept. 10)

FIRPTA and Tax Barriers to Foreign Investment in US Real Estate

FIRPTA
  • RER is finalizing a request to Treasury to revoke outdated administrative guidance (IRS Notice 2007-55) that creates unnecessary hurdles and tax burdens for foreign investors seeking to deploy capital in US real estate.
  • Notice 2007-55 treats REIT liquidating distributions as a sale of real property rather than the sale of stock, thus subjecting the transactions to tax under FIRPTA. The Notice also treats REIT distributions as ineligible for the section 892 foreign government tax exemption.
  • RER believes the Notice’s conclusions were incorrect at the time, and more recent events strongly favor its repeal.
  • These include changes in the FIRPTA statute since the Notice was issued, growth in the importance of foreign capital to U.S. real estate jobs and investment, and the corrosive effect of 20 year-old sub-regulatory guidance that has never been subject to the formal rulemaking process.

SECA Limited Partner Exception

  • On Aug. 12, the Fifth Circuit withdrew its January opinion in Sirius Solutions and issued a substitute opinion holding that the self-employment tax exception applies to a limited partner who plays “no significant role in managing or running a business.” (JD Supra, Sept. 9)
  • The new standard is a step back from the court’s earlier ruling, which based eligibility on limited liability and state-law limited partner status. However, the court again rejected the Tax Court’s stricter “passive investor” test and remanded the case for further consideration. (Grant Thornton, Aug. 17)
  • RER has filed amicus briefs supporting taxpayers in Sirius and two related appeals—Denham Capital in the First Circuit and Soroban Capital Partners in the Second Circuit. (Roundtable Weekly, Jan. 30 | Feb. 13)

RER will continue engaging with Congress, Treasury, and the IRS to advocate for clear, effective tax rules that expand access to capital, encourage investment and redevelopment, and support long-term economic growth.
View from the CEO: Priorities for the CRE Industry in 2025

With control over the White House and both chambers of Congress decided, attention has turned to how President-elect Donald Trump’s second term will affect the commercial real estate industry.

Looking Ahead

  • As Roundtable President & CEO Jeff DeBoer noted to BisNow last week, the new administration represents a chance to strengthen policymakers’ understanding of the critical role CRE plays in the economy. (BisNow, Nov. 12)
  • “Anytime that there’s a turning of the page, there’s an opportunity to emphasize new issues, or to bring priority to older issues that maybe have been pushed out by previous leaders,” DeBoer told BisNow. DeBoer also highlighted key policy priorities for commercial real estate to move forward in the coming administration, including housing, tax, capital markets, and energy.

Housing Policy

  • Interagency task force: The Roundtable is calling for a federal task force focused on expanding the housing supply, particularly affordable housing. This task force would coordinate efforts across agencies to streamline building processes and reduce regulatory barriers, incentivizing new development across the U.S.
  • Property conversions: The administration should support federal incentives for (such as low interest loans) converting obsolete office buildings into residential housing. Modeled after tax credits for historic preservation, bipartisan legislation like the Revitalizing Downtowns and Main Streets Act could help relieve the national housing shortage. (Roundtable Weekly, July 12)
  • Tariff concerns: Proposed tariffs on materials like lumber, steel, concrete, glass and appliances could impact housing supply: “By putting tariffs on housing materials, you will be indirectly increasing costs for buyers and renters and making it more difficult to solve this housing crisis,” said DeBoer.

Tax Policy

  • With key provisions of the Tax Cuts and Jobs Act of 2017 (TCJA) expiring soon, tax legislation will likely be central to President-elect Trump’s first 100 days.
  • Capital gains: Long-standing elements of the tax code, including the reduced rate for capital gains, the ability to reinvest through like-kind exchanges, and step-up in basis of assets at death, are critical for real estate businesses and encourage productive investment and economic growth. RER will continue to advocate that these provisions be maintained.
  • Section 199A: The qualified business income deduction for pass-through businesses, known as Section 199A, ensures that small businesses can compete on a level playing field with public corporations. RER supports extending the deduction, which is currently set to expire.
  • Foreign investment: Restrictions on foreign investment discourage capital formation and could hinder growth in real estate at a time when increasing the supply and availability of capital is critical to the industry’s recovery. Policymakers should avoid imposing additional restrictions or tax burdens on foreign investors, and consider repealing or reforming the Foreign Investment in Real Property Tax Act (FIRPTA).

Capital Markets

  • Strengthening capital flows in real estate is a top priority, as lending and credit availability have remained relatively weak since the pandemic and are only recently starting to see improvement.
  • Interest rates: Policymakers should carefully consider the inflationary effects of fiscal policies to maintain a favorable interest rate environment. Avoiding increased capital requirements, such as Basel III Endgame proposal, is also necessary to prevent hindering growth.

Energy Policy

  • With the rise of data centers, AI and other energy-intensive sectors, addressing energy capacity and permitting is a critical bipartisan need and “very important” to RER’s agenda, as DeBoer noted.

RER is committed to working proactively and productively with President-elect Trump and the 119th Congress to support the needs of the economy and commercial real estate industry.

The Roundtable Shares 2025 Tax Legislative Agenda with Lawmakers

Responding to a request for input from the chairs of the House Ways and Means Committee and Ways and Means Tax Policy Subcommittee, The Real Estate Roundtable submitted comments on the pending expiration of the Tax Cuts and Jobs Act of 2017 and ways in which tax policy can support long-term investment, economic stability, and the creation of affordable housing. (Letter, Oct. 2)

Roundtable Recommendations

The letter from Roundtable President and CEO Jeffrey DeBoer urges lawmakers to ensure that any major tax legislation in 2025 retain or include:

  • The reduced tax rate on long-term capital gains. The capital gains rate is critical for driving long-term real estate investment and fostering job creation. Raising capital gains rates, taxing unrealized gains, or double-taxing gains at death would deter entrepreneurship, increase costs, and reduce economic mobility.
  • Tax fairness for partnerships and pass-through entities. Half of the nation’s tax partnerships are real estate-related, making these provisions vital to the industry’s success.  Section 199A, which provides a 20% deduction on pass-through business income (including REIT dividend income), allows privately held businesses to compete on a level playing field with large corporations.
  • Like-kind exchanges. Section 1031 allows for the deferral of capital gains through real estate exchanges and helps gets languishing properties into the hands of new owners who will invest in, and improve, them.  Retaining section 1031 is vital to promoting reinvestment in communities, creating opportunities for minority and small business owners, and improving struggling properties.
  • Tax rules that encourage, rather than deter, foreign investment in U.S. real estate. Targeted changes to the outdated and discriminatory Foreign Investment in Real Property Tax Act (FIRPTA) could unlock capital for large-scale real estate and infrastructure projects that create jobs and spur economic development.
  • Incentives for affordable housing, energy efficiency, and community revitalization. The Roundtable supports expanding the low-income housing tax credit (LIHTC), improving the real estate-related clean energy tax provisions in the Inflation Reduction Act, and introducing new incentives for the conversion of obsolete commercial buildings into affordable housing. The letter also calls for a long-term extension of Opportunity Zone (OZ) tax incentives and preserving carried interest tax rules that recognize and reward sweat equity with capital gains treatment.

The Roundtable is committed to working with lawmakers to ensure the U.S. maintains a competitive tax code that encourages capital formation, rewards entrepreneurial risk-taking, and supports critical policy objectives, including accessible and affordable housing and safe and healthy communities.

Final Treasury Rules Expand Reach of FIRPTA Tax Regime

The Treasury Department in Washington, DC

The Treasury Department issued final regulations this week that redefine what constitutes a domestically controlled REIT exempt from tax under the Foreign Investment in Real Property Tax Act (FIRPTA). The regulations create a new look-through rule that extends the reach of the discriminatory FIRPTA regime to common investment structures. (Final Regulations | Tax Notes, April 25 and Bloomberg Law, April 24)

New Look-Through Rule

  • By looking through a domestic C corporation to its shareholders, the new FIRPTA rules run counter to general tax principles, past IRS guidance, and historic precedent.  Moreover, the final regulations do not provide relief to widely held U.S. real estate funds with dispersed foreign ownership, even if the foreign investors are far removed and separate from the management and control of the U.S. funds’ activities. 
  • While the final rules increased the total percentage of foreign ownership of a C corp. necessary to trigger look-through treatment, the change offers little practical relief since participating U.S. investors typically will only invest in U.S. real estate through other channels (e.g., directly, through a partnership, or through a REIT).
  • Transition relief in the final regulations may offer some respite to certain foreign investors, depending on their facts and circumstances. The new look-through rule does not apply to preexisting business arrangements—but only if the entity does not acquire a significant amount of new real estate interests or undergo a significant change in its ownership during the 10-year transition period.

Roundtable Response

FIRPTA
  • Roundtable President and CEO Jeffrey DeBoer responded to the Treasury rules. “Foreign capital is badly needed to supplement domestically sourced capital in cities and downtowns that continue struggling to recover from the pandemic. The wide spread adoption of remote work, coupled with today’s high interest rates and decreased lending by banks is fueling a reinforcing cycle of declining investment, property values, and tax revenues that can only be countered through additional investment capital.”
  • “Unfortunately, the final Treasury rules on FIRPTA and domestically controlled REITs raise new barriers to passive foreign investment in U.S. real estate, including affordable housing and the conversion of underutilized office buildings,” DeBoer said.
  • The Real Estate Roundtable and some members of Congress had advocated for the withdrawal of the proposed regulations or significant changes. House Ways and Means Committee Members Darin LaHood (R-IL) and Carol Miller (R-WV) urged Treasury Secretary Janet Yellen to drop the FIRPTA proposal. (Letter to Yellen, July 28, 2023 and real estate industry coalition letter, March 1, 2023 | Roundtable Weekly: Jan. 6, March 4 and Aug. 4, 2023) 

A Roundtable Tax Policy Advisory Committee (TPAC) working group is reviewing the most recent changes and considering potential policy and tax planning strategies going forward. The next TPAC meeting will be held on June 21 in conjunction with the all-member Roundtable Annual Meeting in Washington, DC.

#  #  #

House Ways and Means Members Call on Treasury to Withdraw FIRPTA Regulatory Proposal

House Ways and Means Committee Members Darin LaHood (R-IL) and Carol Miller (R-WV) recently called on Treasury Secretary Janet Yellen to withdraw a proposed IRS rule that would expand the reach of the Foreign Investment in Real Property Tax Act (FIRPTA) of 1980. The policymakers’ request followed a letter by The Real Estate Roundtable and 14 other real estate trade organizations that urged congressional tax-writing committees to oppose the FIRPTA proposal. (Letter to Yellen, July 28 and Industry coalition letter, March 1)

Retroactive Rewrite for REITs

  • Under current law, shareholders of domestically controlled REITs are not subject to FIRPTA, a statutory regime that subjects foreign investors to capital gains tax on their U.S. property investments.
  • The proposed IRS Look-Through Rule would no longer treat a taxpaying U.S. C corporation that has ownership shares in a REIT as a U.S. person—if more than 25% of the owners of the C corporation are foreign. If enacted, the new rule would trigger FIRPTA capital gains, retroactively, on REITS and investment structures used for decades when planning real estate and infrastructure investments.

Congressional CRE Concerns

buildings cityscape
  • Reps. LaHood and Miller asked Treasury and the IRS to reverse course and withdraw the proposed regulation, stating in their letter, “The proposed regulation’s retroactivity is severely burdensome and is already having a chilling effect on foreign investment, which has been a vital contributor to the economic health of the U.S. commercial real estate market. If Treasury decides to move forward with this proposal, it is imperative that the retroactivity provisions are removed.”
  • The letter also noted the proposed change would limit access to capital at a time when the CRE market is showing signs of destabilization. The House taxwriters added, “We fear this proposal could worsen the commercial real estate outlook and harm the many Americans who rely on these crucial investments in their communities.”

Industry Response

Additionally, The Roundtable, Nareit, American Investment Council, Managed Funds Association, and ICSC submitted comments to Treasury in February in opposition to the proposed look-through rule. The organizations wrote that the regulation would “reverse decades of well-settled tax law, severely misconstrue the statute, and contradict Congressional intent.” (Letter to Treasury, Feb. 27)

#  #  #

Roundtable, Trade Organizations Urge Treasury to Withdraw FIRPTA Regulatory Proposal

The Real Estate Roundtable and 16 other trade organizations weighed in this week against a proposed IRS rule that would expand the reach of the Foreign Investment in Real Property Tax Act (FIRPTA) of 1980.

Retroactive Rewrite

  • On December 29, Treasury and the IRS released proposed regulations that would redefine what constitutes a domestically controlled REIT and impose capital gains taxes, through FIRPTA, on investment structures that taxpayers have used for decades when planning real estate and infrastructure investments in the United States.
  • For purposes of FIRPTA and the exemption for domestically controlled REITs, the proposed look-through rule would no longer treat a taxpaying U.S. C corporation (that is a shareholder of a REIT) as a U.S. person if more than 25% of the owners of the C corporation are foreign. The result would be that many REITs previously exempt from FIRPTA would be thrust, retroactively, into the discriminatory tax regime.

Industry Response

  • On Monday, The Roundtable, Nareit, American Investment Council, Managed Funds Association, and ICSC submitted detailed comments to Treasury urging withdraw of the proposed look-through rule. The organizations wrote that the rule would “reverse decades of well-settled tax law, severely misconstrue the statute, and contradict Congressional intent,” as well as potentially “impair real estate’s access to foreign capital at a critical economic juncture and undermine foreign investors’ confidence in the stability and predictability of U.S. tax rules.” (Letter to Treasury, Feb. 27)
  • On Wednesday, The Roundtable and 14 other real estate trade organizations wrote to the congressional tax-writing committees asking Members of Congress to encourage the Treasury Department and IRS to withdraw the rule, which could put property value, jobs, and communities at risk unnecessarily. (Letter to congressional tax committees, March 1)
  • Treasury’s regulatory package also included favorable final rules regarding the FIRPTA foreign pension fund exemption and a helpful proposal related to real estate investments and the tax exemption for foreign governments.

The principal drafters of the Treasury comment letter were Roundtable Tax Policy Advisory Committee (TPAC) members David Levy (Weil Gotshal) and David Polster (Skadden), as well as Nickolas Gianou (Skadden). TPAC members also met virtually with Treasury officials on February 15 to discuss the proposed regulation. TPAC will remain active and engaged with the administration on this issue as the process unfolds.

#  #  #

Treasury Dept. Issues New Rules on Taxation of Foreign Investment in U.S. Real Estate

Foreign Investment in Real Property Act - book

On December 28, Treasury and the IRS released new tax regulations affecting foreign investment in U.S. real estate. 

FIRPTA

  • Among the changes, a proposed rule would repeal a long-standing private letter ruling that foreign investors have relied on when structuring inbound investments. 
  • Under current law, shareholders of domestically controlled REITs are not subject to the Foreign Investment in Real Property Tax Act (FIRPTA)—a statutory regime that subjects foreign investors to capital gains tax on their U.S. property investments. 
  • The proposal, if finalized, would expand the reach of FIRPTA by denying a REIT’s status as domestically controlled if a U.S. corporate shareholder of the REIT is foreign-owned. In other words, the rule would look through a domestic C corporation that owns the REIT, even if the C corporation is a U.S. taxpayer that pays U.S. income tax. 
  • The proposed regulation surprised foreign investors and real estate fund managers who have relied on a 2009 IRS private lettering rule, which held that a domestic C corporation that owns shares in a REIT is a U.S. owner for purposes of determining whether the REIT is domestically controlled. 
  • The proposed rule appears to conflict with policies underlying FIRPTA-related ownership attribution changes enacted in the 2015 PATH Act.  As a practical matter, the tax consequences of the proposal are retroactive because they would apply to existing investments made years ago. (Weil Tax Alert and Skadden Insights)

Additional Provisions & Regulations

Treasury Department

  • Other provisions in the proposed regulations are more favorable. For example, they include rules that allow a sovereign wealth fund to preserve the tax exemption applicable to foreign governments if the fund has only a minority, non-controlling interest in a U.S. real estate business. 
  • Simultaneously, Treasury also released final regulations last month related to the FIRPTA exemption for foreign pension funds, which the Roundtable worked to enact in 2015. The final regulations are largely positive and should facilitate even greater investment in U.S. real estate by qualified foreign pension funds. 

The Real Estate Roundtable’s Tax Policy Advisory Committee (TPAC) has created a working group to develop formal comments and respond to the recent Treasury releases.

#  #  #

Treasury Secretary Mnuchin Addresses FIRPTA Reform at House Ways and Means Hearing


Testifying before the House Ways and Means Committee on the President’s FY 2021 budget, Treasury Secretary Steven Mnuchin was questioned this week on the Foreign Investment in Real Property Tax Act (FIRPTA) and addressed potential steps he could take to encourage greater real estate investment from abroad.  (Watch 2:35 video of March 3 exchange with Mnuchin)

  • During the hearing’s Q&A with Secretary Mnuchin, committee member Kenny Marchant (R-TX) noted a recent letter that he and other GOP taxwriters sent to the Treasury Department urging a reevaluation of FIRPTA and related IRS guidance (Notice 2007-55).  
  • The congressional letter, led by Ways and Means Republican Devin Nunes (R-CA), encourages Treasury to withdraw section two of the IRS Notice, which effectively imposes U.S. capital gains tax on the liquidating distributions of domestically controlled real estate investment trusts (REITs).   Often, when a foreign investor is a minority partner in a U.S. real estate or infrastructure investment, the joint venture employs a domestically controlled REIT structure.
  • The 16 signatories of the February 20 letter wrote, “repealing the IRS Notice will restore the intent of Congress with respect to the tax law governing liquidations, provide parity to investors, and increase direct foreign investment in U.S. commercial real estate and infrastructure in every corner of the nation.”
  • During the hearing, Rep. Marchant called attention to the letter – and noted the IRS guidance applies FIRPTA to previously untaxed transactions involving domestically controlled REITs.  
  • Mnuchin responded that the Feb. 20 letter prompted a briefing at Treasury this week – and that he shares the concerns the letter  raises about FIRPTA.  “[I]t makes no sense that we discriminate against foreign investors,” Mnuchin said.  “But in my mind, anything we can do legally to encourage those investments we will do.  So thank you for the letter.  We are reviewing it.  It is at the top of my list,” he added. (Watch 2:35 video of Marchant and Mnuchin)
  • During another Ways and Means tax hearing last month, Rep. Marchant said, “FIRPTA is an outdated, discriminatory law.  It applies to no asset class other than real estate and infrastructure … Economic studies indicate repealing FIRPTA could drive $65 to $125 billion in new investment.”  (Watch video of Feb. 11 FIRPTA exchange).  Rep. Marchant is lead sponsor of the bipartisan Invest in America Act (H.R. 2210), a bill that would repeal the entire FIRPTA law. 
  • A similar letter was sent on December 18, 2019 to Secretary Mnuchin by a bipartisan group of 11 Senate Finance Committee Members led by Sen. Robert Menendez (D-NJ) – a longtime lead sponsor of FIRPTA repeal bills.  Another bipartisan letter to Secretary Mnuchin urging repeal of the IRS Notice was signed by 32 Representatives of the House Ways and Means shortly before introduction of the Tax Cuts and Jobs Act of 2017 (TCJA). (Roundtable Weekly, Dec. 20, 2019)

Members of the Roundtable’s Tax Policy Advisory Committee (TPAC) have met with Treasury officials on multiple occasions to discuss the harm caused by IRS Notice 2007-55.  Leading industry experts also convened on Oct. 30 at the National Press Club in Washington for an in-depth discussion the economic damage incurred by the IRS Notice.  An industry coalition is scheduled to meet with officials in Treasury’s Office of Tax Policy next week to discuss the issue.

#  #  # 

House Ways & Means Republicans Ask Treasury Secretary Mnuchin to Boost Investment, Create Jobs by Easing FIRPTA Tax Burden

Treasury Department

Over three-quarters of the Republican Members of the House Ways and Means Committee on Feb. 20 urged Treasury Secretary Steven Mnuchin to remove tax barriers to foreign investment in U.S. real estate and infrastructure.  

  • The congressional letter, led by Representative Devin Nunes (R-CA), encourages Treasury to withdraw section two of IRS Notice 2007-55.  The Notice, which relates to the Foreign Investment in Real Property Tax Act (FIRPTA), effectively imposes U.S. capital gains tax on the liquidating distributions of a domestically controlled REIT. 
  • Domestically controlled REITs commonly are employed in joint ventures where a foreign investor is a minority partner in a U.S. real estate or infrastructure investment.  Prior to the Notice, a liquidating distribution from a domestically controlled REIT was treated as nontaxable sale of stock for tax purposes. 
  • The 16 signatories of the February 20 letter wrote that “repealing the IRS Notice will restore the intent of Congress with respect to the tax law governing liquidations, provide parity to investors, and increase direct foreign investment in U.S. commercial real estate and infrastructure in every corner of the nation.”
  • The Ways and Means Republican letter comes on the heels of a high-profile exchange on the broader economic harm caused by FIRPTA at a recent Ways and Means tax hearing.  At the hearing, Rep. Kenny Marchant (R-TX), said that “FIRPTA is an outdated, discriminatory law.  It applies to no asset class other than real estate and infrastructure . . . Economic studies indicate repealing FIRPTA could drive $65 to $125 billion in new investment.” Rep. Marchant is lead sponsor of the bipartisan Invest in America Act (H.R. 2210), a bill to repeal FIRPTA altogether.  (Watch video of Feb. 11 FIRPTA exchange)
  • In conjunction with The Roundtable’s Tax Policy Advisory Committee (TPAC) meeting on January 29, Darin Mellott, Director of Americas Research at CBRE shared updated data indicating that foreign capital represented only 10 percent of total transaction volume between 2007 and 2019 – further evidence that FIRPTA weighs heavily on potential inbound investment.  In other asset classes, such as manufacturing, foreign capital represents a much larger share of overall investment. 
  • A letter similar to the House Republican letter was sent by a bipartisan group of 11 Senate Finance Committee Members to Secretary Mnuchin on December 18, 2019.  The December letter was led by Sen. Robert Menendez (D-NJ), a longtime lead sponsor of bills to roll back FIRPTA, and Sen. Johnny Isakson (R-GA).  A bipartisan House Ways and Means Committee letter urging repeal of the Notice and signed by 32 Representatives was sent to Secretary Mnuchin shortly before introduction of the Tax Cuts and Jobs Act of 2017 (TCJA). ( Roundtable Weekly , Dec. 20, 2019)

Members of the Roundtable’s Tax Policy Advisory Committee have met with Treasury officials on multiple occasions to discuss the harm caused by IRS Notice 2007-55.  Since 2017, Treasury’s regulatory agenda has focused on implementing the TCJA.  With TCJA implementation nearly complete, The Roundtable is now urging Treasury officials to give the Notice the attention it merits.

#  #  #