Tax Policy Roundup: Lame-Duck Outlook, Opportunity Zones and Data Center Proposals

The November elections will shape the prospects for year-end tax legislation, with a crowded lame-duck agenda leaving limited room for a bipartisan package. Treasury and the IRS are also advancing guidance affecting real estate investment, while lawmakers continue to pursue new limits on data center tax incentives.

Lame-Duck Outlook

  • Lawmakers will return to Washington with just 24 legislative days to address government funding beyond Dec. 11, the annual defense policy bill and other expiring programs. Those negotiations could provide a vehicle for a limited tax package. (Politico, Oct. 13)
  • Potential provisions could include renewing the Work Opportunity Tax Credit, improving IRS administration, and making targeted corrections to the 2025 tax law. A narrow bipartisan agreement appears more achievable than a broader tax bargain, with cost and competing party priorities remaining obstacles. (WilmerHale, Oct. 14)
  • Control of the next Congress will influence whether lawmakers negotiate a year-end agreement or defer major decisions until 2027. Another Republican reconciliation bill remains uncertain, with Senate Majority Leader John Thune (R-SD) acknowledging the difficulty of securing sufficient votes. (Politico, Oct. 13 | Thomson Reuters, Oct. 15)
  • Senate Minority Leader Chuck Schumer (DNY) stated in a recent interview, “The lame duck will be quite different if we win the Senate,” he said. “Same thing if they win the House, and same thing if we win both or neither.” (Politico, Oct. 13)

Opportunity Zones and Tax Guidance
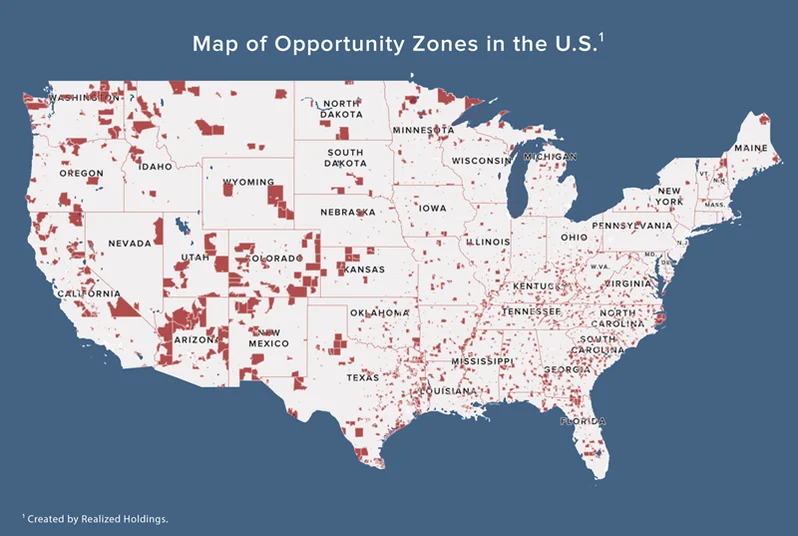
  • OZ deadlines: State nominations for new OZ maps have been extended and are now due Oct. 28, while comments on proposed reporting rules and broader program implementation are due Oct. 26 and Nov. 23, respectively. (Roundtable Weekly, Sept. 25 | Federal Register, Sept. 28 | IRS, Sept. 22)
  • RER advocacy: RER’s Opportunity Zone Working Group met with Treasury and IRS officials in August and has urged clear transition rules that allow existing projects to continue under the permanent program. (Roundtable Weekly, Sept. 25)
  • Treasury and the IRS recently released their 2026–2027 Priority Guidance Plan, outlining 121 tax guidance projects, including rules on Opportunity Zones, business interest deductibility, bonus depreciation and the Section 199A pass-through deduction. (Treasury–IRS Priority Guidance Plan, Sept. 29)
  • These administrative decisions will help determine how provisions of the 2025 tax law operate regardless of congressional action.

Data Center Tax Proposals
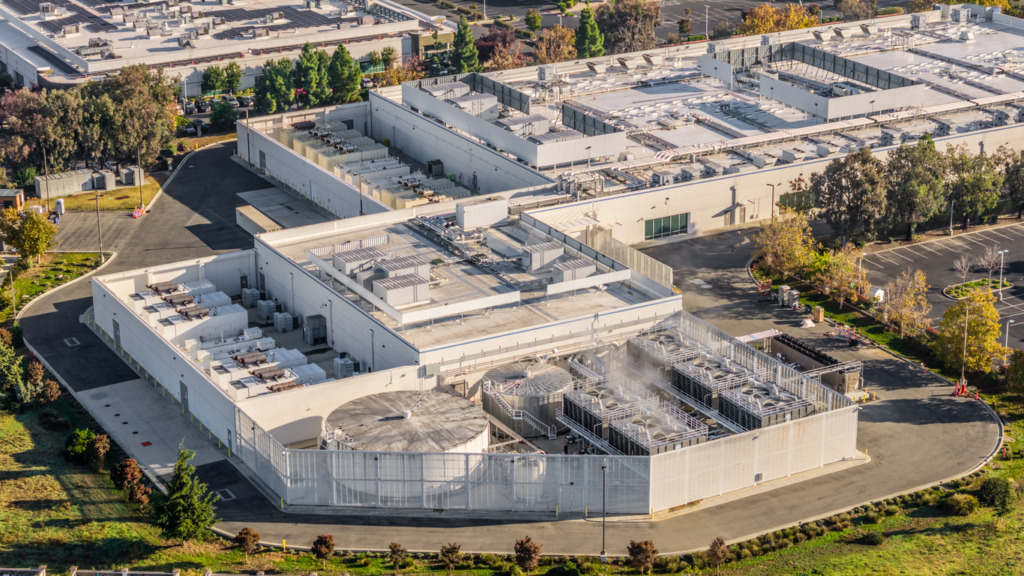
  • Sen. Peter Welch (D-VT) urged the IRS to examine whether major technology companies are improperly claiming research and experimentation tax credits for AI data center development. His Oct. 7 letter requests information on claims, enforcement, and potential guidance changes. (Sen. Welch Press Release, Oct. 8)
  • Sen. Welch’s inquiry follows proposals from Senate Finance Committee Ranking Member Ron Wyden (D-OR), Sen. Josh Hawley (R-MO) and House Democrats targeting data center tax treatment. (PoliticoPro, Oct. 14)
  • The proposals include restrictions on OZ eligibility and bonus depreciation; Wyden’s framework also targets certain REIT rents and proposes an operator excise tax. (Roundtable Weekly, Aug. 7 | Roundtable Weekly, Sept. 25 | Axios, Oct. 8)
  • A separate report led by Sen. Elizabeth Warren (D-MA) criticized data center companies’ energy-cost commitments and pursuit of state and local tax incentives. (Sen. Warren Press Release, Oct. 9)

Roundtable on the Road

  • In his prepared remarks, DeBoer highlighted that “[r]eal estate development is not just about buildings; it is a macro-economic engine that provides funding for local and national budgets, creates millions of jobs and structurally supports the long-term retirement goals of everyday Americans through pension funds and institutional portfolios.”

DeBoer also called for policies that reward capital investment, lower housing production costs, accelerate commercial-to-residential conversions, remove regulatory barriers, and expand private investment in housing and community redevelopment.
New Senate Legislation Takes Aim at Wall Street but Threatens to Disrupt U.S. Real Estate

Legislation introduced in the House and Senate on Sept. 24 aims to fundamentally reform the private equity industry, but the expansive legislation could cause major disruption to U.S. real estate values and markets.

The newly revised Stop Wall Street Looting Act, introduced by Sen. Elizabeth Warren (D-MA) and seven other Democratic senators, as well as a coalition of progressive House members, would raise the tax rate on REIT investors, end capital gains treatment for carried interest, and greatly restrict the deductibility of interest on real estate borrowing. (Senate Banking Committee, Sept. 24 | Bill Text)

State of Play

  • Sponsors seek to rein in investment by private funds. The bill authors seek to build on their successful effort this summer to expand the government’s role in regulating private investment in single-family rental housing. The legislation would impose restrictions on the activities of private funds, including their acquisitions, distributions, and business operations such as outsourcing jobs or closing facilities. (Section-by-Section Summary, Sept. 24)
  • Legislation’s reach extends beyond Wall Street. The legislation would have far-reaching consequences for REITs, REIT investors, and real estate generally. While the sponsors highlight a specific case involving REIT ownership of health care-related property, the bill would raise the tax rate on all REIT investors by repealing the 20% deduction for qualified REIT dividends (Section 199A). (Section-by-Section Summary, Sept. 24)
  • Carried interest. The bill also incorporates the Carried Interest Fairness Act (S. 445), introduced by Sen. Tammy Baldwin (D-WI). The Carried Interest Fairness Act would recharacterize all carried interest income as ordinary income rather than capital gains. (Section-by-Section Summary, Sept. 24)
  • Interest deductibility. The bill would restrict business interest deductions under Section 163(j) for certain businesses controlled by private investment funds if the business has a rate of leverage (debt-to-equity ratio) greater than 50%. The proposal would calculate leverage using the adjusted basis of a business’s assets rather than market value, potentially overstating the leverage on appreciated real estate. Qualifying businesses that meet the bill’s conditions would also lose access to the existing real estate exception from the Section 163(j) limitation. (Section-by-Section Summary, Sept. 24)
  • Health care real estate and fund fees. Other provisions would prohibit federal health care payments to certain entities that sell or pledge assets to REITs and modify rules governing taxable REIT subsidiaries that operate health care properties. Additionally, it would impose a 100% tax on certain fees, often called “monitoring” or “transaction” fees, paid by fund-controlled companies to private fund managers. (Section-by-Section Summary, Sept. 24)
  • Outlook for the bill. While action on the legislation is unlikely in the near term, the sponsors will likely seek to include some or all of the provisions in tax legislation next year if control of either chamber changes.

Why It Matters

  • Taken together, the proposed changes could affect a broad range of real estate businesses and investors beyond private equity funds. Eliminating the Section 199A deduction for qualified REIT dividends and changing the tax treatment of carried interest would increase tax burdens and discourage investment in real estate partnerships, REITs, and development projects. (RER Carried Interest Fact Sheet, Jan. 2026)
  • Restrictions on interest deductions could create additional financing challenges for real estate owners by increasing after-tax borrowing costs, reducing property values, and complicating the refinancing of maturing debt. Because debt is a fundamental source of financing for commercial real estate investment and development, the changes could also constrain capital availability and discourage new investment. (RER Policy Priorities, Tax)

Roundtable Advocacy

  • The Real Estate Roundtable (RER) has consistently opposed proposals to tax all carried interest as ordinary income, emphasizing that carried interest reflects the entrepreneurial risk and “sweat equity” contributed by general partners to real estate ventures. RER has warned that such changes could affect 2.2 million real estate partnerships and 9.7 million partners nationwide. (RER Carried Interest Fact Sheet, Jan. 2026)
  • Beyond carried interest, RER has advocated for preserving the Section 199A deduction for pass-through businesses and qualified REIT dividends, as well as the real estate exception from Section 163(j). In an October 2025 letter to Treasury and the IRS, RER urged regulators to allow real estate businesses to revisit prior Section 163(j) elections to access bonus depreciation benefits restored under the 2025 tax law. (RER Letter, Oct. 17, 2025)

RER will continue working with policymakers to oppose tax provisions that could undermine real estate investment, financing, and development, while advocating for policies that support capital formation and the stability of U.S. real estate markets.

Opportunity Zone Rules and Maps Take Shape as Congress Weighs Data Center Limits

As states finalize the next Opportunity Zone maps, Treasury and the IRS are seeking input on program rules while lawmakers weigh whether data centers should qualify for OZ tax benefits.

Treasury Seeks Input on OZ Rules

  • In a Sept. 22 notice, Treasury and the IRS requested comments on how to implement the permanent OZ program, specifically regarding housing investment, working capital rules, operating businesses and the tax treatment of long-held investments. Comments are due Nov. 23. (Tax Notes, Sept. 22 | Bloomberg Law, Sept. 23)
  • The request follows proposed regulations issued Sept. 11 on reporting requirements for Qualified Opportunity Funds (QOFs) and OZ businesses, as well as fund certification and decertification. Comments on that separate proposal are due Oct. 16. (PoliticoPro, Sept. 10)

RER Advocacy

  • RER’s Opportunity Zone Working Group has urged Treasury and the IRS to adopt clear, workable rules that allow existing projects to continue through the transition to the permanent program.  The Group also recently met with Treasury and IRS staff in August to discuss guidance for projects spanning the original and permanent OZ programs.
  • The new maps and forthcoming rules will shape where and how OZ capital can support housing, redevelopment and other projects in low-income communities.

New Opportunity Zones Maps

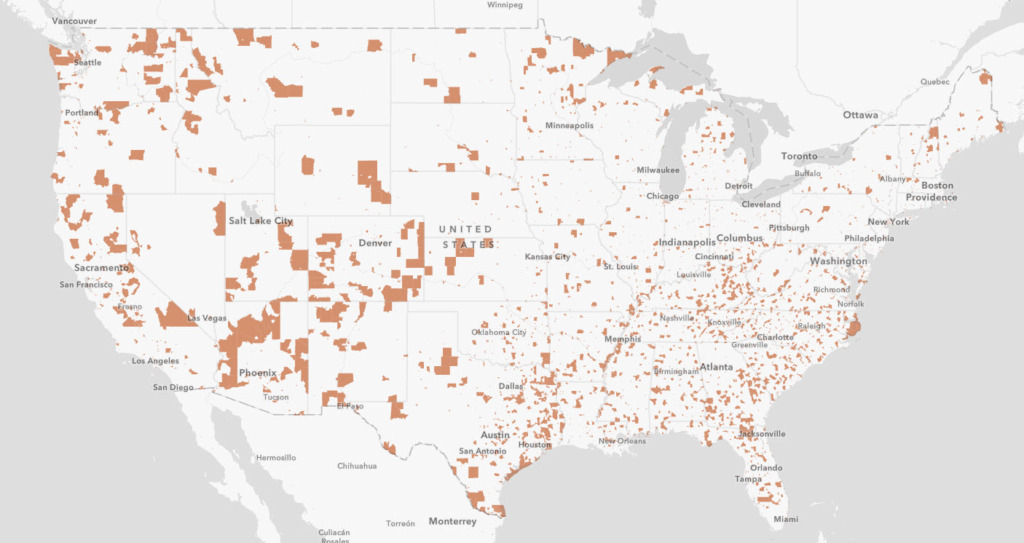
  • Governors are finalizing nominations for the next generation of OZs ahead of a Sept. 28 deadline, with a 30-day extension available upon request. Treasury will certify the new designations, which take effect Jan. 1, 2027 and remain in place for 10 years.
  • The tighter eligibility rules are expected to significantly reduce the number of designated OZs. Roughly, 6,500 zones could be selected nationwide, nearly 26% fewer than the 8,764 designated under the original program. (Bisnow, Sept. 15)
  • The designation process will help determine where new OZ-supported investment can occur beginning in 2027. While the original program attracted significant multifamily investment, developers are now pursuing designations for a broader range of real estate projects, including mall redevelopments and data centers. (Bisnow, Sept. 15)

Data Center OZ Legislation

RER will continue working with Congress, Treasury, and the IRS to secure and improve  OZ rules to ensure the incentives support economic development and job growth, new sources of local tax revenue,  and expanded housing supply.

Senate Proposal Would Impose Tax Penalties on Data Centers

Senate Finance Committee Ranking Member Ron Wyden (D-OR) on Thursday unveiled a white paper that proposes the elimination of several federal incentives for new data center investment and a new excise tax on data center operations. (Senate Finance Committee Press Release| Politico, Aug. 6)

Data Center Tax Proposal

  • Sen. Wyden’s proposal would prohibit Opportunity Zone funds from investing in new data centers, subject capital assets used to build and supply data centers to longer cost recovery periods than assets used for other purposes, and effectively deny investors’ ability to participate in new data center investment through REITs. (White Paper, Aug. 6)
  • The proposal would also impose a gross receipts excise tax on U.S. data center operators. (White Paper, Aug. 6)
  • The white paper cites the current construction boom as evidence that the changes are justified, while stating the proposal “will not end data center development or put at risk the U.S. maintaining its status as the global leader in AI and other innovative technologies.” (PoliticoPro, Aug. 7)
  • While Sen. Wyden’s statement describes the tax provisions as removing “existing investment incentives,” in actuality the changes would create discriminatory tax penalties that expressly exclude data centers from general, long-standing rules that apply broadly to other forms of capital investment.
  • U.S. data center construction has quadrupled over the past four years, according to the white paper, which also cites roughly $700 billion in projected spending this year. Revenue from the proposed tax changes would be directed toward workers and communities affected by AI-driven economic disruption (White Paper | NOTUS, Aug. 6)
  • Sen. Wyden is seeking comments on the framework through Aug. 31 and expects to release legislative discussion draft language this fall. (AI Weekly, Aug. 7)

Why It Matters

  • Data center development is increasingly connected to a broader infrastructure ecosystem. A recent Academy Securities report identifies the federal Enhanced Use Lease (EUL) program as an emerging catalyst for digital infrastructure and domestic supply chains, noting that the Army, Air Force, and Department of Energy have increasingly used the program to facilitate data center development on underutilized government land. (July 29)
  • The model also leverages private capital for infrastructure development. The private-sector lessees under EUL arrangements bear the costs of financing, designing, building, operating, and securing facilities—illustrating the role private investment can play in meeting growing infrastructure needs.
  • With energy demand surging, real estate is an important partner in supporting energy investment, increasing efficiency, and delivering energy savings across the economy.
  • Meanwhile, in mid-August, the North American Electric Reliability Corp. (NERC) is expected to issue federal registration requirements and grid reliability standards for owners and operators of data centers. NERC’s imminent proposed standards could result in the first federal-level regulations on data centers. (Roundtable Weekly, July 17 | 24)

Permitting Reform

  • Bipartisan Senate permitting negotiations will continue beyond the August recess, with Sens. Shelley Moore Capito (R-WV), Sheldon Whitehouse (D-RI), Mike Lee (R-UT), and Martin Heinrich (D-NM) now targeting September for a potential agreement. Negotiators report progress, though significant issues remain over transmission, renewable energy projects, and historic preservation reviews. (E&E News, Aug. 5)

The House and Senate are scheduled to return to Washington on Sept. 14, leaving a narrow legislative window to advance permitting reform and other priorities before the midterm elections.

Roundtable Submits Recommendations to Further Improve New Opportunity Zone Transition Relief

The Real Estate Roundtable (RER) submitted comments this week on IRS Notice 2026-40, welcoming the guidance as an important step in the transition from Opportunity Zones (OZ) 1.0  (TCJA) to the permanent OZ framework enacted under the One Big Beautiful Bill (OB3) Act. RER urged the Treasury Department and IRS to clarify the Notice’s Written Plan and Ordinary Course safe harbors for multiphase investments and allow opportunity funds to continue investing in OZ 1.0 census tracts through their statutory expiration on Dec. 31, 2028. (Letter, July 29)

OZ Transition Recommendations

  • The Notice incorporated several concepts previously recommended by RER and has helped unlock capital that had been delayed by uncertainty surrounding investments in expiring OZ 1.0 census tracts. (Roundtable Weekly, June 26)
  • Post-2026 investments in OZ 1.0 census tracts must comply with either (1) the “Written Plan” exception, which requires compliance with the existing working capital safe harbor rules and related funding requirements; or (2) the “Ordinary Course” exception, which relates to the purposes of the expenditures (e.g., the permissible modernization or continued operations of the trade or business, as opposed to impermissible expansion of the business or starting a new trade or business).
  • RER’s July 29 comments urged Treasury to make both exceptions clear and workable for real estate investors, developers, and entrepreneurs undertaking long-term and multiphase projects. (Letter, July 29)
  • Additional clarifications would provide helpful certainty, reduce regulatory risk, and further unlock capital for greater investment in low-income communities. (Letter, July 29)
  • Under the Written Plan exception, RER asked Treasury to confirm that capital provided after 2026 does not need to come from the same Qualified Opportunity Fund (QOF) that financed the project earlier and that subsequent phases of an existing real estate business may qualify. (Letter, July 29)
  • For the Ordinary Course exception, RER requested administrable rules distinguishing permissible upgrades—such as energy-efficiency measures, accessibility improvements and interior reconfigurations—from business expansions. The letter also seeks clarity for projects involving new floors, conversions of existing space, parking structures, and other improvements that may fall between those categories.
  • RER also asked Treasury to allow new QOF equity to fund qualifying ordinary-course improvements, rather than requiring projects to rely on debt, existing cash, or non-QOF equity.
  • RER further encouraged Treasury to allow QOFs in OZ 1.0 census tracts to continue investing and acquiring property outside the two exceptions through the tracts’ statutory expiration on Dec. 31, 2028—two years longer than contemplated by the Notice. (Letter, July 29)

RER Advocacy

  • RER has consistently urged Treasury and the IRS to provide workable transition rules for OZ 1.0 projects, including through a December 2025 letter, follow-up comments and draft guidance submitted by RER’s Opportunity Zone Working Group in March 2026, and meetings with agency officials. (Roundtable Weekly, March 6) (Roundtable Weekly, Dec. 2025)

RER’s Opportunity Zone Working Group will continue engaging with Treasury and the IRS to support clear, workable implementation of the permanent OZ framework.

IRS Issues Long-Awaited Transition Guidance for Opportunity Zones

The Treasury Department and IRS issued new guidance last week, IRS Notice 2026-40, providing transition rules for Opportunity Zone investments made or initiated under the original OZ 1.0 regime.

The notice previews rules Treasury and IRS intend to include in forthcoming regulations. It focuses on new OZ designations going forward, transition rules for investors with existing deferred gains, and transition rules for Qualified Opportunity Funds (QOFs) and Qualified Opportunity Zone Businesses (QOZBs) operating in OZs designated under the prior law. (Tax Notes, June 18 | Reuters, June 22)

Why It Matters

  • The guidance is a major development for Opportunity Funds and OZ businesses with projects in OZ 1.0 census tracts as the program transitions to the new permanent OZ framework under the One Big Beautiful Bill (OB3)Act.
  • While the OB3 Act permanently extended and improved the OZ tax incentives, it left unresolved tax questions affecting investments in expiring OZ 1.0 tracts, including how far along a project must be before a census tract expires and whether future capital expenditures can continue to qualify for the tax incentives.

The Notice

  • Under the notice, property acquired after Dec. 31, 2026, in a previously designated OZ may still qualify if certain conditions are met. (Seyfarth, June 23)
  • To qualify, the OZ business must have a written working capital plan in place by Dec. 31, 2026; future property acquisitions must be consistent with that plan; the business must receive at least 10% of its estimated working capital assets by year-end; and it must expend at least 5% of those assets by Dec. 31, 2026. (IRS Notice 2026-40, June 18)
  • The notice also clarifies how OZ compliance tests apply after an OZ 1.0 census tract expires. In certain cases, a previously designated OZ can continue to be treated as a qualifying zone for purposes of the “substantial use” test and the requirement that at least 50% of a business’s gross income be derived from the active conduct of a trade or business in a qualified OZ. (IRS Notice 2026-40, June 18 | Reuters, June 22)
  • The guidance provides important certainty for real estate investors, developers, and businesses seeking to move forward with projects in low-income communities during the transition from OZ 1.0 to the new permanent OZ framework.

RER Advocacy

  • RER emphasized that unresolved questions surrounding expiring census tract designations could delay projects, discourage new fund formation, and undermine housing production and community development efforts.
  • While the notice includes many important details that remain under review, its issuance marks a major step forward in providing greater certainty for long-term OZ investment in underserved communities.

RER’s Opportunity Zone Working Group will review the implications of Notice 2026-40 in the days ahead and continue to engage with Treasury and the IRS to support clear, workable implementation of the new OZ framework.

Treasury Extends Tax Relief to Foreign Governmental Investors in U.S. Real Estate

The U.S. Department of the Treasury and Internal Revenue Service (IRS) took a positive step last Friday in response to The Real Estate Roundtable (RER) and other stakeholder concerns, partially withdrawing and modifying proposed regulations on the taxation of sovereign wealth funds and other foreign governmental investors. (Treasury Press Release, May 29)

Why It Matters

  • Foreign investment, including investment by sovereign wealth funds, foreign pension funds, and other government entities, is a critical source of financing for capital-intensive U.S. real estate projects.
  • Section 892 of the tax code generally exempts from U.S. tax certain dividends, interest, and gains earned by foreign governments, unless the income is treated as commercial activity income or income from a controlled commercial entity. Foreign investors rely heavily on Section 892 when planning and structuring U.S. real estate investments.
  • In December, Treasury issued proposed regulations addressing two key questions under Section 892: (1) when a foreign government has effective control of an entity engaged in commercial activities, and (2) when an acquisition of debt is considered commercial activity. (Tax Notes, June 1)
  • The new regulations published on June 1 would ensure that existing foreign government investments, as well as investments acquired during a transition period, are not subject to the more stringent standards in the 2025 proposed rules. (Skadden, May 29)
  • As Treasury and the IRS continue to evaluate the underlying substantive issues, this most recent action ensures that the new rules will not retroactively increase the tax burden on existing real estate investments or have a chilling effect on foreign real estate investments currently under consideration.

RER Advocacy

  • In February, RER submitted comments urging Treasury to avoid imposing a retroactive new tax on existing investments and recommended clear grandfathering and transition rules as part of any final Section 892 regulations. The new Treasury proposal is a positive step that directly addresses those concerns. (Letter | Roundtable Weekly, Feb. 13 | Feb. 27)
  • RER also provided detailed comments on the underlying section 892 issues, urging Treasury to clarify that customary minority investor protections do not create effective control, confirming withholding agents may rely on foreign government self-certifications, and establishing safe harbors for certain debt-related situations. (Roundtable Weekly, Feb. 27)
  • In March, TPAC Chair Joshua Parker (Founder, Chairman and CEO, Ancora) reinforced RER’s concerns in a Bloomberg Tax op-ed urging Treasury to modernize Section 892 rules without discouraging sovereign investment in U.S. real estate and other long-term assets. (Roundtable Weekly, March 13)

What’s Next

  • Treasury Secretary Scott Bessent said the new guidance provides certainty for current investments and transition relief for sovereign investors, while Treasury continues to evaluate feedback to “uphold established market practices” and maintain a stable environment for sovereign wealth fund investment. (Treasury Press Release, May 29)
  • Treasury has not yet modified the substantive provisions related to effective control, commercial activity, and acquisitions of debt.
  • RER will continue working with Treasury and IRS to ensure final Section 892 rules preserve foreign government capital flows into U.S. real estate while maintaining the statute’s distinction between tax-exempt investment activity and taxable commercial activity.

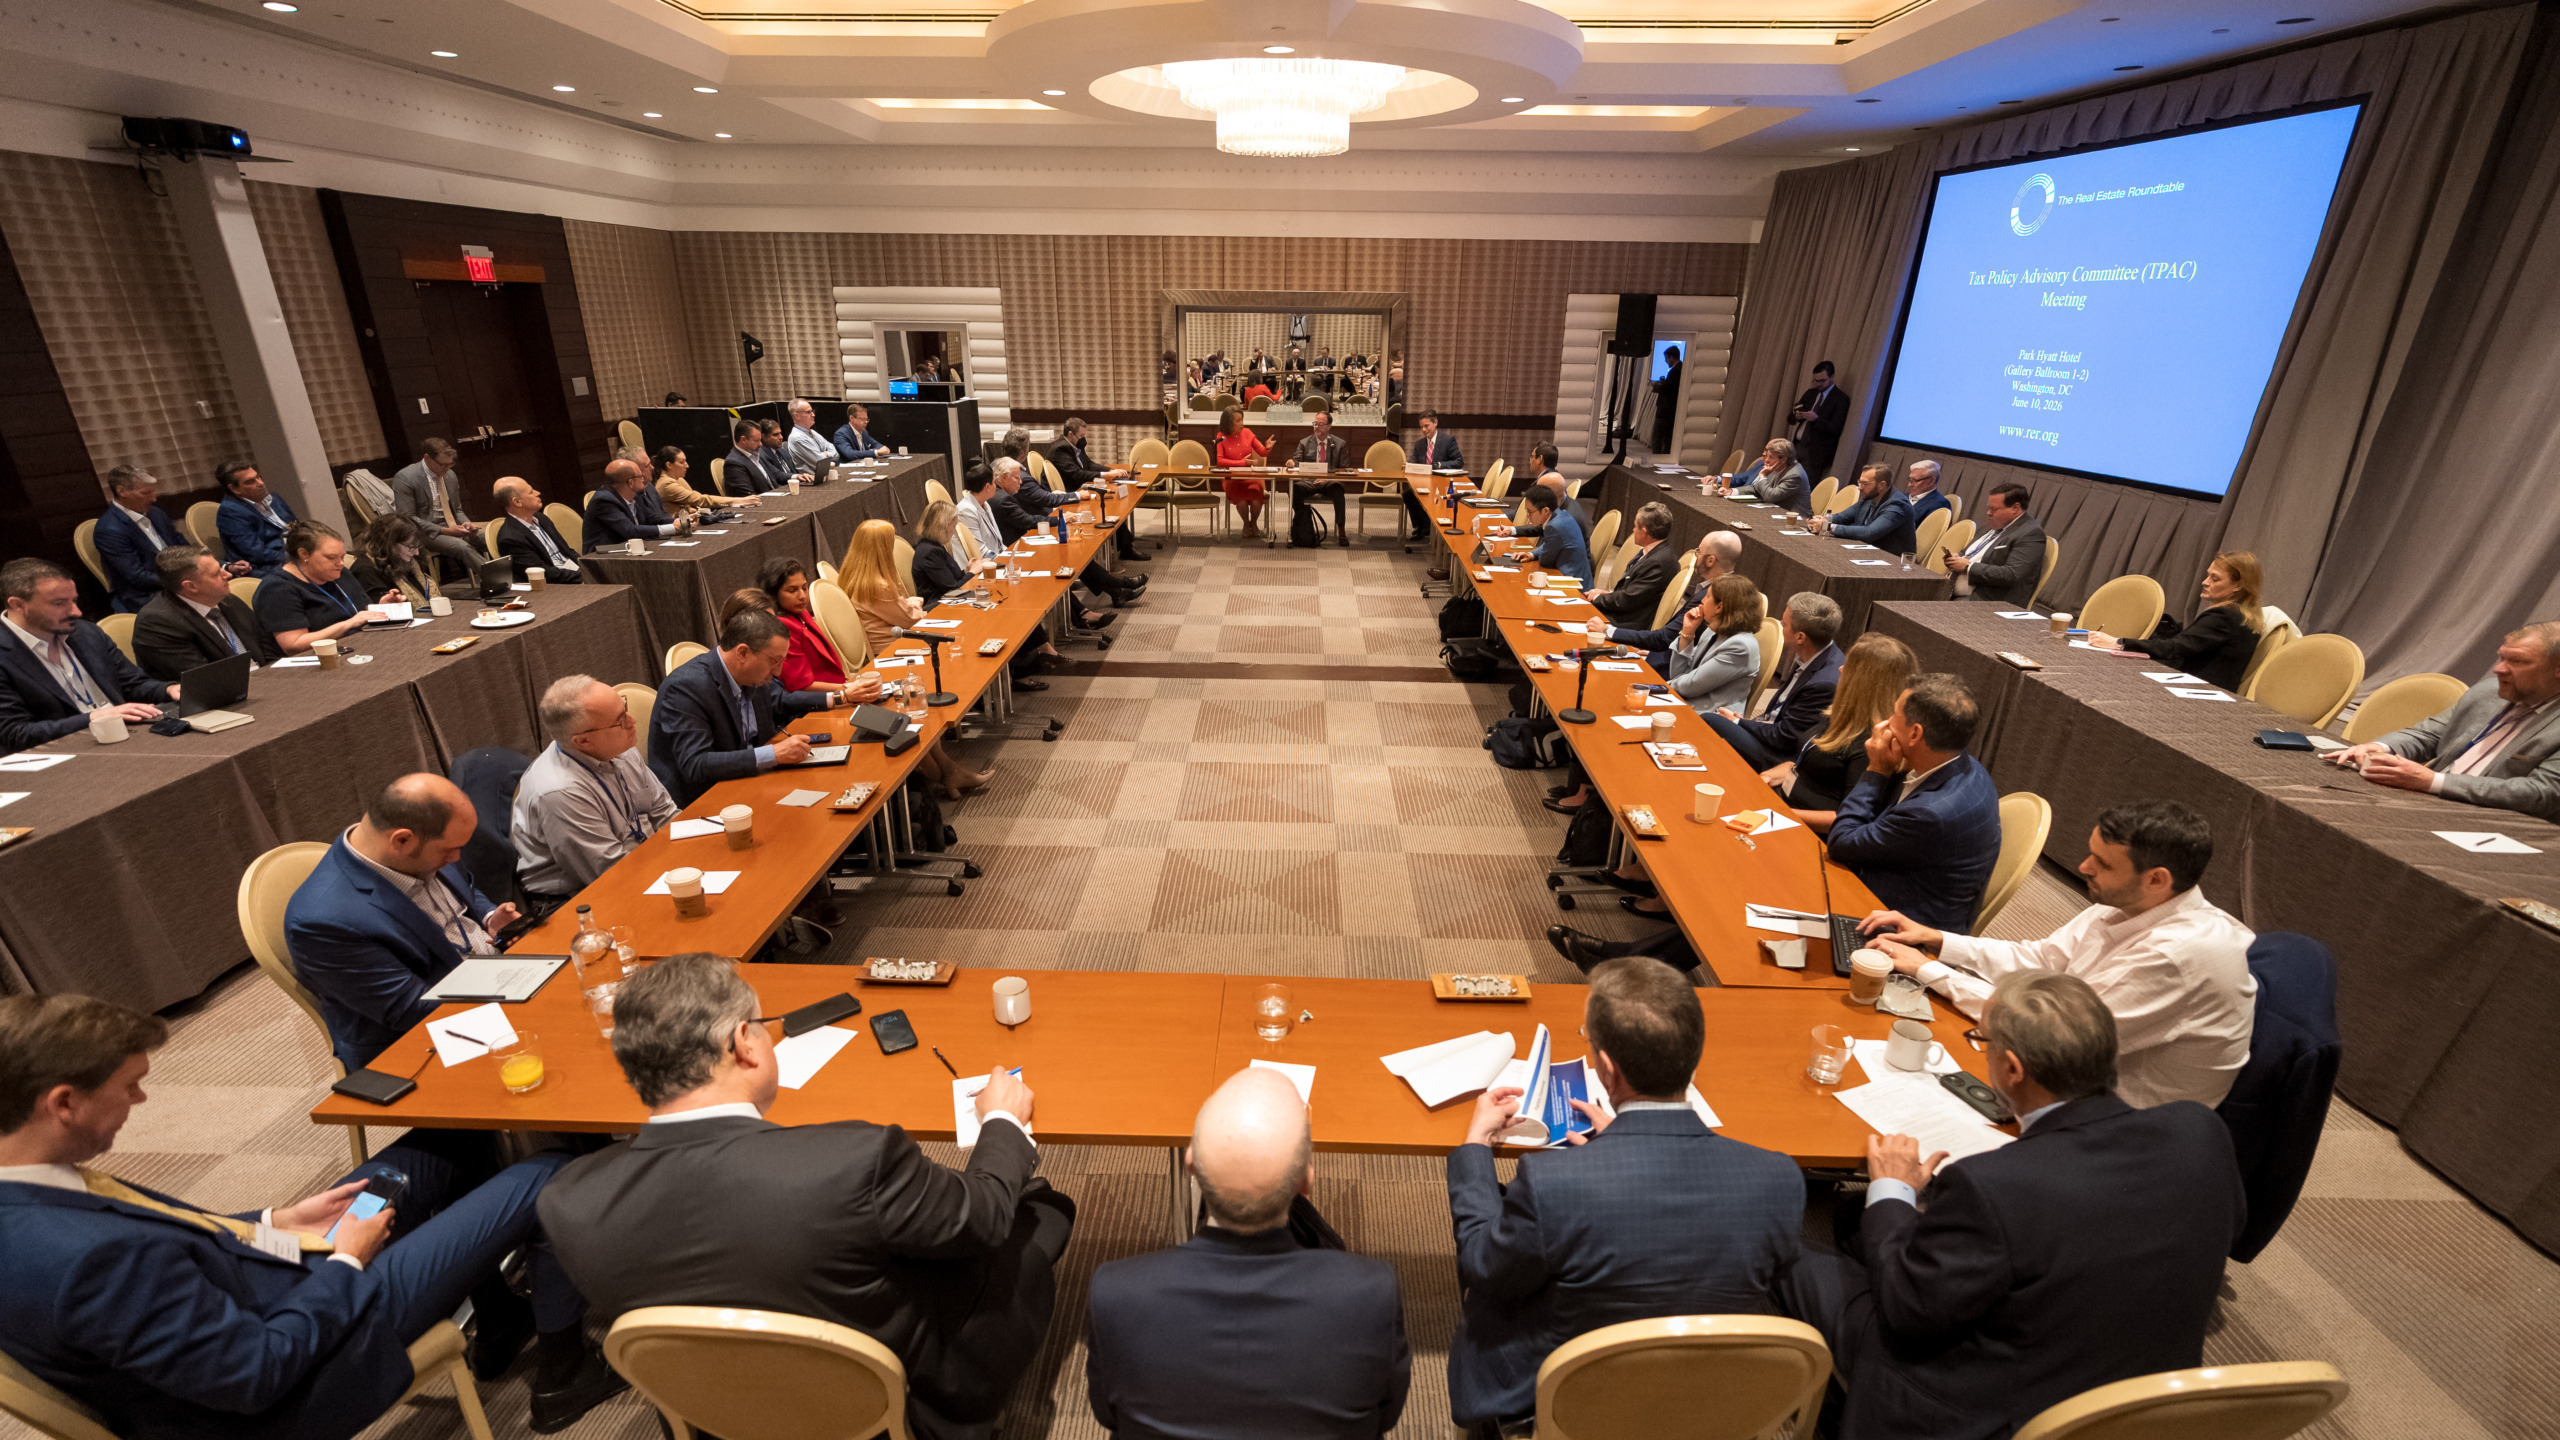
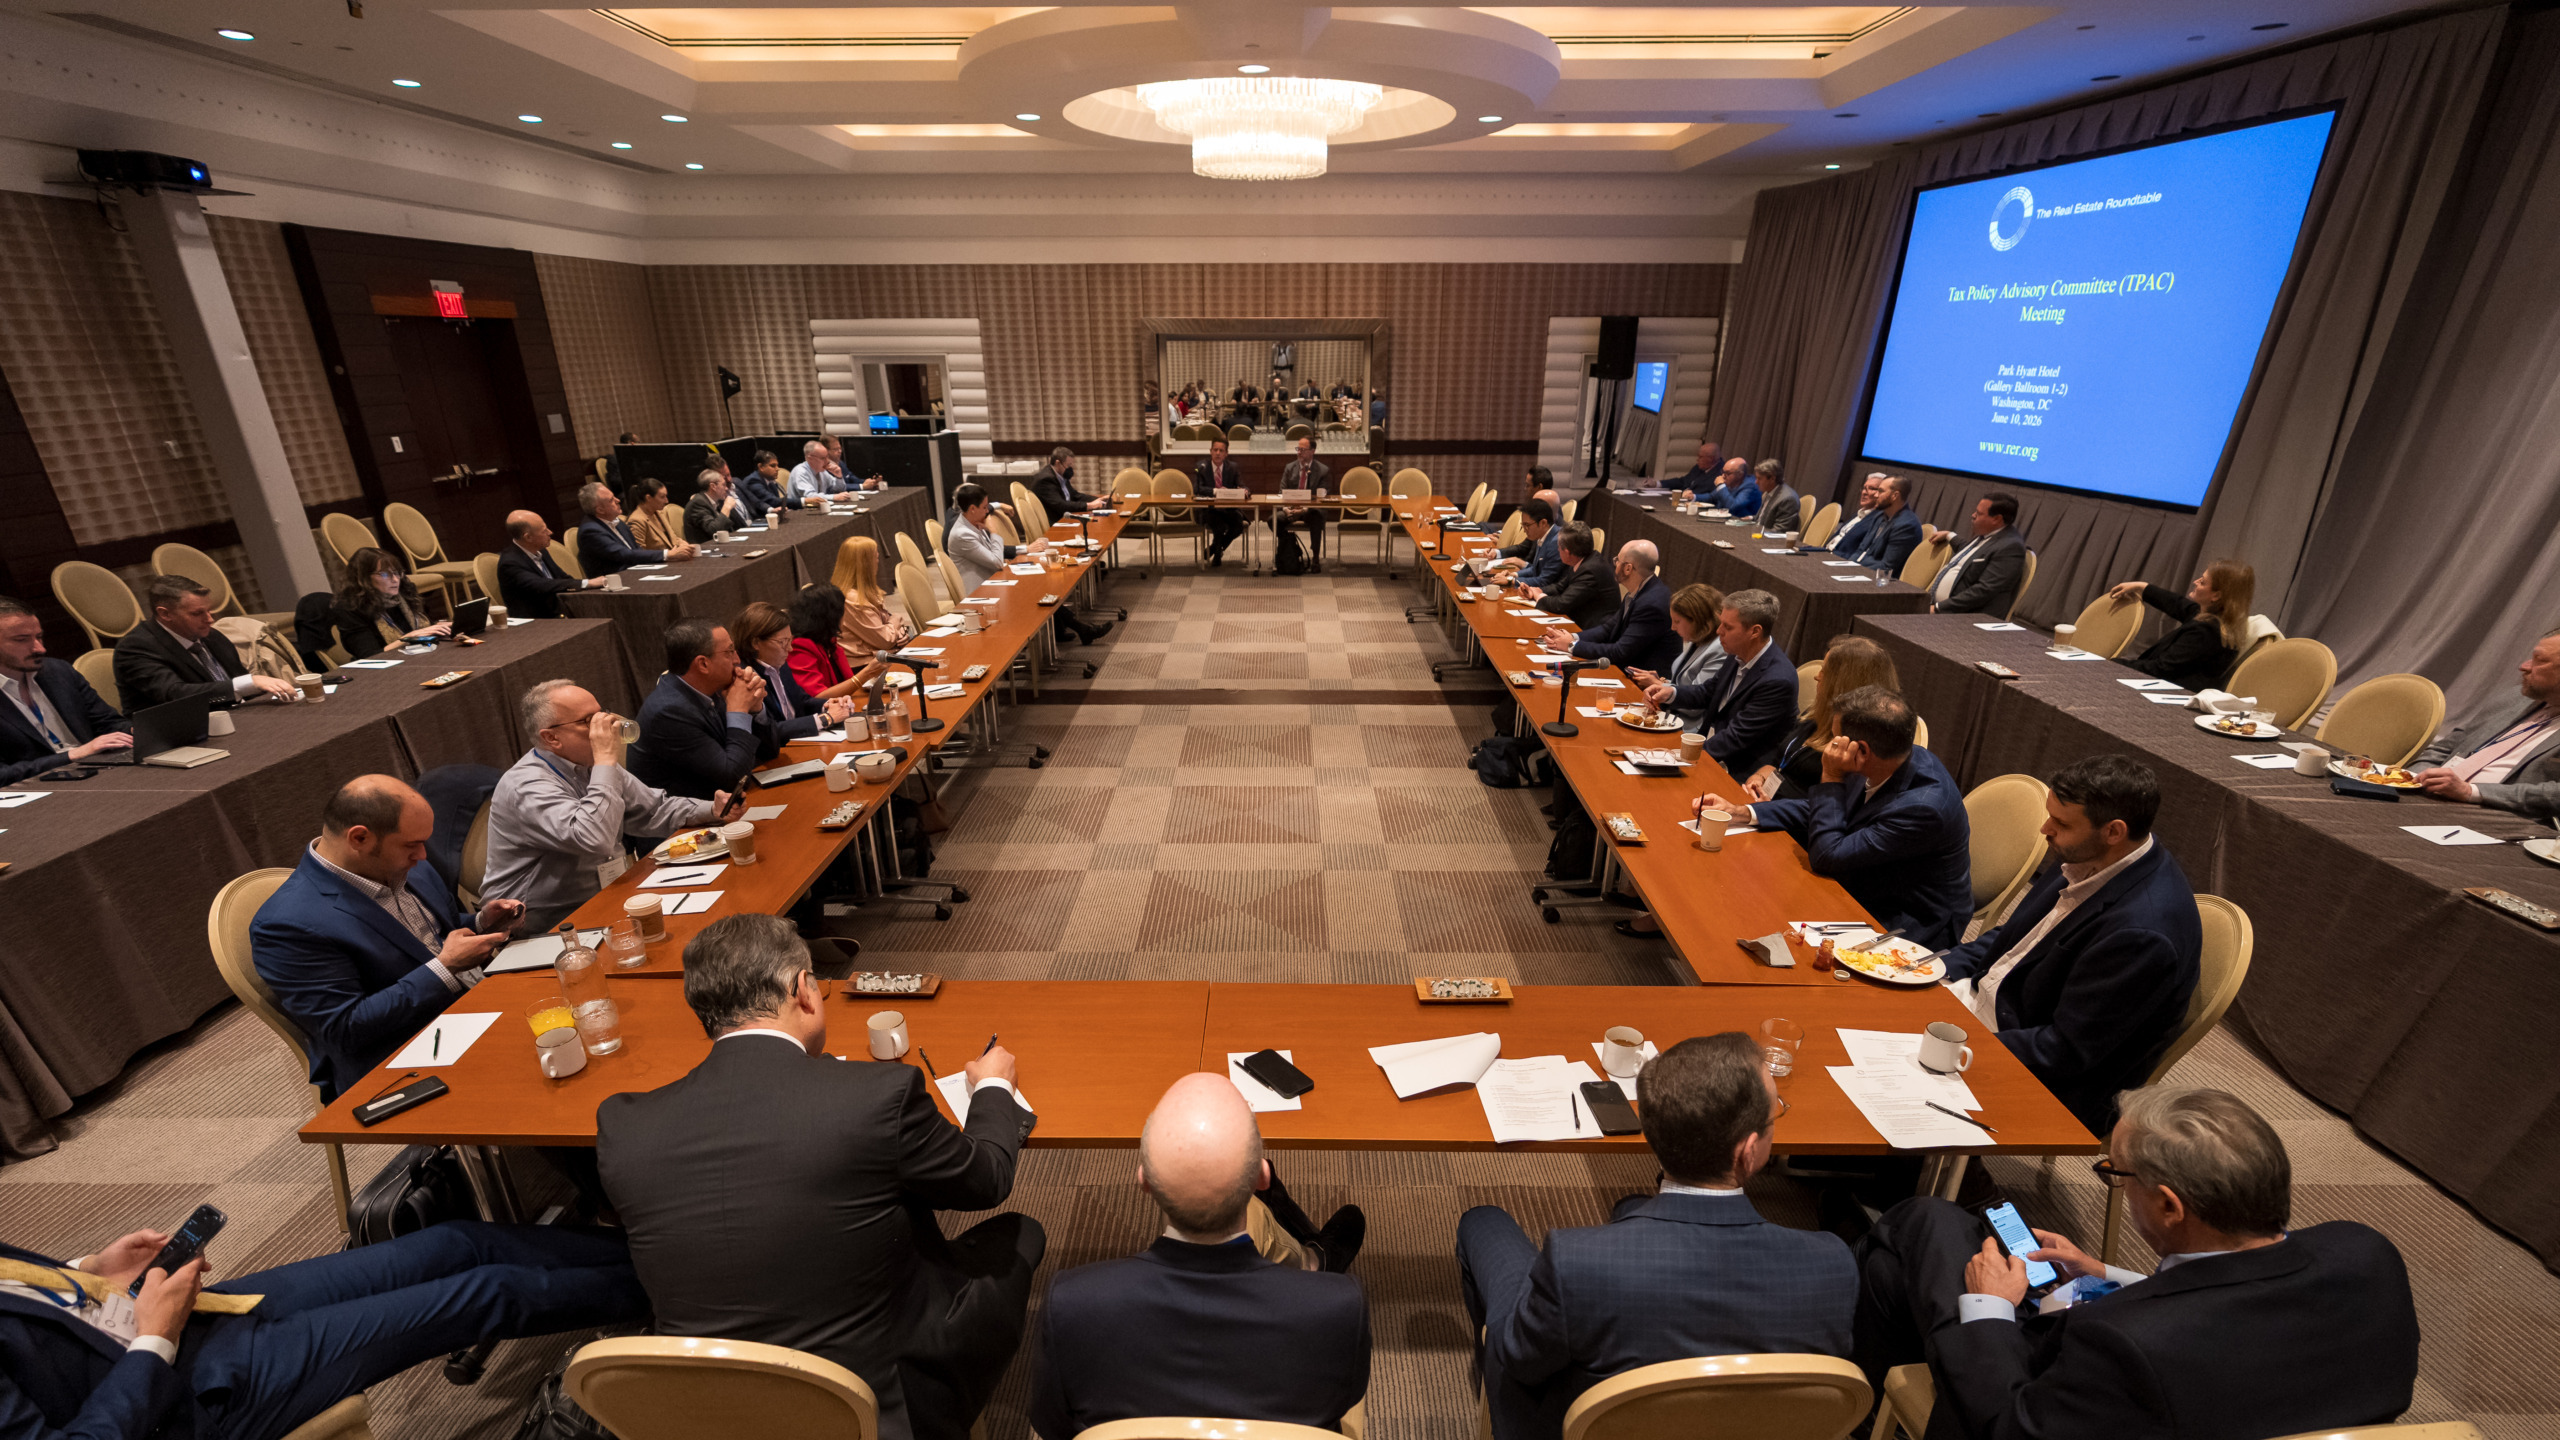
Section 892 regulations and other foreign investment tax policy issues will be discussed next week during RER’s Tax Policy Advisory Committee meeting on June 10.

Housing Supply Push Gains Momentum with New Tax and Regulatory Proposals

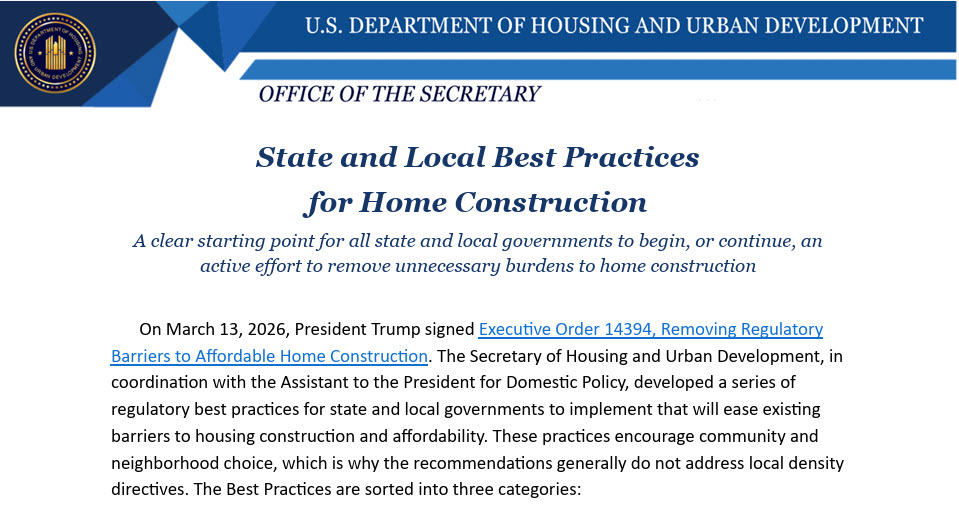
Federal policymakers offered new measures aimed at boosting housing supply this week, including bipartisan tax legislation to encourage rental construction and new Department of Housing and Urban Development (HUD) recommendations to reduce state and local regulatory barriers to homebuilding.

Rental Housing Investment Act

  • Reps. Claudia Tenney (R-NY), Linda Sánchez (D-CA), Darin LaHood (R-IL), and Jimmy Panetta (D-CA) introduced the Rental Housing Investment Act, bipartisan legislation to increase the supply of long-term rental housing by modernizing the tax code and incentivizing new construction. (Press Release, May 21)
  • The bill would allow builders to immediately deduct up to $150,000 per rental unit in construction costs for qualifying long-term residential rental housing developments, with an increased deduction of up to $250,000 per unit for qualifying affordable housing projects.
  • The legislation includes safeguards to ensure properties remain in long-term rental use and would apply to newly constructed housing placed in service after enactment.
  • “This bipartisan legislation takes a practical, market-driven approach to expanding housing supply, reducing development costs, and helping make housing more affordable for hardworking Americans,” said Rep. Tenney. (Press Release, May 21)
  • The bill’s bipartisan co-sponsors emphasized that high construction costs and limited rental supply are driving affordability challenges in communities across the country.
  •  A similar bill was previously introduced in the Senate by Sen. Lisa Blunt Rochester (D-DE). A Tax Policy Advisory Committee (TPAC) panel will discuss the bill and other housing tax incentives at The Real Estate Roundtable’s Annual Meeting in June.

HUD Regulatory Best Practices

  • HUD Secretary Scott Turner said the agency is encouraging state and local partners to review their regulations and policies to “lower the cost to build and enable more efficient housing supply growth.”
  • HUD noted that regulatory costs account for more than $100,000 of the final price of a new single-family home, while certain state and local green energy mandates can add up to $30,000 to construction costs. (HousingWire, May 20)

Housing Momentum

  • The housing debate was also front and center at an Axios event this week, where lawmakers highlighted growing bipartisan momentum around supply-side reforms, deregulation, zoning flexibility, and alternative construction methods. (Watch, May 20)
  • Rep. Ritchie Torres (D-NY) said “housing is having a moment in Washington, D.C.,” while Rep. Mike Flood (R-NE) emphasized that housing supply is also an economic development issue tied to workforce shortages and regional growth. (Axios, May 21)

These new legislative and regulatory actions reflect growing bipartisan attention to the core drivers of housing affordability: supply shortages, high construction costs, land-use barriers, lengthy permitting timelines, and financing constraints. RER will continue working with policymakers to advance supply-side reforms that encourage private capital, reduce construction barriers, and expand housing supply nationwide.

CRE Leaders Gather in Washington to Discuss Housing, Tax Policy, National Security, Energy, and More

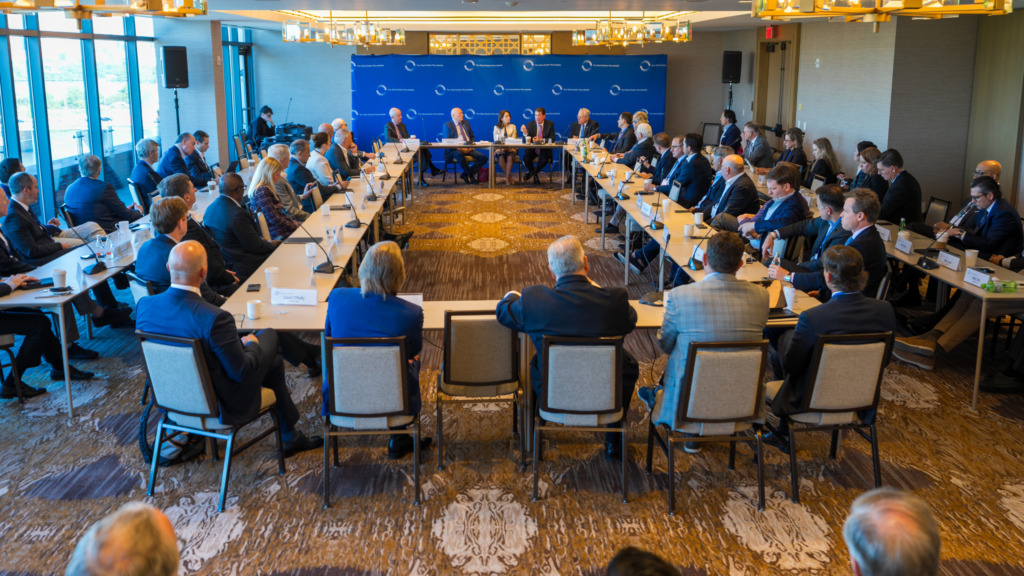
The Real Estate Roundtable’s (RER) Spring Roundtable Meeting brought commercial real estate leaders to Washington this week for bipartisan discussions on national security, housing, tax policy, energy, and economic growth. The meeting (Roundtable-level members only) came as Congress continued to debate housing legislation, implementation of the One Big Beautiful Bill Act, and broader questions of U.S. competitiveness and leadership. (RER’s Spring 2026 Policy Priorities and Executive Summary)

Across the agenda, speakers echoed similar concerns and priorities, including strengthening the workforce pipeline, expanding career and technical education, permitting reform, reducing regulatory burdens, and ensuring reliable energy infrastructure to support AI, data centers, and long-term economic growth.

Roundtable Leadership

  • RER Board Chair Kathleen McCarthy Baldwin (Former Global Co-Head of Blackstone Real Estate) opened the meeting by highlighting the value of convening industry leaders in Washington and recognizing the strong leadership across the organization, including the nominating committee’s work and the incoming board members’ efforts to position RER for the year ahead.
  • RER President and CEO Jeffrey DeBoer said that RER’s impact in Washington is built on active member involvement, strong committee engagement, and continued support for REALPAC. “Our voice is strongest when members are engaged, our committees are active, and we continue to invest in the advocacy efforts that help advance the industry’s priorities.”

Speakers & Policy Issues

  • Roundtable members engaged in policy discussions with the following guests:
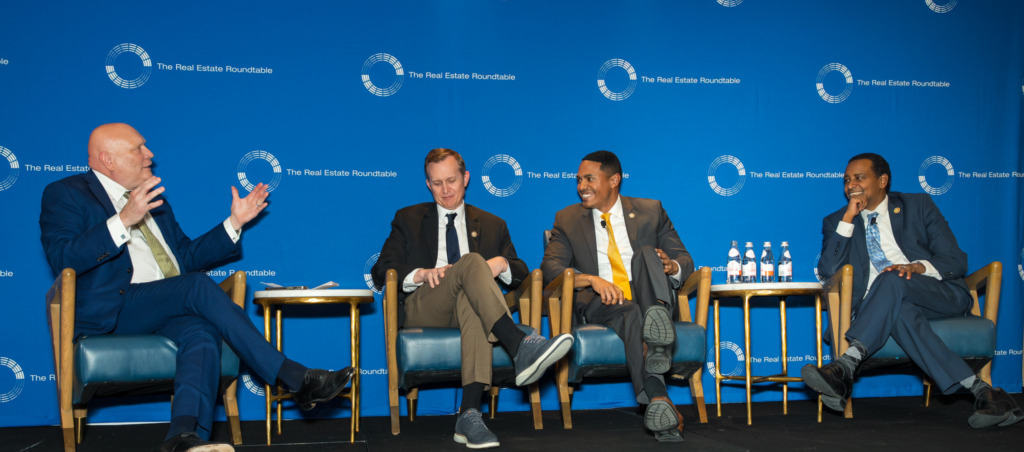
  • (R-L): Rep. Joe Neguse (D-CO) (House Assistant Democratic Leader; Committees: Natural Resources, Rules, and Judiciary), Rep. Ritchie Torres (D-NY) (Committees: Financial Services; Select Committee on the Strategic Competition Between the United States and the Chinese Communist Party), and Rep. George Whitesides (D-CA) (Committees: Science, Space and Technology; Armed Services) joined Monday evening’s dinner conversation on the political landscape, affordability, housing, immigration, and the policy choices shaping the run-up to the midterms. The panel also explored housing supply strategies, bipartisan problem-solving, and what voters are looking for from both parties on economic opportunity and cost-of-living concerns.
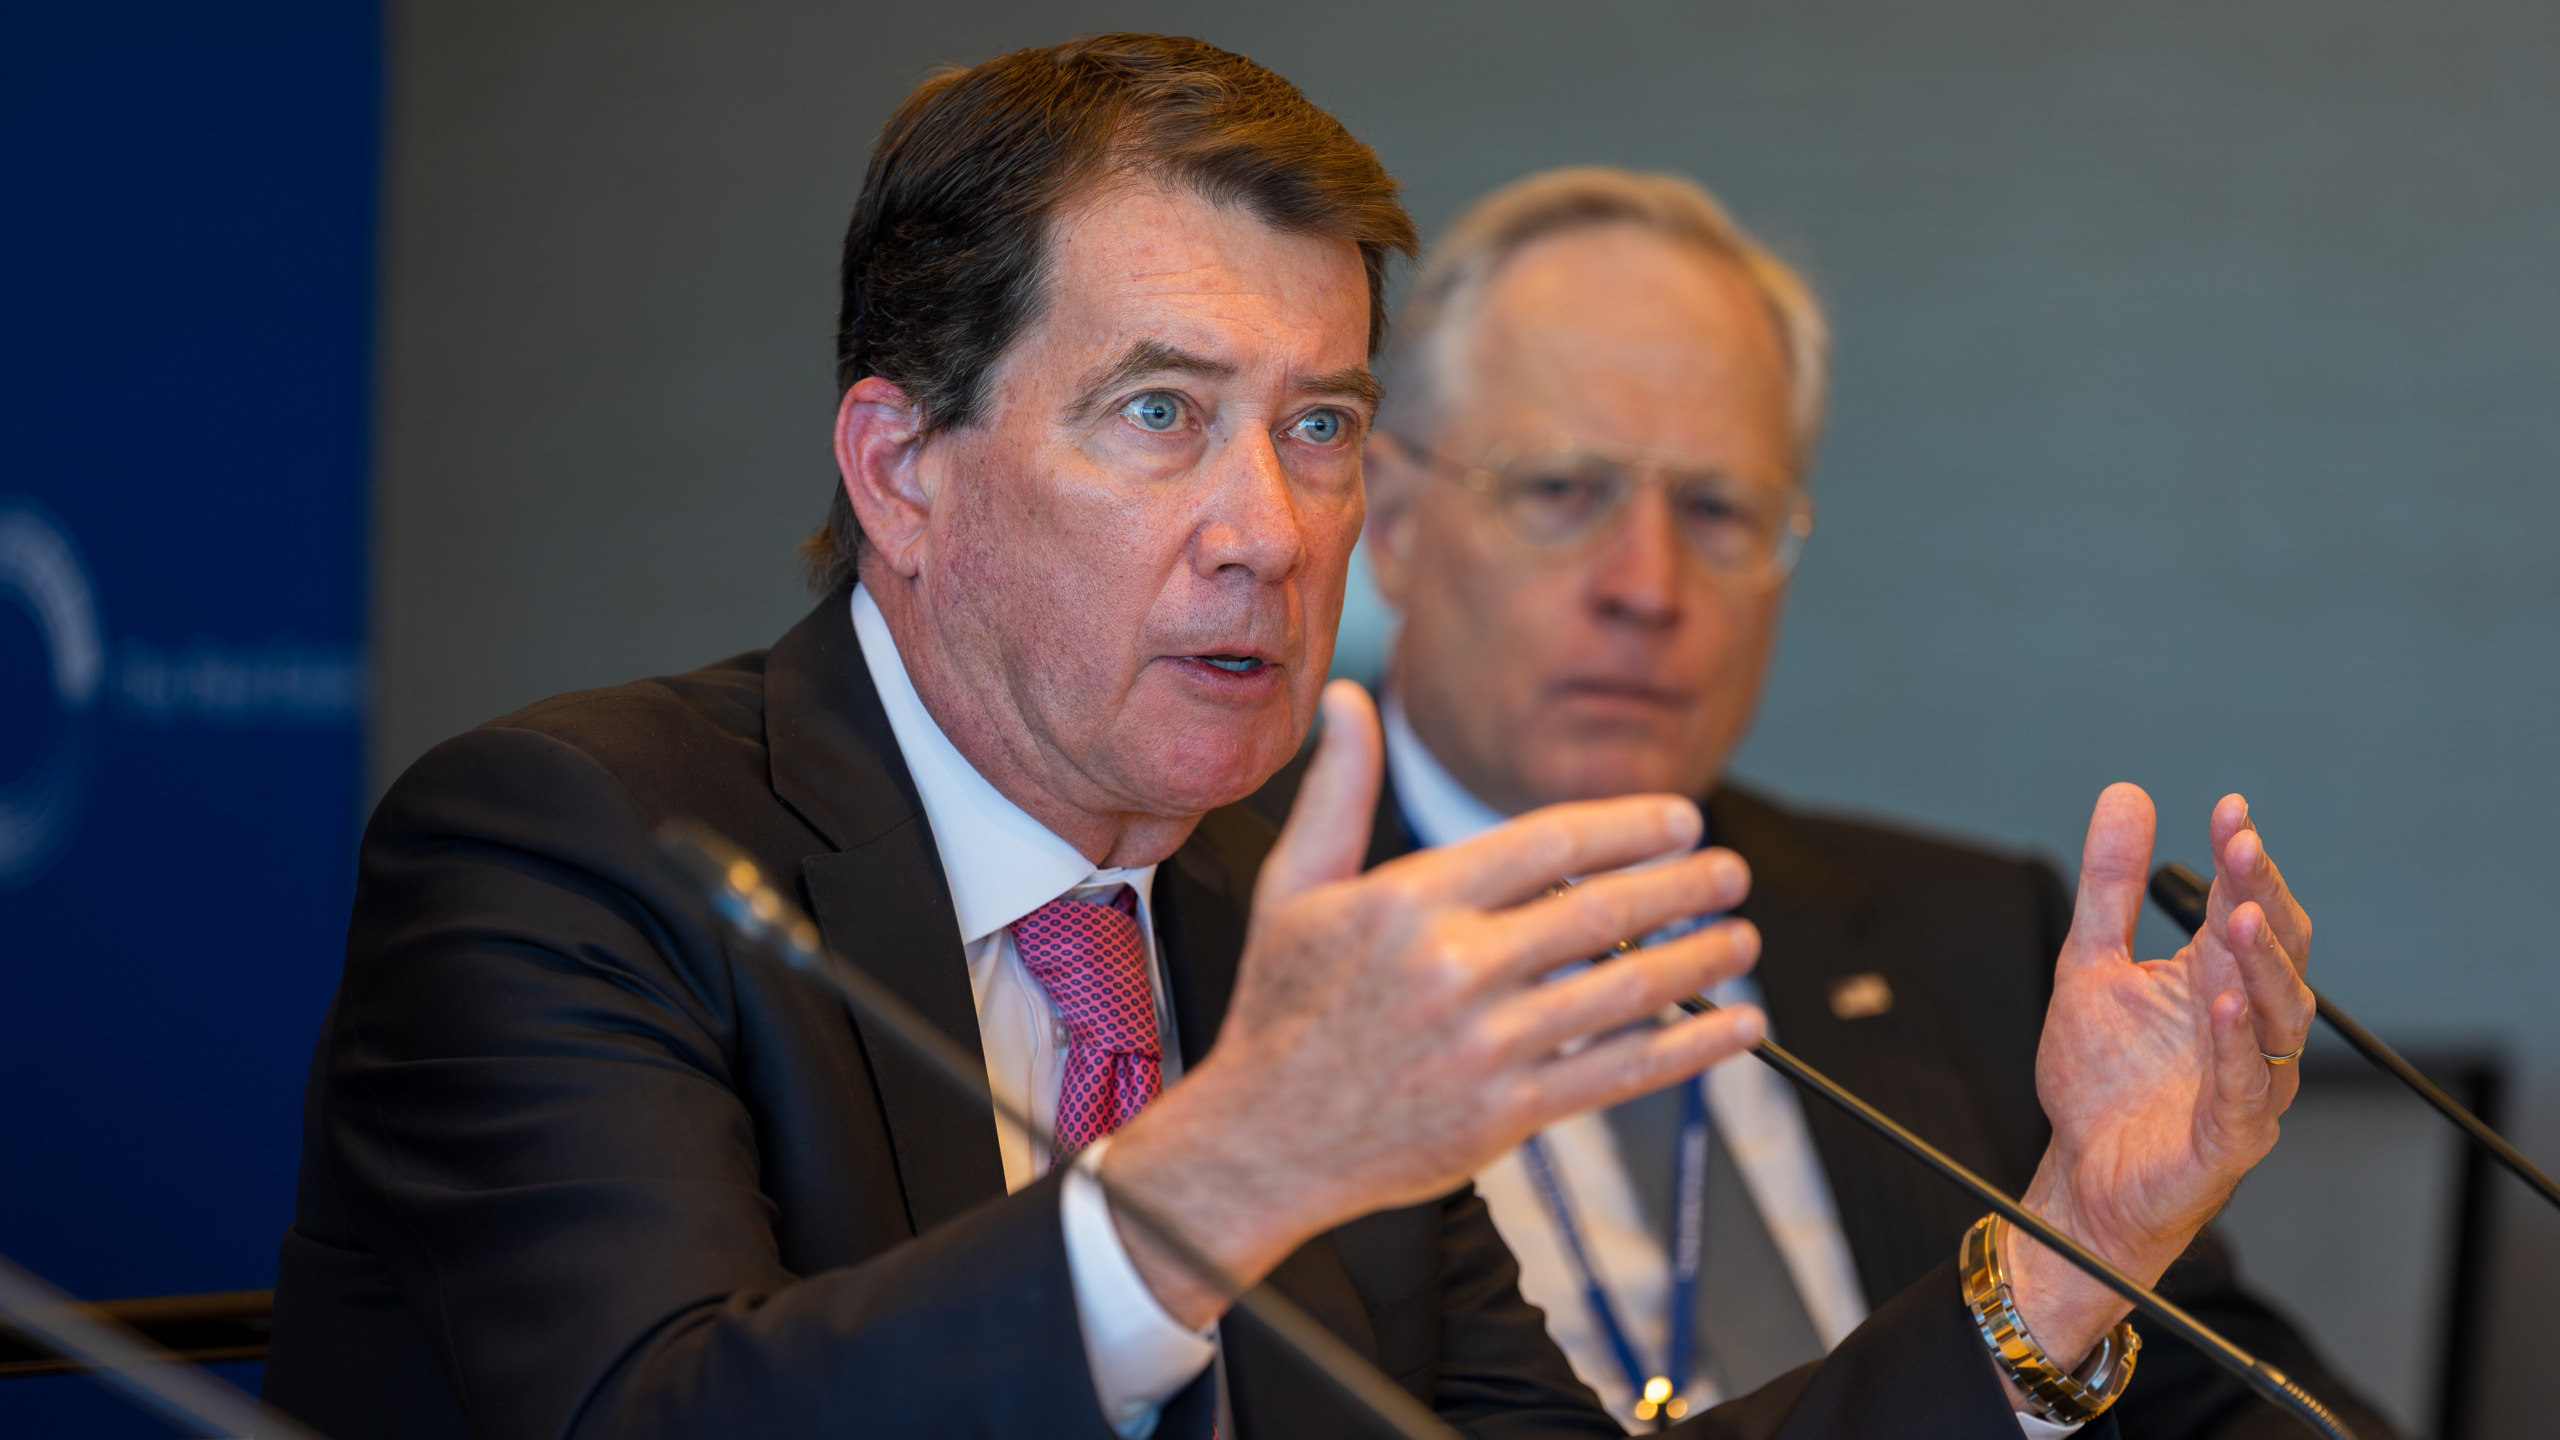
  • Sen. Bill Hagerty (R-TN) (Committees: Appropriations; Banking, Housing and Urban Affairs; and Foreign Relations) discussed national security, trade, China, workforce development, and the policy environment needed to strengthen American competitiveness. He also addressed housing supply and his recently introduced Freedom to Build Act, which is intended to incentivize deregulation, expand housing supply, and make homes more affordable by aligning existing federal incentives with communities that reduce barriers to building. (Roundtable Weekly, April 17)
  • Rep. Mike Flood (R-NE) (House Financial Services Committee) weighed in on the housing bills and the path toward bridging House and Senate priorities, with particular focus on concerns that Section 901 of the Senate-passed 21st Century ROAD to Housing Act could reduce housing supply and create new market uncertainty. He also addressed TRIA reauthorization, mortgage market stability, access to credit, and the need for practical housing solutions that expand supply.
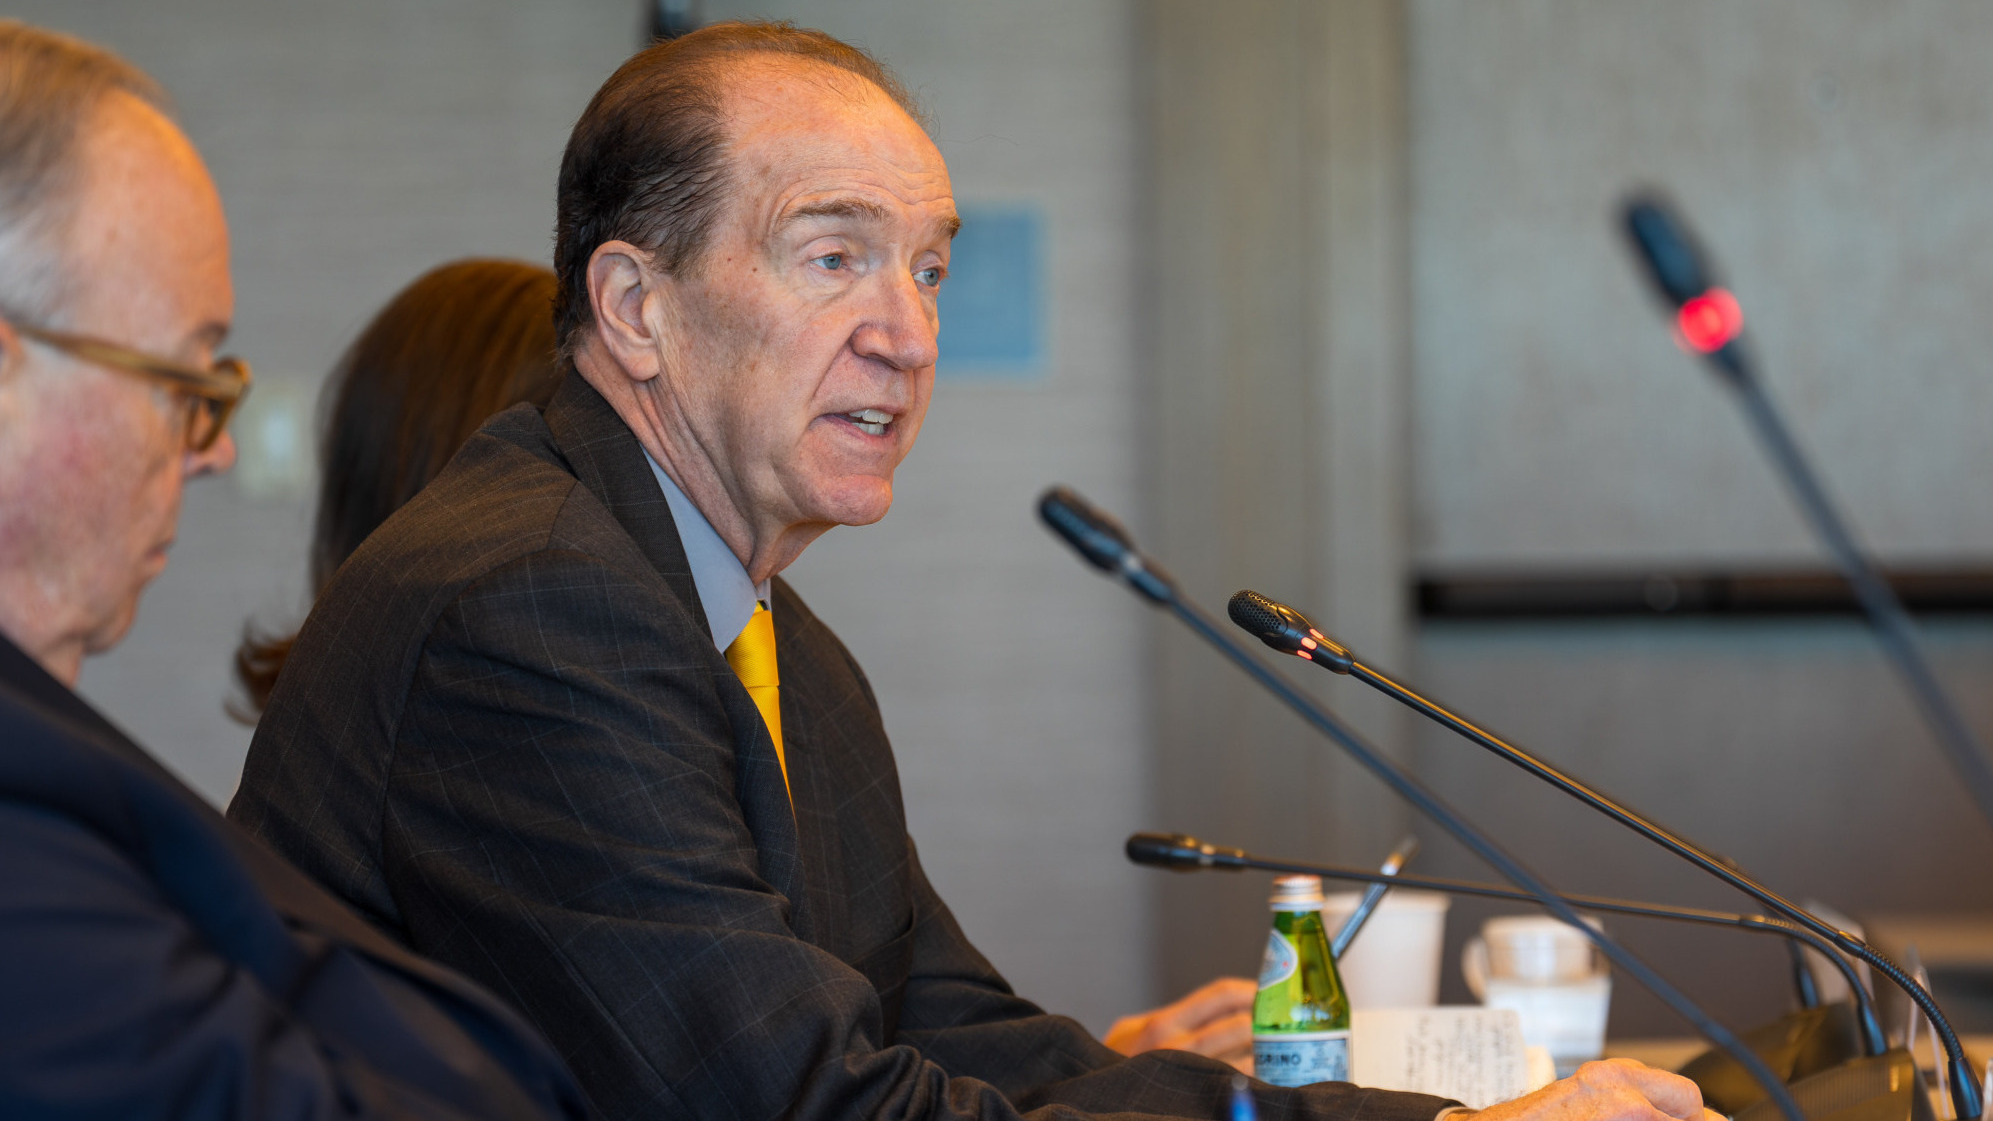
  • David Malpass (former President of the World Bank and former Under Secretary for International Affairs at the U.S. Department of the Treasury) offered his perspective on global economic ambiguity, energy policy, domestic production, labor shortages, and U.S. leadership. He also spoke about permitting reform, workforce development, interest rates, and the policy changes needed to support stronger long-term growth.
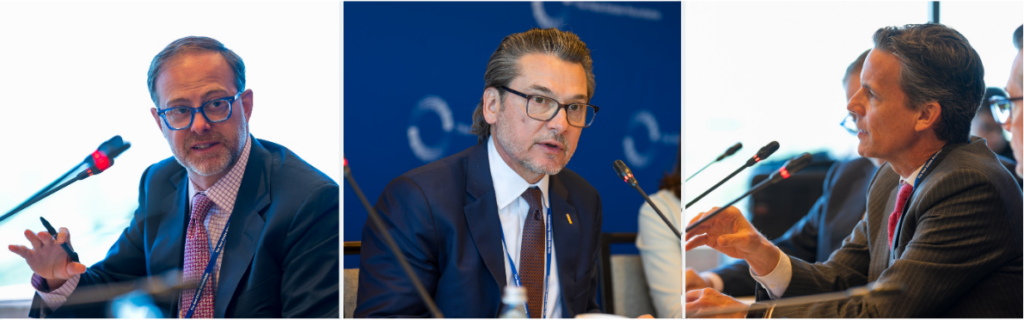
  • (L-R): Josh Parker (Chairman & CEO, Ancora Group Capital; Chair, RER’s Tax Policy Advisory Committee), Tony Chereso (President & CEO, The Inland Real Estate Group, LLC), and Ryan McCormick (Senior Vice President & Counsel, RER) led a tax policy panel on Treasury implementation of the One Big Beautiful Bill Act, Section 892 regulations, Opportunity Zones implementation, FIRPTA, foreign capital, and other issues affecting real estate investment and capital formation.

Next on RER’s meeting calendar is the all-member Annual Meeting on June 9-10, 2026, in Washington, D.C., which will include policy advisory committee sessions.

Roundtable Proposes Revenue Procedure to Address Opportunity Zone Transition

The Real Estate Roundtable (RER) on March 6 submitted proposed guidance to the U.S. Department of the Treasury and urged adoption of safe harbor rules to support continued investment in Opportunity Zones as the original OZ census tract designations phase out under the One Big Beautiful Bill Act (OBBBA). (Letter, Revenue Procedure, March 6)

Why It Matters

  • OZ incentives have helped drive private investment, job creation, and redevelopment in underserved communities since the enactment of the Tax Cuts and Jobs Act of 2017.
  • The approaching expiration of the original OZ designations creates uncertainty for long-term investments and development projects already in progress.
  • For example, it is unclear how opportunity funds and OZ businesses can continue satisfying location-based statutory and regulatory compliance tests after an original tract designation expires.
  • The uncertainty is having a chilling effect on OZ investment, discouraging new housing development and other productive real estate activity from moving forward.
  • RER’s proposal responds to a structural gap in current guidance and offers specific language that Treasury and the IRS could use to establish a safe harbor for qualifying investments, including guardrails to prevent abusive transactions while protecting capital formation. (Letter, Revenue Procedure, March 6)
  • Transitional administrative guidance would support continued housing construction, economic growth, and community revitalization as the program shifts to the permanent framework enacted under OBBBA.

RER Recommendations

  • To resolve this issue, the draft Revenue Procedure would establish a safe harbor under which an expired tract would be treated as a “Grandfathered QOZ” for specified compliance purposes unless a disqualifying event occurs.
  • Qualifying funds and businesses could continue meeting statutory requirements if projects began or satisfied written planning and capital deployment standards before expiration.
  • A clearly defined safe harbor would unlock frozen capital and, combined with the beneficial OZ reforms enacted in OBBBA, support construction of new and affordable housing and long-term economic development in disadvantaged communities.

RER Advocacy

  • In December 2025, RER separately urged Treasury and the IRS to provide expedited guidance warning that unresolved tax treatment questions could significantly reduce OZ investment and capital formation in 2026. (Roundtable Weekly, Dec. 19)
  • The Dec. 2025 letter emphasized that uncertainty surrounding expiring census tract designations could delay projects, discourage new fund formation, and undermine housing production and community development efforts. (Letter, Dec. 19)

The proposed guidance was developed by the RER’s Opportunity Zone Working Group. Principal drafters included KPMG’s Orla O’Connor and Michael McMahon, Deloitte’s Gary Hecimovich and Adam Wallwork, and Greenberg Traurig’s Sandy Presant. RER will continue encouraging Treasury and the IRS to issue timely guidance that sustains Opportunity Zone investment and keeps housing and economic development projects on track in underserved communities.