RER Calls for Coordinated Community Reinvestment Act (CRA) Rules; HUD Outlines Manufactured Housing Plan

This week, The Real Estate Roundtable (RER) urged all three federal banking agencies to adopt clear, harmonized Community Reinvestment Act (CRA) rules to reduce compliance costs and support capital investment in affordable housing and underserved communities. (Letter, Oct. 13)

CRA Rulemaking

  • In the Oct. 13 letter, RER called for the Office of the Comptroller of the Currency (OCC), Federal Deposit Insurance Corporation (FDIC), and Federal Reserve to adopt clear, harmonized CRA rules. The OCC and FDIC have jointly proposed changes without parallel Federal Reserve action. (Letter, Oct. 13)
  • Enacted in 1977 to combat redlining, the CRA encourages banks to meet the credit needs of their entire communities, including low- and moderate-income neighborhoods.
  • RER supports continued efforts to modernize CRA rules but cautioned that finalizing changes without parallel Federal Reserve action could replace the historically uniform interagency framework with materially different regulatory regimes. (Letter, Oct. 13)

Why It Matters

  • Affordable housing and community development projects frequently rely on multiple banks providing construction loans, permanent financing, tax credit investments, and other forms of capital.
  • A divided CRA regime could make identical loans receive different treatment, weaken investment incentives for some lenders, complicate mergers and syndicated transactions, and make the flow of capital into underserved markets less predictable.
  • RER also raised concerns about a potential 1.25% of Tier 1 capital benchmark for wholesale and limited-purpose banks, which would need to be met within their assessment areas before qualifying activities elsewhere could receive CRA consideration. (Letter, Oct. 13)
  • The benchmark could concentrate investment in heavily banked markets while disadvantaging strong projects in smaller metropolitan and rural communities.
  • RER recommended uniform rules, coordinated implementation and consistent treatment of multibank transactions. (Letter, Oct. 13)

RER Advocacy

  • RER urged the agencies to coordinate transition schedules, examinations and interpretive guidance, and apply consistent standards to multibank housing and community development transactions. (Letter, Oct. 13)
  • Existing requirements should remain in place until all three agencies jointly propose and finalize a harmonized framework.

Manufactured Housing
  • The plan calls for updated energy efficiency standards, design and installation rules for chassis-free homes, and a performance-based code for larger factory-built residential structures. HUD will also develop guidance and resources addressing zoning, appraisal, lending, and insurance. (HUD, Oct. 7)
  • The ROAD Act eliminates the requirement that manufactured homes be built and remain on a permanent steel transport frame—a relic of the mobile home era. The change could reduce construction costs by $5,000–$10,000 per home, by some estimates, allow more flexible designs, and reduce local zoning barriers. (RER’s Housing Fact Sheet, July 2026)

RER will continue working with banking agencies and stakeholders to advance rules that support community investment and provide certainty for real estate financing.
Fed Signals Another Rate Hike as Regulators Advance Capital Reforms

Minutes from the Federal Reserve’s Sept. 15-16 meeting, released Oct. 7, indicated that most policymakers believe another interest rate increase would likely be appropriate by year-end. The minutes follow recent remarks by Federal Reserve Vice Chair for Supervision Michelle Bowman, who said she expects regulators to finalize the revised Basel III capital framework by year-end, while pointing to early results from recent leverage ratio reforms. (Federal Reserve, Sept. 18 | Federal Reserve, Oct. 1 | American Banker, Oct. 1 | Federal Reserve, Oct. 7)

Fed Outlook

  • Most Federal Open Market Committee (FOMC) participants indicated that another rate increase would likely be appropriate before year-end, following the Fed’s unanimous decision in September to raise its benchmark rate by 25 basis points, bringing the target range to 3.75%-4%. Officials cited persistent inflation, resilient economic activity, and diminished labor market risks in support of additional tightening. (Federal Reserve, Oct. 7 | Wall Street Journal, Oct. 7 | Associated Press, Oct. 7)
  • Credit and Housing. Several participants pointed to easier bank lending standards, while a few noted that elevated mortgage rates continued to weigh on housing activity. Treasury yields rose roughly 35 basis points across the 2- to 10-year range between meetings, while residential mortgage rates increased slightly more than the 10-year Treasury yield. (Federal Reserve, Oct. 7)
  • Regulatory Reform. Bowman said the Fed’s recalibration of the enhanced supplementary leverage ratio (eSLR) has expanded large banks’ balance sheet capacity and improved Treasury market intermediation. Dealers’ Treasury positions increased from approximately $600 billion before the changes to more than $700 billion by the end of April, demonstrating how adjustments to capital requirements can support market liquidity. (Federal Reserve, Oct. 1 | Bloomberg Law, Oct. 1)
  • Capital Reforms. Regulators are expected to finalize revised risk-based capital requirements under Basel III and accompanying changes to the global systemically important bank (G-SIB) surcharge before year-end. The proposals, released in March, would reduce aggregate capital requirements for the largest U.S. banks by an estimated 2.4% and revise the treatment of mortgages and mortgage servicing assets to better align capital requirements with risk. (Roundtable Weekly, March 20 | Bloomberg, March 19 | Federal Reserve, Sept. 18)

Why It Matters

  • Another potential rate increase, combined with elevated Treasury yields, could extend borrowing and refinancing pressures for commercial real estate (CRE) owners. Nearly $983 billion in CRE mortgages are estimated to mature in 2027, increasing the importance of accessible financing as borrowers seek to refinance existing debt. (Federal Reserve, Oct. 7 | RER Policy Priorities, Capital & Credit)
  • At the same time, appropriately calibrated capital requirements could strengthen banks’ capacity and incentives to provide CRE financing. While the eSLR changes primarily address Treasury market intermediation, the revised Basel III framework could ease certain regulatory constraints on lending and support market liquidity as borrowers navigate elevated financing costs. (Roundtable Weekly, March 20 | Federal Reserve, Sept. 18 | Federal Reserve, Oct. 1)

Roundtable Advocacy

  • The Real Estate Roundtable has consistently advocated for appropriately calibrated, risk-based bank capital requirements that maintain financial stability without unnecessarily limiting CRE lending. RER opposed the original 2023 Basel III proposal, warning that higher capital requirements could reduce credit availability, increase financing costs, and constrain investment in commercial and multifamily real estate. (Roundtable Weekly, March 20)
  • In a June 18 coalition letter, RER and other national real estate organizations urged regulators to preserve the revised proposal’s improvements while making targeted changes to avoid unnecessarily constraining CRE financing. Recommendations included more risk-sensitive treatment of CRE and multifamily loans, mortgage servicing, and securitizations, along with changes to prevent disproportionate capital charges on common financing arrangements such as mezzanine loans and preferred equity. (Coalition Letter, June 18)

RER will continue engaging with federal regulators and industry partners as the Basel III reforms move toward finalization, advocating for capital requirements that preserve credit availability, support housing and commercial real estate investment, and maintain a stable and liquid CRE finance market.

FinCEN Permanently Ends Beneficial Ownership Reporting for U.S. Companies

The Treasury Department’s Financial Crimes Enforcement Network (FinCEN) issued a final rule on Aug. 11 permanently removing beneficial ownership information (BOI) reporting requirements for U.S. companies and U.S. persons under the Corporate Transparency Act (CTA). The rule finalizes the narrower framework adopted in March 2025 and provides long-term relief for millions of U.S. businesses.

State of Play

  • All entities created in the United States are exempt from BOI reporting, including the limited liability companies and partnerships commonly used to own and operate commercial real estate. The rule took effect Aug. 14, 2026. (Final Rule | Treasury Press Release, Aug. 11)
  • FinCEN will delete information previously reported by U.S. persons who are now exempt from the requirements. (FinCEN, Aug. 11)
  • Foreign entities that qualify as reporting companies remain subject to the CTA, but they are required to report BOI only for foreign individuals. (FinCEN, Aug. 11)

Why It Matters for CRE

  • Treasury originally estimated the CTA would reach roughly 32 million existing entities, plus millions of newly formed entities each year. Under the narrowed framework, only about 11,600 foreign firms are expected to report annually. (Roundtable Weekly, March 28, 2025)
  • The regime posed particular challenges for real estate, where individual assets are frequently held in separate LLCs or partnerships. The final rule eliminates the need to identify individuals with indirect ownership interests or substantial control across these structures and file updates following changes in ownership or management. (Roundtable Weekly, June 7, 2024)

RER Advocacy

  • Most recently, RER and a coalition urged Treasury to delay the CTA’s reporting requirements weeks before the department announced it would suspend enforcement against domestic companies. (Coalition Letter, Jan. 4, 2025)

RER’s Real Estate Capital Policy Advisory Committee (RECPAC) will continue to track developments related to beneficial ownership reporting requirements.

Senate Passes Seven-Year TRIA Reauthorization

The Senate passed the bipartisan Terrorism Risk Insurance Program Reauthorization Act of 2026 (S. 4395) by unanimous consent, advancing a seven-year extension of the federal terrorism risk insurance program through Dec. 31, 2034.

State of Play

  • Sponsored by Sen. Dave McCormick (R-PA), with Sens. Tina Smith (D-MN), Thom Tillis (R-NC), and Ruben Gallego (D-AZ), S. 4395 provides a clean seven-year reauthorization through 2034, maintaining the program’s existing structure.
  • Both chambers have now approved seven-year extensions, but the Senate bill differs from the House-passed measure, which would increase the minimum loss threshold for an event to qualify as an act of terrorism under the program from $5 million to $10 million beginning in 2029 and establish a 90-day timeframe for Treasury certification determinations. (Roundtable Weekly, July 17) 

What’s Next

  • Because the House and Senate passed different versions of the reauthorization, identical legislation must still clear both chambers before it can be sent to the president for his signature.
  • Options include the House adopting the Senate bill, a conference to resolve differences, or attaching final language to a must-pass package by year’s end.

RER Advocacy

  • RER and coalition partners urged lawmakers to advance S. 4395, warning that policyholders are already negotiating coverage extending beyond TRIA’s 2027 expiration and emphasizing the importance of maintaining certainty for insurers and policyholders. (Roundtable Weekly, Sept. 18)
  • RER and its industry partners will continue urging Congress to send a long-term TRIA reauthorization to the president’s desk before the end of the year, providing certainty ahead of the program’s 2027 expiration.

Senate Banking Committee Advances TRIA Reauthorization

The Senate Banking Committee voted 24–0 on Sept. 17 to advance the bipartisan Terrorism Risk Insurance Program Reauthorization Act of 2026 (S. 4395), moving a long-term extension of the federal terrorism insurance program toward full Senate consideration. (Coalition Letter, Sept. 16 | Insurance Journal, Sept. 17)

State of Play

  • As introduced, the Senate legislation would extend the program for seven years through Dec. 31, 2034, maintaining its existing framework. TRIA is currently scheduled to expire on Dec. 31, 2027. (Senate Banking Statement, Sept. 17 | Bill Text)
  • On June 29, the House voted 373–15 to pass its bipartisan reauthorization bill (H.R. 7128), also extending the program through 2034. (Roundtable Weekly, July 17)
  • The House measure would also raise the minimum loss threshold for terrorism certification from $5 million to $10 million beginning in 2029 and establish a 90-day timeframe for Treasury certification decisions. (Roundtable Weekly, July 17)

Roundtable Advocacy

  • Ahead of the vote, RER, the Coalition to Insure Against Terrorism (CIAT), and a broad group of trade associations submitted a letter to Senate Banking Committee Chairman Tim Scott (R-SC) and Ranking Member Elizabeth Warren (D-Mass.), urging them to advance S. 4395 to the full Senate. (Coalition Letter, Sept. 16
  • The coalition warned that policyholders are already negotiating coverage extending beyond TRIA’s 2027 expiration. Past reauthorization delays have prompted insurers to include conditional exclusions that eliminate terrorism coverage if the program lapses.
  • RER, which co-chairs CIAT, has consistently urged Congress to act early. The latest letter builds on the coalition’s July call to include long-term TRIA reauthorization in must-pass legislation this year. (Coalition Letter, July 29)

Why It Matters

  • Following the Sept. 11 attacks, terrorism insurance became largely unavailable, disrupting commercial real estate financing and construction. TRIA’s public-private partnership helps maintain access to coverage needed to finance projects, protect jobs, and support investment. (Roundtable Weekly, May 1)
  • Since 2002, the program has served as a public-private risk-sharing mechanism that helps maintain the availability of terrorism insurance at virtually no cost to taxpayers.

The bill now heads to the full Senate for consideration. RER and its coalition partners will continue urging Senate passage and enactment of a long-term TRIA extension this year.

RER, CIAT Urge Senate to Advance Long-Term TRIA Reauthorization

The Real Estate Roundtable (RER), the Coalition to Insure Against Terrorism (CIAT), and a broad group of business organizations urged congressional leaders this week to include a seven-year extension of the Terrorism Risk Insurance Program (TRIA) in any must-pass legislation considered this year. (Letter, July 29)

Coalition Letter

  • The coalition called for action on the bipartisan Senate Terrorism Risk Insurance Program Reauthorization Act of 2026 (S. 4395), warning that waiting until the final year of TRIA’s authorization would create uncertainty for insurers and policyholders that are already negotiating policies extending beyond the program’s Dec. 31, 2027 expiration. (Roundtable Weekly, July 17)
  • The letter emphasized that maintaining the current framework is critical to ensuring insurers of all sizes remain in the market, and sufficient capacity is available for businesses seeking terrorism coverage. (Letter, July 29)
  • TRIA remains a critical public-private partnership that helps ensure terrorism insurance coverage remains available and affordable for commercial businesses, educational institutions, nonprofit organizations, and other policyholders. (Letter, July 29)

State of Play

  • Last month, the House voted 373-15 to pass the bipartisan TRIA Program Reauthorization Act of 2026 (H.R. 7128), which would extend the program through 2034. The bill would also raise the minimum loss threshold from $5 million to $10 million beginning in 2029 and establish a 90-day timeframe for Treasury certification decisions. (PoliticoPro, June 29 | Legis1, July 1)
  • The Senate’s seven-year reauthorization bill (S. 4395) has garnered more than 30 bipartisan cosponsors. Both the House and Senate proposals maintain TRIA’s existing structure, which the coalition emphasized is critical to keeping insurers of all sizes in the market and preserving sufficient coverage capacity. (Roundtable Weekly, May 1)

Why It Matters

  • TRIA has provided stability to terrorism insurance markets since its enactment following the Sept. 11 attacks, helping businesses, property owners, lenders, and insurers manage risks that the private market cannot fully absorb. (Roundtable Weekly, Sept. 19)
  • Since 2002, the program has served as a public-private risk-sharing mechanism that helps maintain the availability of terrorism insurance at virtually no cost to taxpayers.
  • A 2026 Treasury Department report warned that allowing TRIA to expire—or even lapse temporarily—could disrupt insurance markets, affect unrelated lines of coverage, and delay projects in critical sectors. (Letter, July 29)
  • The letter also cited federal assessments of evolving threats to critical infrastructure, including real estate.

Roundtable Advocacy

  • RER, which co-chairs CIAT, has consistently urged Congress to act well ahead of TRIA’s Dec. 31, 2027 expiration.

RER and its industry partners will continue to urge Senate leaders to include TRIA on any must-pass legislation this year.

House Passes Main Street Capital Access Act with Bipartisan Support

The House passed the Main Street Capital Access Act (H.R. 6955) on Tuesday by a bipartisan vote of 270-155-1, with 56 Democrats joining 213 Republicans and one independent in support. The Real Estate Roundtable (RER) endorsed the legislation earlier this year as an important step toward right-sizing bank regulation and expanding access to capital. (HFSC Press Release, July 21)

State of Play

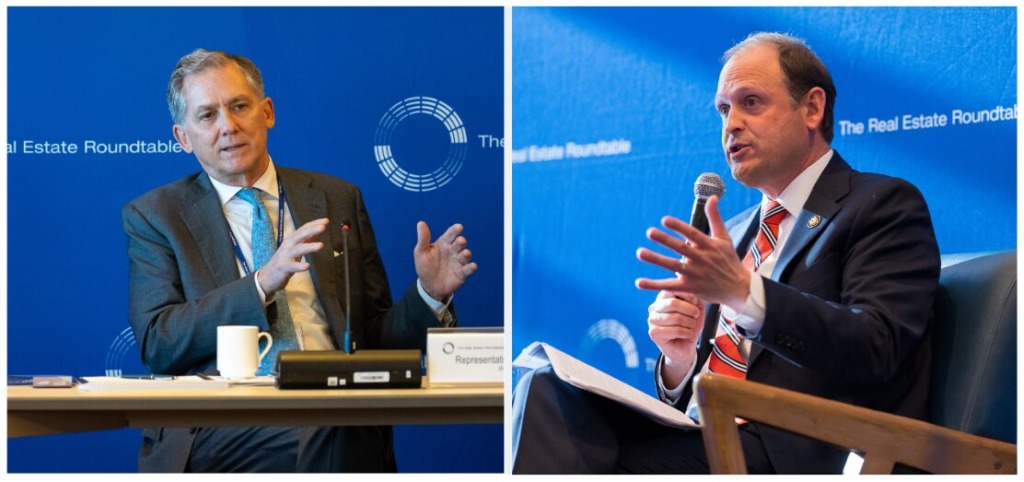
  • Sponsored by House Financial Services Committee Chairman French Hill (R-AR) and Financial Institutions Subcommittee Chairman Andy Barr (R-KY), the package is designed to encourage new bank formation, tailor regulation for community and regional banks, and remove barriers to local lending. (Bill text | Section-by-Section | One-Pager)
  • “Expanding access to capital means entrepreneurs can invest, businesses can grow, and families can build wealth,” Hill said following the vote, adding that he looks forward to the Senate considering the legislation. (Legis1, July 22)
  • Community and regional banks are important sources of financing for housing and commercial real estate, particularly in smaller and underserved markets.
  • RER has consistently advocated for appropriately tailored financial regulation that maintains bank safety and soundness while supporting liquidity, capital formation, housing production, and economic growth. (Roundtable Weekly, Jan. 16)

RER Advocacy

  • RER submitted a letter of support for the Main Street Capital Access Act in January, emphasizing the critical role community and regional banks play in financing commercial and residential real estate. (Roundtable Weekly, Jan. 16)
  • “The Main Street Capital Access Act will help revitalize communities across the nation by encouraging local bank formation and enhancing credit capacity,” said RER President and CEO Jeffrey D. DeBoer. “By easing outdated regulatory burdens for community banks, it will help unlock more capital for housing and small businesses.”

21st Century ROAD to Housing Act Implementation

  • RER is forming a member working group to engage with Treasury, HUD, and other federal agencies as they develop implementing regulations for the recently enacted 21st Century ROAD to Housing Act, with a particular focus on Section 1001 and its implications for single-family rental and build-to-rent investment.
  • Members interested in participating in the working group should contact RER’s SVP, Clifton E. (Chip) Rodgers, Jr. (crodgers@rer.org).

The legislation now moves to the Senate for consideration. RER will continue working with policymakers to advance measures that strengthen credit capacity and expand access to capital for housing, commercial real estate, and communities across the country.

Coalition Urges Regulators to Refine Basel III Proposal for CRE Lending

The Real Estate Roundtable (RER) and a coalition of national real estate organizations urged federal banking regulators this week to make targeted refinements to the revised Basel III Endgame proposal to better calibrate capital rules for commercial and residential real estate lending. (Letter, June 18)

Why It Matters

  • In March, the Federal Reserve, Federal Deposit Insurance Corporation (FDIC), and Office of the Comptroller of the Currency (OCC) unveiled a substantially revised Basel III Endgame proposal, replacing the 2023 framework that drew broad industry opposition. (Reuters, June 18)
  • The coalition commended regulators for improving the revised proposal, particularly by tailoring capital requirements more closely to risk across different assets and activities, but warned that additional changes are needed to avoid unnecessarily constraining CRE credit. (Letter, June 18)
  • Commercial and multifamily real estate is a roughly $20 trillion sector supported by more than $6.4 trillion in debt, with approximately $3 trillion in CRE loans maturing over the next five years.
  • For commercial real estate, the reset could ease regulatory pressure that threatened to constrain credit for real estate lending, mortgage activity, and other capital-intensive transactions. (Roundtable Weekly, March 20)
  • “The Proposals significantly improve on the 2023 proposal,” the coalition wrote, adding that targeted refinements would “better calibrate CRE capital requirements without unduly constraining the financial system or burdening housing providers.”

Policy Priorities

  • The coalition urged regulators to better align capital treatment with actual risk for CRE exposures, multifamily loans, securitizations, warehouse facilities, mortgage servicing rights, Low-Income Housing Tax Credit (LIHTC) investments, and Fannie Mae Delegated Underwriting and Servicing (DUS) exposures.
  • The letter also recommends avoiding structural penalties for common CRE financing arrangements, including mezzanine loans, preferred equity, B-notes, junior participations, and loans involving special-purpose entities. (Letter, June 18)
  • Capital rules that are not properly calibrated could increase borrowing costs, reduce bank lending capacity, and constrain credit for housing development and other income-producing real estate.

Roundtable Advocacy

  • The Real Estate Roundtable (RER) has consistently opposed the original Basel III proposal, citing its potential negative impact on available credit capacity for commercial real estate transactions, market liquidity, and economic growth. (Roundtable Weekly, Nov. 2023 | Jan. 2024 |  Mar. 2024 | Dec. 2025 | Feb. 2026 |  March 20, 2026)
  • Earlier this year, federal regulators released a substantially revised Basel III proposal that reduced capital requirements for the largest U.S. banks by 2.4% overall and lowered certain risk weights for mortgages and mortgage servicing assets. (Financial Times, June 17)
  • In its June letter, the coalition urged regulators to preserve the proposal’s improvements while making targeted refinements to avoid unnecessarily constraining CRE lending, affordable housing investment, or broader economic growth. (Letter, June 18)

RER will continue working with policymakers, regulators, and real estate industry partners to support capital rules that are appropriately calibrated, risk-based, and aligned with the need for a stable and liquid commercial real estate finance market.

Roundtable Backs DOL Proposal to Expand 401(k) Access to Alternative Assets

The Real Estate Roundtable (RER) submitted comments this week supporting the Department of Labor’s (DOL) proposed rule to clarify fiduciary standards for including alternative assets, such as real estate, in 401(k) retirement plans. In the letter, RER affirmed that the proposal would expand investment choice, improve diversification, and provide retirement savers with access to asset classes that have long been available to institutional investors. (Letter, June 1)

Why It Matters

  • RER’s comments respond to the DOL’s proposed rule implementing the August 2025 Executive Order, “Democratizing Access to Alternative Assets for 401(k) Investors,” which seeks to clarify fiduciary obligations when plan sponsors offer investment options that include alternative assets such as private equity, real estate, private credit, and infrastructure investments. (Letter, June 1)
  • The DOL proposal would also establish a process-based safe harbor under the Employee Retirement Income Security Act (ERISA), helping reduce regulatory uncertainty and litigation risk that have discouraged many employers from offering alternative investment options in defined-contribution retirement plans. (DOL Press Release, March 30)
  • More than 90 million Americans participate in 401(k)-style retirement plans but generally lack access to the same alternative investment opportunities available to defined-benefit plan portfolios, such as pensions and other institutional investors. (Letter, June 1)

RER Advocacy

  • RER’s letter argues that the DOL’s rule appropriately clarifies that ERISA gives fiduciaries discretion and flexibility to determine when alternative investments are suitable for plan participants. (Letter, June 1)
  • RER also emphasized that defined-benefit pension plans that maintain allocations to private equity and other alternative assets have historically outperformed many defined-contribution plans, giving institutional investors access to diversification and return opportunities generally unavailable to retail retirement savers. (Letter, June 1)
  • The proposal would help level the playing field between 401(k) investors and defined-benefit plans by allowing fiduciaries to consider a broader range of investment options when they determine such investments are appropriate for plan participants. (Letter, June 1)
  • “RER believes that this rulemaking represents an important step toward restoring the principle that retirement savers, not regulators, determine how they invest,” the letter stated.

State of Play

  • The proposal has drawn mixed reactions on Capitol Hill.
  • Senior congressional Democrats, including House Education and Workforce Committee Ranking Member Bobby Scott (D-VA), Senate HELP Committee Ranking Member Bernie Sanders (I-VT), and Senate Banking Committee Ranking Member Elizabeth Warren (D-MA), urged DOL this week to withdraw the proposal. (Letter, June 1)
  • The Democratic lawmakers argued that expanding access to private equity, cryptocurrency, and other alternative investments could expose retirement savers to “risky, complex, and expensive” investments and weaken fiduciary protections for retired savers. (Letter, June 1)
  • Meanwhile, a group of 21 Senate Republicans, including Senate Banking Chair Tim Scott (R-SC) and HELP Chair Bill Cassidy (R-LA), submitted a letter backing the proposal, arguing that it “has the potential to materially improve long-term retirement outcomes for American workers.” (PoliticoPRO, June 2)
  • A separate group of 25 House Republicans, including House Budget Chair Jodey Arrington (R-TX) and House Financial Services Subcommittee on Financial Institutions and Monetary Policy Chair Andy Barr (R-KY), also submitted a letter advocating for the policy. (PoliticoPRO, June 2)
  • In a March press release, then-U.S. Secretary of Labor Lori Chavez-DeRemer explained, “This proposed rule will show how plans can consider products that better reflect the investment landscape as it exists today. This greater diversity will drive innovation and result in a major win for American workers, retirees, and their families.” (DOL Press Release, March 30)
  • SEC Chairman Paul S. Atkins echoed former Secretary Chavez-DeRemer’s remarks, saying, “Americans’ ability to participate more fully in innovation and economic growth through well-diversified long-term investments is a vitally important priority for effective retirement planning.” (DOL Press Release, March 30)

What’s Next

  • The public comment period closed on June 1, and DOL is reviewing stakeholder feedback before deciding whether to finalize the rule later this year.

RER will continue to engage with policymakers on retirement investment policy and support reforms that expand capital formation, balance investment flexibility with appropriate oversight, and provide American workers with broader opportunities to build long-term wealth.

Roundtable Urges FTC, DOJ to Preserve HSR Real Estate Transaction Exemptions

The Real Estate Roundtable (RER) submitted comments this week urging the Federal Trade Commission (FTC) and Department of Justice (DOJ) to preserve longstanding real estate exemptions under the Hart-Scott-Rodino Act (HSR), warning that eliminating them would impose substantial costs and delays on lawful real estate transactions without delivering any clear antitrust benefit. (Letter, May 26)

Why It Matters

  • The comments respond to an FTC and DOJ request for public input on potential changes to the Premerger Notification and Report Form, including whether the agencies should revisit exemptions for certain real estate transactions. (Letter, May 26)
  • The real estate exemptions were adopted in 1996 because these transactions were considered unlikely to violate antitrust laws.
  • The exemptions cover several categories of real property acquisitions, including office, residential, retail, hotel, warehouse, agricultural, recreational, and other rental real estate assets.
  • At the time, the FTC said the exemptions would “remove an unnecessary burden from business” and allow the FTC and DOJ to better focus resources on transactions more likely to cause competitive harm.
  • The letter emphasized that the same policy and economic rationale remain sound today, given that real estate markets are local, highly fragmented, and shaped by property type, geography, zoning rules, neighborhood characteristics, and other market-specific factors.

Market Impact

  • Eliminating the exemptions would create new regulatory burdens for transactions that have long been considered unlikely to raise antitrust concerns. (Letter, May 26)
  • HSR filing fees can reach up to $2.46 million, in addition to legal, financial, and operational costs associated with preparing filings.
  • Potential new filing requirements could slow transactions, disrupt market liquidity, and create additional uncertainty across real estate markets at a time when capital formation remains critical to investment and development.
  • The agencies have not provided evidence that circumstances have changed materially since the exemptions were adopted, or that exempted real estate transactions have had a negative effect on competition.
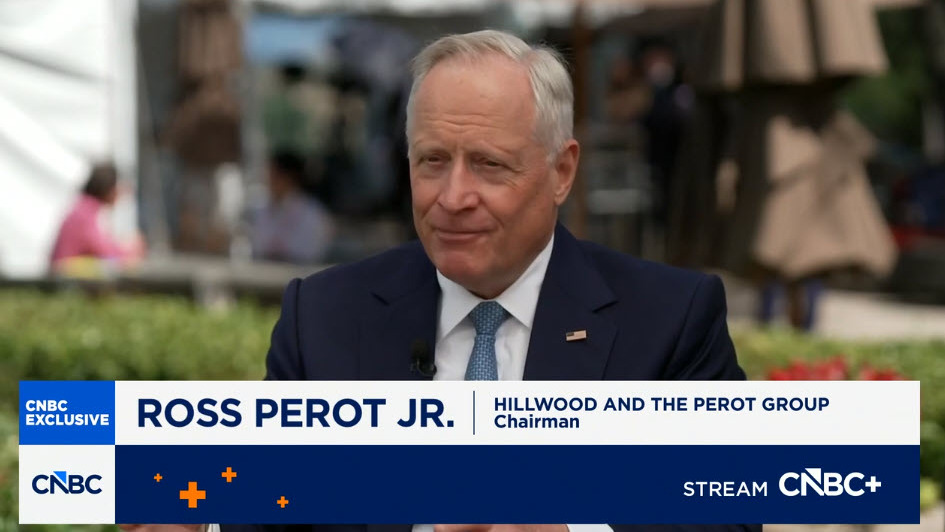
  • RER board member Ross Perot Jr. (Chairman, The Perot Companies and Hillwood), discussed the real estate market and how developers are keeping up with demand this week on CNBC’s The Exchange. He emphasized the need for pro-growth tax and regulatory policies to support investment, job creation, AI infrastructure, and responsible development in communities across the country. (CNBC, May 29)

Housing Supply

  • The letter warned that removing the exemptions would not be a targeted way to address concerns about single-family housing acquisitions by large institutional investors. (Letter, May 26)
  • The vast majority of transactions covered by the exemptions do not involve single-family housing, and many single-family housing transactions would not meet the $133.9 million HSR filing threshold even if the exemptions were removed.
  • Large institutional investors collectively own less than 1% of single-family homes nationally and make less than 3% of annual home purchases in the U.S. (Roundtable Weekly, Jan. 9)
  • The costs and delays of HSR reporting would fall disproportionately on smaller buyers such as homebuilders and residential developers acquiring land for new housing projects, potentially increasing development costs and slowing efforts to address the nation’s housing shortage.

Preserving the exemptions would help avoid unnecessary regulatory burdens, support market liquidity, and protect the capital needed to expand housing supply and strengthen the broader economy.