RER advocates for tax policies that promote capital formation, reward risk-taking, and bolster investment. RER strongly supported the tax provisions in the One Big Beautiful Bill Act (OB3 Act) signed into law in July 2025. The OB3 Act tax reforms, once fully implemented, will spur investment in our nation’s housing supply, strengthen urban and rural communities, and grow the broader economy to the benefit of all Americans. Going forward, RER is focused on the following objectives.
RER's Fall 2026 Policy Priorities
Summary
Entity choice rules allow U.S. businesses to choose how they will be taxed, and real estate generally is owned and operated through “pass-through” entities—partnerships, LLCs, S corporations, and REITs. These pass-through entities allow income and often deductions to pass through to individual investors. Pass-through entities give investors greater flexibility in how they allocate the risks and rewards of these capital-intensive and relatively illiquid businesses. Our partnership tax rules facilitate the ability of differently situated parties, such as entrepreneurs and capital providers, to come together for productive activities that create jobs and strengthen communities.
Despite the economic benefits of our pass-through tax regime, pass-through rules are often challenged by certain lawmakers who claim that the rules: (1) disproportionately benefit upper-income taxpayers and large corporations, (2) give taxpayers too much ability to pick and choose how and when to pay tax, and (3) are too complicated for the IRS to enforce.
Several proposals in recent years would significantly restrict pass-through taxation or raise tax rates on pass-through income, effectively raising the tax burden on real estate investment. These proposals include:
Support for proposals to raise revenue on the backs of pass-through businesses may grow in the months and years ahead as pressure increases for Congress to address rising debt and deficits. For example, Senate Finance Ranking Democrat Ron Wyden (D-OR) has claimed that his PARTNERSHIPS Act (S. 2095) to reform partnership tax rules would raise over $725 billion.
Key Takeaways
Our pass-through regime is a competitive strength of the U.S. tax system. Most countries rely on inflexible corporate regimes that provide little ability for an entrepreneur to tailor the capital and ownership structure to meet the needs of the business and its investors.
Pass-through businesses account for roughly 95% of all U.S. businesses, and these businesses are the drivers of job growth, innovation, and productive risk-taking.
Half of the 4 million partnerships in the U.S. are real estate partnerships, and real estate activity constitutes a large share of pass-through business activity.
Publicly traded REITs allow small investors to invest in diversified, commercial real estate using the same single tax system available to partners and partnerships.
Small and closely held businesses drive job growth and entrepreneurial activity in the U.S. Entity choice is a differentiator that contributes to our entrepreneurial culture.
See the full fact sheet.
Summary
A “carried” interest is the interest in partnership profits that a general partner receives from the investing partners for managing the investment and taking on the entrepreneurial risks of the venture, such as funding pre-development costs, guaranteeing construction budgets, and potential litigation. Carried interest is also granted for the value the general partner adds beyond routine services, such as business acumen, experience, and relationships. Carried interest may be taxed as ordinary income or capital gain depending on the character of the income generated by the partnership. A “carried” interest is the interest in partnership profits that a general partner receives from the investing partners for managing the investment and taking on the entrepreneurial risks of the venture, such as funding pre-development costs, guaranteeing construction budgets, and potential litigation. Carried interest is also granted for the value the general partner adds beyond routine services, such as business acumen, experience, and relationships. Carried interest may be taxed as ordinary income or capital gain depending on the character of the income generated by the partnership.
In the Tax Cuts and Jobs Act of 2017, Congress created a three-year holding period requirement for carried interest to receive long-term capital gains treatment.
In recent years, both Republican and Democratic leaders have proposed making policy changes that would increase the tax burden on carried interest. These include proposals to: (1) convert virtually all real estate-related carried interest income to ordinary income subject to the top tax rates and self-employment taxes; (2) treat carried interest as an interest-free loan from the limited partners to the general partner that is taxable upon grant, regardless of whether the partnership ever generates any profits; and (3) extend the current three-year holding period for carried interest capital gains treatment to five years.
Since carried interest and its tax treatment first emerged as a controversial political issue in 2007, RER has consistently opposed legislative proposals to tax all carried interest at ordinary income rates.
Key Takeaways
Carried interest is essential to real estate investment, supporting housing development, economic growth, and the modernization of U.S. infrastructure. Carried interest changes would harm small businesses, stifle entrepreneurs and sweat equity, and threaten future improvements and infrastructure in neglected areas.
Carried interest is not compensation for services. General partners receive fees for routine services (leasing, property management). Those fees are taxed at ordinary tax rates.
Proposals to tax all carried interest as ordinary income would result in an enormous tax hike on the 2.2 million real estate partnerships and 9.7 million real estate partners across the country who develop, own, and operate income-producing real estate.
Taxing carried interest at ordinary income rates would increase the cost of building or strengthening infrastructure, workforce housing, and assisted living, and would deter risky projects, such as sites with potential environmental contamination.
The tax code should reward risk-taking; the capital gains rate should apply to more than just invested cash. The tax code has never, and should never, limit the reward for risk-taking to taxpayers who have cash to invest. An entrepreneur who forgoes the security of a salary to invest time and effort into starting a business should qualify for capital gains treatment in the same way that a passive investor qualifies when they put their cash into a public stock or private venture.
Carried interest proposals apply retroactively to prior transactions and partnership agreements executed years earlier. The agreements were based on tax law as it existed at the time.
Changing the results years later would undermine the predictability of the tax system and discourage long-term, patient investment.
See the full fact sheet.
Summary
Created in 2017, Opportunity Zones (OZs) are designated, low-income census tracts where qualifying investments are eligible for reduced capital gains taxes. By channeling investment where it is needed, OZs help stimulate jobs, generate economic opportunity, and improve the built environment in low-income communities. The decentralized design of OZs allows more investors and stakeholders to participate in the market and invest in these projects.
The One Big Beautiful Bill Act (OB3 Act), signed into law on July 4, 2025, permanently extended the OZ tax incentives and made a number of helpful reforms that will further increase the provisions’ positive impact in low-income communities.
Since the passage of the OB3 Act, the Real Estate Roundtable has focused on ensuring that investment and capital continue to flow into OZs during the transition from the OZ 1.0 to OZ 2.0 regime.
IRS Notice 2026-40 incorporates several Roundtable recommendations and provides helpful guidance for businesses and funds that are undertaking ambitious, long-duration, and sustained real estate investments.
Specifically, the guidance allows for investments in OZ 1.0 census tracts after 2026 if the expenditure is made in the ordinary course of the business, or if it is pursuant to a working capital plan and the business receives and spends certain percentages of its working capital by the end of 2026.
Key Takeaways
In their short tenure, OZs have created jobs and spurred billions of dollars of new investment in economically struggling communities across the country.
Opportunity Funds finance affordable, workforce, and senior housing; grocery-anchored retail centers; and commercial buildings that create spaces for new businesses and jobs.
Recent estimates suggest OZs have attracted over $120 billion in capital.
Congress should continue working on improvements to the OZ tax incentives to boost their scale and impact. These improvements should include:
See the full fact sheet.
Summary
For over 100 years, with one brief exception (1987-1990), the U.S. has taxed long-term capital gain at a lower rate than ordinary income. Previous administrations have proposed raising capital gains tax rates and taxing unrealized gains.
RER encourages Congress to continue to support investment and job creation with a meaningful capital gains incentive.
Key Takeaways
The reduced capital gains rate partially offsets the higher risk that comes with illiquid, capital-intensive real estate projects, as well as the economic effects of inflation. The current structure decreases the cost of capital, drives long-term investment, encourages productive entrepreneurial activity, draws investment from around the world, and increases U.S. workforce productivity and competitiveness.
Unlike other tax policies, such as immediate expensing, the capital gains preference only rewards smart, productive investments that generate profits.
High taxes on capital income make it harder to attract the investment needed to rebuild our urban centers. Opportunity Zone capital gains incentives facilitated $75 billion in new investment in low-income communities in the first two years after enactment.
Current law on capital gains encourages taxpayers to put capital to work on projects that won’t pay off for many years. By taxing business assets and investments annually, a tax on unrealized gains would remove one of the major incentives for patient, productive capital investment.
Risk capital differs from wage compensation. The entrepreneur who forgoes a traditional job in favor of starting a business forfeits many protections and benefits offered to employees, such as a pre-negotiated salary.
A proposed tax on unrealized gains is quite possibly unconstitutional. Supreme Court jurisprudence has applied a realization requirement to determine whether gains or profits constitute income taxable under the 16th Amendment.
In addition, taxing unrealized gains would trigger wasteful disputes and litigation, detracting from productive economic activity. Annual valuation requirements will require costly appraisals. Valuation disagreements will be a constant source of audits and administrative appeals.
See the full fact sheet.
Summary
Under section 1031, the tax code allows taxpayers to defer capital gains when exchanging real property used in a trade or business for a property of a like-kind.
In 2017, Congress narrowed Section 1031 by disallowing its use for personal property (art, collectibles, etc.). The last six budgets put forward by Democratic Administrations have proposed severe restrictions on real estate like-kind exchanges. Congressional Republicans initially considered repealing 1031 for real estate as well. In 2025, a group of House Democrats introduced legislation that would impose restrictions on such transactions. RER advocates for preserving the current tax treatment of like-kind exchanges.
Key Takeaways
15-20 percent of commercial transactions involve a like-kind exchange. Exchanges help get languishing properties into the hands of new owners who improve them and put them to their best use.
Academic and outside research has found that exchanges spur capital expenditures, increase investment, create jobs for skilled tradesmen and others, reduce unnecessary economic risk, lower rents, and support property values.
Like-kind exchanges allow businesses to grow organically with less unsustainable debt, creating a ladder of economic opportunity for minority-, veteran-, and women-owned businesses and cash-poor entrepreneurs that lack access to traditional financing.
Land conservation organizations rely on exchanges to preserve open spaces for public use or environmental protection.
Like-kind exchanges helped stabilize property markets at the height of the COVID-19 lockdown. Exchanges are even more important during periods of market stress when external financing is harder to obtain.
Roughly 40 percent of like-kind exchanges involve rental housing. Section 1031 helps fill gaps in the financing of affordable housing. Unlike the Low-income Housing Tax Credit, developers can use Section 1031 to finance land acquisition costs for new affordable housing projects.
Exchanges help low-income, hard-hit, and distressed communities where outside sources of capital are less available. Section 1031 also supports public services (police, education) by boosting transfer/recording/property taxes (nearly 3/4 of all local tax revenue).
Section 1031 is consistent with corporate and partnership tax rules that defer gains when the proceeds are retained and reinvested in businesses (sections 721, 731, 351, and 368).
See the full fact sheet.
Summary
The Tax Cuts and Jobs Act of 2017 included strict new limits on the deductibility of business interest, generally restricting deductions to 30 percent of the taxpayer’s EBITDA (earnings before interest, tax, depreciation, and amortization). However, the bill also included a key provision that allows commercial real estate (a real property trade or business) to opt out of the interest limitation. The One Big Beautiful Bill Act (OB3 Act) included a provision that would allow more real estate businesses to fully deduct their business interest and qualify for 100 percent bonus depreciation on their nonresidential interior improvements.
Recent proposals from Members of Congress would further tighten restrictions on the deductibility of interest and disallow private real estate funds from using the real property trade or business election. Other legislation would deny business interest expense deductions for owners of data centers and large owners of single-family rental homes.
Key Takeaways
Debt is a fundamental part of a real estate entity’s capital structure and, in addition to property acquisition costs, is used to finance day-to-day operations like meeting payroll, buying raw materials, making capital expenditures, and building new facilities.
New restrictions on interest deductibility would cause enormous damage to U.S. commercial real estate by dragging down property values and discouraging new investment. Fewer loans could be refinanced, fewer projects could be developed, and fewer jobs would be created.
The ability to finance investment and entrepreneurial activity with borrowed capital has driven jobs and growth in the U.S. for generations. America’s capital markets are the deepest in the world and provide our economy with a valuable competitive advantage.
Commercial banks are the dominant source of financing for commercial real estate investment. Like other entrepreneurs, small and medium-sized real estate developers and investors lack access to equity markets and rely on traditional lending to grow and expand.
The OB3 Act’s change to the EBITDA/163(j) definition is a positive development that will allow more real estate businesses to fully deduct their interest while also expensing their property improvements and upgrades. The change will accelerate the modernization and repositioning of real estate assets that is critical to meet post-pandemic business needs.
Concerns regarding excessive borrowing or use of leverage are better addressed through flexible financial regulatory tools that can be revisited and revised, not tax penalties that permanently distort the allocation of capital in the economy.
See the full fact sheet.
Summary
Foreign investment is a major source of capital for U.S. commercial real estate, but new federal regulations, a wave of state-level restrictions, and proposed legislation threaten to deter the deployment of global capital in U.S. assets.
First, in April 2024, the Treasury Department issued final regulations that greatly expanded the reach of the Foreign Investment in Real Property Tax Act of 1980 (FIRPTA), creating a new and unprecedented “look-through” rule that in effect would raise the tax burden on inbound real estate capital. Tax regulations proposed by the Trump administration in October 2025 would repeal the 2024 look-through rule. Separately, in December 2025, Treasury issued final Section 892 regulations and proposed new regulations that could disrupt inbound real estate investment from foreign governmental entities.
Second, at the state level, 20 states have enacted restrictions on foreign investors in real estate and agricultural land, and eight states have considered similar measures.
Third, Congress recently considered a tax proposal—known as Section 899—that would impose higher U.S. tax rates on investors from foreign countries deemed as maintaining “unfair” tax regimes. Section 899 was ultimately dropped from the One Big Beautiful Bill Act (OB3 Act) after the US and OECD agreed to carve out U.S. companies from a global minimum tax agreement.
Key Takeaways
Foreign capital is a critical source of capital for U.S. real estate and infrastructure investment. Policies that discourage foreign investment weaken U.S. competitiveness, raise the cost of capital for U.S. developers, and undermine efforts to revitalize urban cores, modernize infrastructure, and expand the housing supply.
Treasury’s proposed repeal of the FIRPTA look-through rule is a positive development.
The “look-through” rule is retroactive and disruptive. It imposes the regulations on investment structures in place for years and creates significant uncertainty for foreign investors in REITs and infrastructure.
States enacting or considering restrictions on foreign investment in real estate should proceed carefully to prevent unintended consequences that could hold back economic growth and capital formation.
State-level restrictions have national implications and seem to fly in the face of the Commerce Clause of the Constitution in that they interfere with the free flow of interstate and foreign commerce.
Congress should continue to oppose proposals such as Section 899 that could disrupt global capital flows and chill passive investment in U.S. real estate and infrastructure.
If a “retaliatory tax” like Section 899 moves forward, lawmakers should modify the measure to exempt passive, non-controlling minority investment in U.S. real estate in order to protect an important source of financing and capital.
See the full fact sheet.
RER advocates for energy policies that promote a robust supply of affordable power, a safe and reliable grid, and encourage energy efficiency.
RER's Fall 2026 Policy Priorities
Summary
President Trump’s Executive Order on “Unleashing American Energy” calls for policies to: cut energy costs; strengthen the nation’s electric grid by developing “base load” power resources (coal, gas, nuclear) over intermittent sources (solar, wind); streamline federal permitting of energy infrastructure projects; and ensure America wins the global race for AI leadership.
The U.S. commercial real estate industry has a central role to play in achieving the country’s energy and economic goals. With energy demand surging, real estate is a critical partner to support energy investments, increase energy efficiency, and deliver energy savings across the economy.
Key Takeaways
No energy should be wasted, and efficiency should be prioritized. Doing more with less energy consumption is the most cost-effective way for buildings to lower utility bills for owners and tenants and strengthen U.S. energy security. Building retrofits that use less energy save consumers money, support grid reliability, and free up power for AI, mining crypto, and re-shoring the U.S. industrial base.
Investments to modernize and expand the grid are essential to increase energy supply, address utility bill affordability, and meet spikes in demand from AI, manufacturing, and electrification trends. It is crucial to expand grid capacity and invest in long-distance transmission. Federal permitting reform is critical to speed up energy infrastructure projects.
RER supports a national “all of the above” energy strategy that invests in building efficiency, grid modernization, faster permitting, and innovation across all energy sources.
See the full fact sheet.
Summary
US-EPA’s ENERGY STAR is a critical voluntary, non-regulatory public-private partnership focused on energy efficiency in buildings and products. Commercial, residential, and manufacturing stakeholders all rely heavily on ENERGY STAR certifications and other offerings.
RER has rallied a coalition of real estate, manufacturing, consumer tech groups, and energy efficiency advocates to preserve the ENERGY STAR program; support its transition from EPA to the U.S. Department of Energy as the agency with the lead implementation role; and assure the program’s funding through ample, annual appropriations by Congress.
Meanwhile, a number of progressive cities and states (map) have enacted building performance standards (BPS). These mandates impose rules regarding building emissions, electrification, and compliance timelines. The regulatory specifics vary from jurisdiction to jurisdiction—making compliance exceedingly complex and expensive. To help bring consistency to the nationwide “patchwork” of BPS regulations, RER has developed a peer-reviewed policy guide outlining 20 key considerations for any jurisdiction adopting a BPS law.
In addition, non-governmental organizations (NGOs) have developed their own BPS-type standards and climate accounting frameworks. Chief among these are the World Resources Institute’s Greenhouse Gas (GHG) Protocol and the Science Based Targets Initiative (SBTi). These NGO standards increasingly influence decisions of certain pension and sovereign wealth funds, pressuring CRE and other companies to “align” with “net-zero” targets as a condition to providing investment capital.
See the full fact sheet.
Summary
Congressional scrutiny of data centers and AI is likely to continue into the next Congress and the 2028 presidential campaign, driven by rising utility bills, job displacement concerns, and risks posed by autonomous AI agents.
Not every data center or AI policy affects commercial real estate, but some warrant RER’s engagement. Proposals that single out data centers for disproportionate regulation or taxation could establish precedents that might eventually extend to other CRE asset classes and building types.
RER evaluates data center policies against the objectives below, to protect commercial real estate interests while recognizing legitimate energy, infrastructure, and community concerns.
See the full fact sheet
RER supports public policy that minimizes regulatory burdens and encourages the availability of credit and the formation of capital while maintaining appropriate systemic safeguards.
RER's Fall 2026 Policy Priorities
Summary
The Terrorism Risk Insurance Act (TRIA) provides a critical federal backstop that enables insurers to offer terrorism risk coverage necessary for commercial real estate financing, development, and operations. Since its enactment in 2002 following the Sept. 11 attacks, TRIA’s public-private framework has supported insurance market stability and economic resilience at minimal cost to taxpayers.
The program expires Dec. 31, 2027. Bipartisan legislation passed by both chambers would extend TRIA for seven years, through Dec. 31, 2034. However, differences between the House and Senate bills must be resolved before a reauthorization can become law. RER supports prompt enactment of a long-term extension that preserves the program’s effectiveness.
Key Takeaways
TRIA is a proven public-private risk-sharing program that helps ensure access to terrorism insurance coverage and limits taxpayer exposure through mandatory recoupment mechanisms.
The TRIA Program Reauthorization Act of 2026 (H.R. 7128) was advanced by the House Financial Services Committee on Jan. 22, 2026, with an overwhelming 51–2 bipartisan vote. The bill was officially reported to the full House for consideration on March 19, 2026. The measure passed the U.S. House of Representatives 373–15 on June 29.
On April 27, 2026, a broad bipartisan group led by Sens. Dave McCormick (R-PA), Tina Smith (D-MN), Thom Tillis (R-NC), and Ruben Gallego (D-AZ) introduced the companion Senate version. The U.S. Senate passed a companion measure (S. 4395) by unanimous consent on Sept. 28, 2026.
The Senate bill maintains the program’s existing core structure. The House bill would raise the minimum loss threshold for certification of an act of terrorism from $5 million to $10 million beginning in 2029 and add certification-related Treasury requirements.
Both bills aim to extend the Terrorism Risk Insurance Program for an additional seven years, moving the expiration date from Dec. 31, 2027, to Dec. 31, 2034. Because the two chambers passed different versions, the legislation awaits reconciliation between the House and Senate before a final bill can be sent to the president. The measure is widely expected to be attached to a larger vehicle like the National Defense Authorization Act (NDAA) or reconciled during the end-of-year legislative session.
See the full fact sheet.
Summary

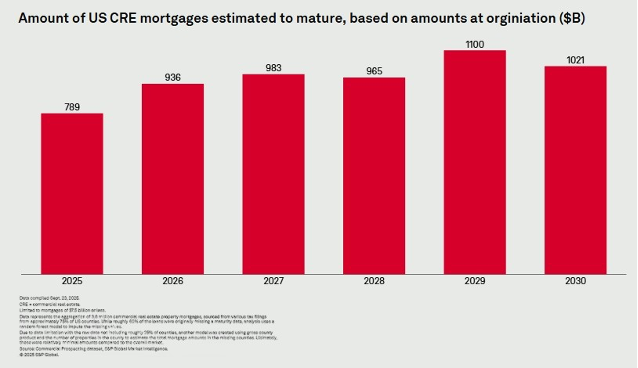
Nearly $983 billion of U.S. commercial real estate mortgages are estimated to mature in 2027. To help rebalance the wave of maturing loans, it is important to advance measures that will encourage additional capital formation and loan restructuring.
As urged by RER, a policy statement—Policy Statement on Prudent Commercial Real Estate Loan Accommodations and Workouts—issued by regulatory agencies encouraging financial institutions to work constructively with creditworthy borrowers on CRE loan workouts is helping to see loans through the current environment. Many of these loans require additional equity, and borrowers still need time to restructure this debt. Capital formation is vital to help restructure maturing debt and fill the equity gap. It is also important to avoid pro-cyclical regulatory actions.
Key Takeaways
Providing banks with the flexibility to work constructively with their borrowers during times of economic stress has led to billions of dollars of loan restructurings and reduced undue stress in bank loan portfolios.
The largest U.S. banks’ capital and liquidity levels have grown dramatically since the original Basel III standards were implemented in 2013 in response to the 2008 Global Financial Crisis. Since 2009, Tier 1 capital has increased by 56 percent and Common Equity Tier 1 capital has tripled. Today, as the Federal Reserve recently observed, the U.S. “banking system is sound and resilient, with strong capital and liquidity.”
See the full fact sheet.
Summary
The proliferation of natural catastrophe threats has raised concerns about commercial insurance coverage for real estate. These concerns have highlighted the lack of—and need for—insurance capacity and various lines of commercial insurance. Risks from natural disasters like floods, hurricanes, wildfires, hail, tornadoes, and drought cost the U.S. billions of dollars each year. Even if policyholders are able to find coverage for these various lines, prices are increasing dramatically. A lack of adequate coverage will lead to economic uncertainty, harm stakeholders, and undermine the growth of communities.
U.S. commercial property insurance premiums grew by over 15 percent annually between 2019 and 2024, doubling as a share of rental income and operating expenses. The national average growth rate reached 7.6 percent (with some markets seeing year-over-year surges exceeding 17 percent), well above historical norms of 2 percent to 3 percent.
Multifamily and apartment properties experienced the highest median compound annual growth rates (CAGRs) and frequent annual increases exceeding 10 percent. Apartment insurance costs jumped an average of 45 percent year-over-year in 2024 alone.
Spending legislation passed this year has reauthorized the National Flood Insurance Program (NFIP) through Dec. 11, 2026.
RER, along with its industry partners, continues to work constructively with policymakers and stakeholders to address market failure and enact a long-term reauthorization of an improved NFIP.
Key Takeaways
Natural catastrophe losses have tripled over the past decade, with severe storms surpassing hurricanes as the costliest insured weather peril.
Commercial property insurance premiums continue to rise, with apartment insurance costs increasing an average of 45 percent year-over-year in 2024.
Construction costs have risen nearly 40 percent since 2020, leaving many properties insured below their actual replacement value.
Commercial property owners continue to take steps to mitigate the risk of natural disasters and potentially lower their insurance costs.
See the full fact sheet.
Summary
The Corporate Transparency Act (CTA) was enacted to combat illicit finance, money laundering, and terrorism financing by requiring certain companies to disclose information about their beneficial owners to the Treasury Department's Financial Crimes Enforcement Network (FinCEN).
In February 2025, RER joined a coalition urging Treasury to delay reporting requirements shortly before the department announced enforcement relief. (Coalition Letter, Feb. 3, 2025)
On Aug. 11, 2026, FinCEN issued a final rule permanently eliminating beneficial ownership information (BOI) reporting requirements for U.S. companies and U.S. persons. Effective Aug. 14, the rule finalizes the narrower framework adopted in March 2025, providing long-term regulatory relief for millions of U.S. businesses, including commercial real estate entities. (Roundtable Weekly, Oct. 2, 2026)
The Real Estate Roundtable (RER) continues to work with policymakers in support of a balanced approach that would inhibit illicit money laundering activity without the imposition of costly reporting requirements for real estate investors.
Key Takeaways
Treasury’s suspension of CTA enforcement for domestic entities significantly reduces compliance burdens for real estate businesses that rely on LLC structures.
See the full fact sheet.
Summary
In 2023, the U.S. Securities and Exchange Commission (SEC) proposed changes to require SEC-registered investment advisers to put all their clients’ assets, including all digital assets like Bitcoin and certain physical assets like real estate, with “qualified custodians.” The proposal would have required a written agreement between custodians and advisers, expanded the “surprise examination” requirements, and enhanced recordkeeping rules. These rules were originally designed for digital assets. The proposal’s “reasonable” safeguarding requirements are ambiguous as applied to real estate. Furthermore, the SEC’s release contained an inaccuracy regarding the way deeds evidencing ownership of real estate are recorded. RER opposed the proposed rule on real estate and pushed for an exception for real estate.
Following extensive industry pushback, particularly regarding its application to real estate, digital assets, and the high compliance costs for small firms, the SEC issued a notice on June 12, 2025, withdrawing the proposal.
Key Takeaways
The withdrawal of the SEC's proposed "Safeguarding Rule" in June 2025 is a major relief for the real estate industry. The proposal would have categorized physical real estate as a client "asset" requiring a qualified custodian, a requirement industry groups called "preposterous" and "unworkable."
See the full fact sheet.
Summary
On Sept. 19, 2025, the White House released an Executive Order, fact sheet, and website announcing Gold and Platinum “Trump Cards.” The program is intended to grant permanent residency in the U.S. for immigrants with high net worth. The administration’s announcement directs the Secretaries of Commerce, State, and Homeland Security to coordinate and establish a program that expedites “green cards” issued under the EB-1 and EB-2 visa categories for foreign nationals who make a “significant financial gift to the Nation.”
This new green card program raises important questions:
Key Takeaways
The new Trump Cards and the EB-5 visa program provide separate visa pathways to attract global capital and top-tier talent.
Trump Cards do not and legally cannot replace EB-5 visas.
The EB-5 program is the established, statutorily authorized pathway to attract foreign investors to the U.S. It has delivered $350 billion in economic impact and created over 1.5 million American jobs—at no cost to taxpayers—and should continue to be fully supported by Congress and the administration.
Congress should permanently authorize the EB-5 program. It should give the foreign investment market stability by authorizing regional centers in 2026, ahead of their scheduled expiration in 2027.
See the full fact sheet.
Summary
On Aug. 7, 2025, President Trump issued an Executive Order titled “Democratizing Access to Alternative Assets for 401(k) Investors,” signaling a fundamental shift in federal policy regarding access to asset classes previously reserved for institutional investors.
The EO aims to expand access to alternative assets, including private equity and real estate, through 401(k) plans by reducing regulatory obstacles and clarifying fiduciary responsibilities. The U.S. Department of Labor (DOL) and Securities and Exchange Commission (SEC) are responsible for advancing related regulatory changes.
The DOL released a proposed rule on advisors’ duties when recommending alternative investments for defined contribution plans on March 30, 2026. RER submitted comments in support of the proposed rule. On Nov. 5, 2026, the DOL submitted its final rule to the White House Office of Management and Budget (OMB) for review, a key step before the rule can be published.
Key Takeaways
In the August order, President Trump directed the DOL to propose new regulations on alts in retirement plans subject to the Employee Retirement Income Security Act (ERISA) within six months. It also directed the DOL to work with other regulators to determine necessary rule changes to ease alternative investment access in 401(k)s, and for the SEC to help with that effort in participant-directed retirement plans.
While such alternative investments have long been part of defined-benefit plan portfolios, such as pensions, they are not expressly barred from defined contribution plans. Nonetheless, fiduciary rules make it challenging to include them in 401(k)s.
See the full fact sheet.
The conflict in Iran raises additional security concerns. Iran poses a credible, near-term threat to the U.S. homeland, utilizing cyber operations, targeted assassination plots against officials, and potential proxy network activations to retaliate against U.S. strikes in the Middle East. Increased risks include cyberattacks on critical infrastructure, violent extremist radicalization, and attacks on religious or government targets by Iran-linked actors.
RER supports measures to more effectively address terrorism and criminal threats through a multifaceted approach involving intelligence gathering, law enforcement, community engagement, and information-sharing partnerships, with a focus on prevention, disruption, and prosecution.
RER's Fall 2026 Policy Priorities
Summary
Rising incidence of cyber and physical security threats—including terrorism, cyberattacks, and organized crime—have heightened concerns about protecting commercial properties and critical infrastructure.
The conflict in Iran raises additional security concerns. Iran poses a credible, near-term threat to the U.S. homeland, utilizing cyber operations, targeted assassination plots against officials, and potential proxy network activations to retaliate against U.S. strikes in the Middle East. Increased risks include cyberattacks on critical infrastructure, violent extremist radicalization, and attacks on religious or government targets by Iran-linked actors.
The Islamic Revolutionary Guard Corps (IRGC) and its affiliates are capable of conducting asymmetric operations and creating and strengthening proxy networks within the U.S. The conflict has prompted warnings from the FBI regarding intelligence, espionage, and potential attacks from Iran-linked individuals.
The conflict may motivate homegrown violent extremists or Iranian proxies to launch attacks on U.S. soil, targeting public gatherings, faith-based institutions (synagogues, mosques), and universities. While direct state-sponsored attacks are less common, Iran may leverage its global network of proxies, such as Lebanese Hezbollah, or activate "sleeper cells" to carry out asymmetric retaliation.
In addition to the challenges posed by Iran and its proxy groups, the ongoing Russian invasion of Ukraine and rising tensions in Asia have raised security concerns about the increased incidence of cyberattacks from the Russian Federation, the People’s Republic of China (PRC), North Korea, and other state actors.
Information sharing is vital for the commercial facilities sector to enhance cybersecurity, improve incident response, mitigate physical threats, build community resilience, and maintain a competitive edge by fostering collaboration and innovation among different facilities and organizations.
Key Takeaways
Recent high-profile hacking attacks underscore the need to fortify the nation’s IT infrastructure against cyberattacks. There are also growing concerns that cyberattacks could exploit AI vulnerabilities to gain unauthorized access to facilities or sensitive data.
RER supports enhanced information sharing and cooperation among its membership with key law enforcement and intelligence agencies through its Homeland Security Task Force and Real Estate Information Sharing and Analysis Center (RE-ISAC).
Policymakers should avoid imposing duplicative or inconsistent regulations that create additional challenges for those tasked with defending the nation’s critical infrastructure and undermine cyber preparedness.
See the full fact sheet.
RER supports innovative policy incentives that expand the nation’s housing supply and improve housing affordability.
RER's Fall 2026 Policy Priorities
Summary
There is a chronic shortage of housing in the U.S. that is driving up housing prices and making it more difficult for lower-income individuals to find safe, affordable housing. Housing production in the U.S. is not keeping pace with expanding housing needs. The underbuilding gap in the U.S. now totals more than 5.5 million housing units. The impact of this growing problem is far-reaching and undermines economic growth—particularly in urban areas. Sweeping bipartisan housing legislation, the 21st Century ROAD to Housing Act, was enacted in July 2026, without the Senate bill’s unconstitutional seven-year forced-sale mandate targeting build-to-rent (BTR) housing.
In April, RER released a white paper authored by Paul Clement of Clement & Murphy, PLLC, finding that Title IX of the Senate-passed bill raises serious constitutional concerns under the Takings Clause, equal protection, and federalism principles, through unprecedented federal restrictions on certain single-family housing owners, including the forced-sale mandate for BTR homes. RER and coalition partners strongly supported the House amendment, which eliminated the forced-sale mandate while preserving supply-focused reforms to modernize federal housing programs, reduce regulatory barriers, encourage new construction, and support capital formation.
Key Takeaways
RER has partnered with 16 other national real estate organizations to jointly advocate for policies that will help to increase housing supplies, grow jobs, and modernize our nation’s critical infrastructure.
See the full fact sheet.
Summary
The U.S. faces a severe shortage of affordable housing as production has failed to keep pace with demand. At the same time, certain other commercial real estate assets like office buildings are under significant stress due to structural shifts in workplace demand. RER is encouraging lawmakers to help revitalize cities, boost local tax bases, and address housing challenges by enacting a tax incentive and federal loan support for converting older, underutilized buildings to housing. RER also supports a meaningful expansion of the Low-Income Housing Tax Credit (LIHTC).
Key Takeaways
Congress should help expand and grow the supply of affordable and workforce housing by investing greater resources in time-tested tax incentives like the LIHTC and adopting creative new approaches that support the conversion of underutilized, existing buildings to housing.
Property conversions are a cost-effective way to increase housing supply, create jobs, and generate critical sources of local property tax revenue.
The LIHTC is an efficient, market-based housing solution that relies on the private sector to finance, build, and operate affordable housing by creating a federal incentive for new construction and redevelopment.
See the full fact sheet.
Summary
In response to the Global Financial Crisis in September 2008, the U.S. Treasury placed Fannie Mae and Freddie Mac into conservatorship under the oversight of the Federal Housing Finance Agency (FHFA). This action was intended to stabilize the mortgage market and restore confidence in the government-sponsored enterprises (GSEs). It also involved an injection of $190 billion of capital, while creating an explicit U.S. government guarantee. The ongoing conservatorship means that the government has total control over these huge government-backed mortgage enterprises, with $7.7 trillion in combined assets.
Conservatorship was not meant to be indefinite. More than 18 years later, the GSEs are in a much stronger financial position and have repaid the $187 billion used to preserve Fannie and Freddie during the financial crisis. Yet, retiring the government’s preferred and common equity stake would require a refinancing of massive scale, a taxpayer gift from the U.S. Treasury of tens of billions of dollars to Fannie and Freddie, or both.
The GSEs are currently "effectively owned" by the U.S. Treasury, which holds senior preferred stock and warrants for 79.9 percent of their common stock. While they have built significant reserves, the Congressional Budget Office (CBO) projected that their equity value by early 2027 would still fall short of full recapitalization requirements.
Policymakers have increasingly discussed various reform proposals, including ending the conservatorship, full privatization, hybrid models, and continued government backing with additional safeguards. The administration has set reform as a key priority, yet concrete details have yet to emerge.
As policymakers consider privatization or structural reforms, it is essential to the real estate industry and the broader economy to preserve a well-functioning housing finance system that supports homeownership, expands affordable housing supply, and sustains economic growth.
The enactment of the 21st Century ROAD to Housing Act in July 2026 directly impacts GSE operations and capital deployment, moving the goalposts for structural housing finance reform:
Key Takeaways
The tension between the executive branch's administrative ambitions and the legislative reality in Congress shapes the future of both GSE reform and institutional housing rules. While the administration utilizes regulatory agencies to bypass legislative gridlock, congressional opposition and structural legal hurdles create significant friction.
The FHFA and the Treasury Department are quietly exploring an administrative "recapitalization and release" framework. With the GSEs holding $328 billion in combined capital, the administration is evaluating a consent decree that would restructure the Treasury’s senior preferred stock and allow the enterprises to exit conservatorship without a new act of Congress.
A complete, rapid exit from conservatorship is considered unlikely in the immediate term due to the technical complexity of raising enough capital to meet regulatory requirements. Instead, a gradual transition involving partial share offerings is more likely.
A critical future debate is whether the government will provide a "paid-for explicit guarantee" on GSE mortgage-backed securities (MBS). Without this, critics warn mortgage rates could spike due to increased risk for private investors.
However, one key concern for a successful exit is the "explicit guarantee." If the government does not legally guarantee the mortgages post-exit, mortgage rates could rise by 0.2 to 0.8 percentage points ($500 to $2,000 more per year for a typical buyer). An explicit, paid-for guarantee would likely stabilize the 30-year fixed-rate mortgage but would require an act of Congress.
If Fannie and Freddie are transitioned to private ownership, the process must ensure financial stability, avoid market disruptions, and protect access to affordable mortgages.
Reforms to the GSEs should be part of a larger national transformation in housing policy to unleash a wave of new housing construction and fully address the underbuilding gap, including Yes in My Backyard (YIMBY) policies, property conversion incentives and reforms to zoning and permitting rules, Opportunity Zones (OZs), and the Low-Income Housing Tax Credit (LIHTC).
See the full fact sheet.