Senate Passes Bipartisan Permitting Reform Bill

The Senate passed sweeping bipartisan permitting reform legislation Thursday night in a 62–33 vote, sending the measure to the House as lawmakers face a narrowing window to reach a deal before the end of the 119th Congress. The Bipartisan American Affordability and Jobs (BAAJA) Act (S. 5653) would streamline federal reviews for energy and infrastructure projects, expand electricity transmission capacity, and address rising power costs. (Roll Call | NYT, Nov. 20)

State of Play

  • The Senate approved the legislation with support from 47 Republicans, 14 Democrats, and independent Sen. Angus King (I-ME). The bill is the most significant energy legislation to pass the Senate since the Inflation Reduction Act in 2022. (Politico, Nov. 20)
  • Bipartisan support: Backed by President Trump and a broad coalition of energy and business groups, the legislation marks a significant step toward permitting reform after years of negotiations. (American Action Forum | Politico Pro, Nov. 19)
  • Permitting reform: The legislation would streamline federal environmental reviews, accelerate approvals for energy and transmission projects, and limit legal challenges. The reforms aim to expand electricity supply and lower costs as growing demand from data centers, AI, and manufacturing strains the nation’s electric grid. (Axios | Washington Post, Nov. 19 | Roundtable Weekly, Nov. 13)

Data Centers
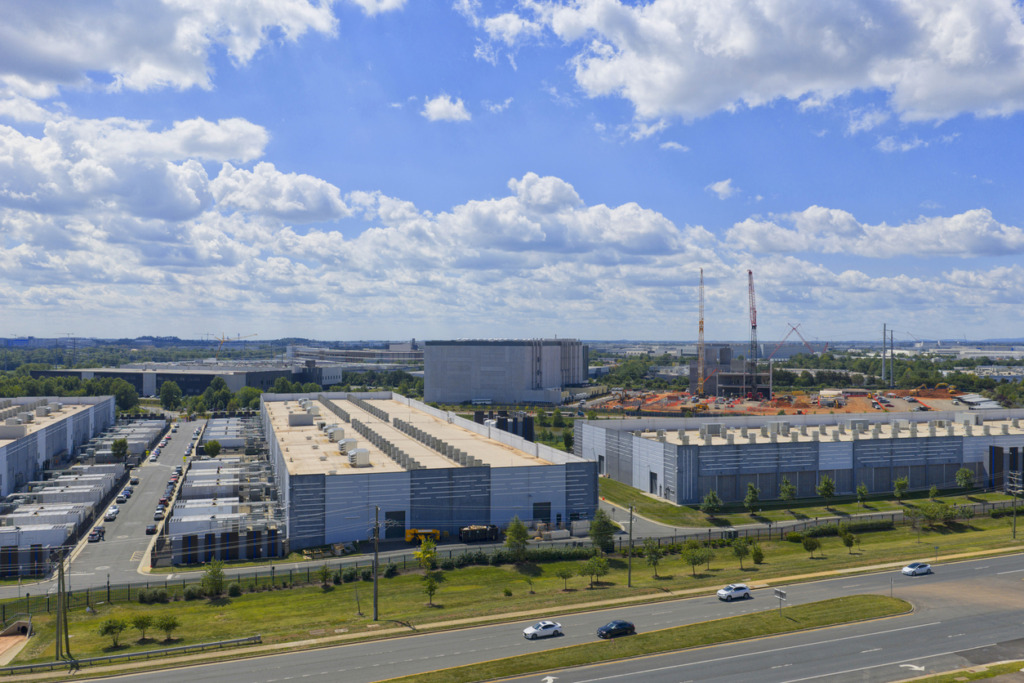
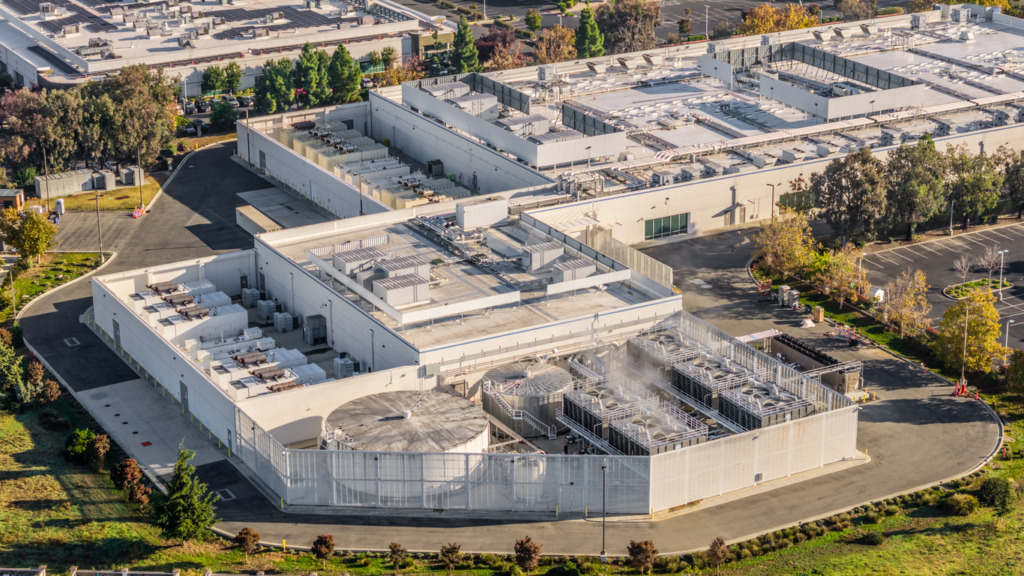
  • The Senate-passed bill would establish protections intended to ensure data centers pay both their share of existing grid costs and the additional infrastructure costs associated with their electricity demand, preventing those expenses from being shifted to other ratepayers.
  • The measure would direct the Federal Energy Regulatory Commission (FERC) to implement the requirements through a subsequent rulemaking. (Bipartisan Policy Center, Nov. 3 | Washington Post, Nov. 19)
  • The Senate proposal goes further than the House-passed Ratepayer Protection Act, which directs states and utility regulators to merely consider additional protections for electricity customers rather than establish mandatory federal requirements.

Distributed Energy at Buildings
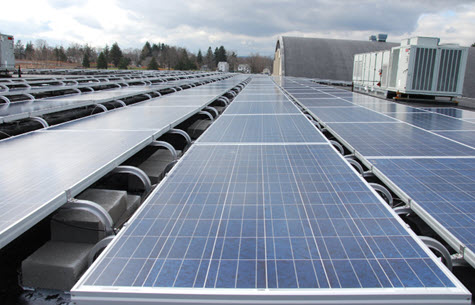
  • One provision in BAJAA of particular interest to real estate concerns “behind the meter” equipment at buildings like rooftop solar, batteries, and back-up generators.
  • Section 2108 would require bundling of these distributed generation resources to operate as “virtual power plants,” giving electricity back to stressed grids during times of peak demand. (Foley Hoag, Nov. 6 | Bipartisan Policy Center, Oct. 2)
  • If enacted, Section 2108 could provide a federal policy lever to help standardize regional efforts for data centers to “bring their own capacity” when applying for interconnections – like the policy instituted by the nation’s largest grid operator. (PJM Interconnection, Aug. 13).
  • The provision could also spark more deals like one recently struck by Google. The hyperscaler will pay an energy company to aggregate distributed resources from residential, commercial, and industrial customers in a 100-MW virtual power plant agreement – as a fast way to unlock new capacity for data center interconnections while benefitting ratepayers financially. (Utility Dive, Oct. 22)

RER Advocacy

  • The Real Estate Roundtable (RER) has consistently supported bipartisan permitting reform to strengthen grid reliability, lower energy costs, and accelerate infrastructure investment. Duplicative federal reviews delay the delivery of affordable, reliable electricity to homes and commercial buildings. (RER Executive Summary | Energy Policy Priorities, Fall 2026 | Roundtable Weekly, Oct. 23)
  • The Senate’s bipartisan action is an important step toward removing barriers that delay critical infrastructure projects and drive up costs,” said Jeffrey DeBoer (President and CEO, RER). “We urge the House to build on this progress and advance practical permitting reforms that strengthen grid reliability, support investment, and help meet the nation’s growing energy needs.”
  • In September comments to the North American Electric Reliability Corporation (NERC), RER also emphasized that regulatory obligations should reflect the distinct responsibilities of building owners, operators, and tenants, particularly when tenants control the equipment and electricity consumption driving those costs. (RER Policy Priorities | Roundtable Weekly, Sept. 18)

What’s Next

  • House outlook: Speaker Mike Johnson (R-LA) plans to bring the bill to the floor under a fast-track procedure requiring a two-thirds majority, with a simple-majority vote as a fallback. House Majority Leader Steve Scalise (R-LA) has also indicated that lawmakers may need to reconcile differences with the House-passed SPEED Act. (Politico, Nov. 20)

The narrower Senate vote, Democratic concerns over environmental protections and tribal consultation, and a limited legislative calendar after Thanksgiving could complicate efforts to pass the bill before year-end. (Roll Call | Politico, Nov. 20)
Roundtable Weekly Will Resume Publication on December 4, 2026

The Roundtable’s policy news digest will resume publication on Friday, December 4, 2026.

Recent issues of Roundtable Weekly can be searched by keyword here.

Higher Rates and Global Uncertainty Weigh on CRE Confidence in Q4

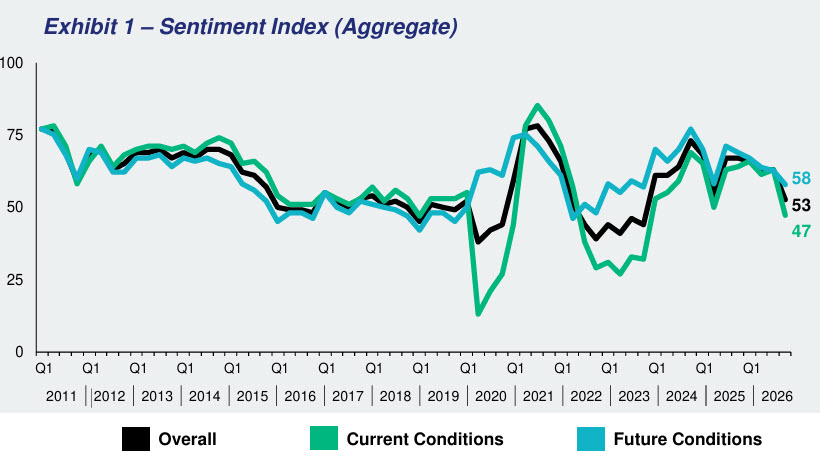
The Real Estate Roundtable (RER) released its Fourth Quarter 2026 Sentiment Index Report this week, revealing a decline in confidence among senior commercial real estate (CRE) executives as higher interest rates and geopolitical uncertainty weigh on valuations and investment decisions. The overall index fell 10 points to 53, even as property operations remained healthy across most sectors. (Q4 Sentiment Index Report)

By the Numbers

  • Overall Sentiment: The Q4 index declined 10 points to 53 from 63 in Q3.
  • Current Conditions: The Current Index fell 16 points to 47, while the Future Index declined 5 points to 58.
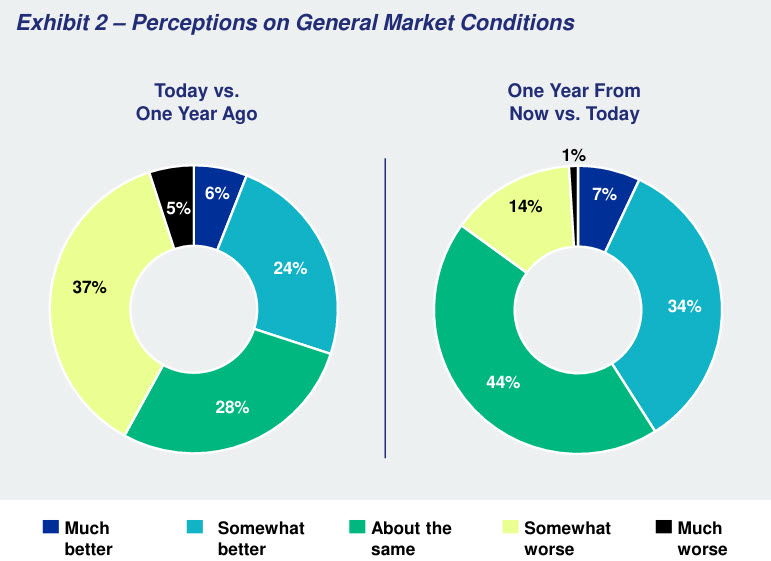
  • Market Outlook: 42% of respondents said market conditions were worse than a year ago, while 41% expect conditions to improve over the next year.
  • Expectations vs. Reality: A year ago, 70% of respondents anticipated improving market conditions. However, only 30% of Q4 2026 respondents believe conditions have improved.

Topline Findings

  • The Q4 2026 Real Estate Roundtable Sentiment Index registered an overall score of 53, a 10-point drop from the previous quarter. The Current Index registered 47, a 16-point decrease from Q3 2026. The Future Index posted a score of 58 points, a decrease of 5 points from the previous quarter. The decreased sentiment this quarter can be attributed to rising interest rates and ongoing geopolitical uncertainty weighing on the market. Interviewees noted a widening gap between how properties are performing and how the market is pricing them, and although operating conditions remain healthy across most sectors, higher rates have unsettled valuations and sent investors back to the sidelines. Most participants expect the setback to pass once rates stabilize. Some see the dislocation as a buying opportunity, though few are ready to commit capital until then.
  • Views continue to vary widely by property type. Open-air retail and industrial have held their value, supported by limited new supply. Office sentiment is improving in select gateway markets, helped in part by leasing from AI companies and the firms benefiting from them. Data centers continue to attract strong demand, though interviewees flagged growing political resistance and questions about long-term need. Multifamily drew the most divided views. Some participants pointed to oversupply in the Sun Belt and the risk that job losses could pressure rents. Others see the recent price declines and early occupancy gains as an attractive entry point.
  • More than half (56%) of respondents believe asset values are lower compared to a year ago, while 29% feel they are unchanged and 15% feel values have increased. Asset values continue to face downward pressure amid interest rate volatility and pricing uncertainty, though the extent of further declines varies by asset quality and sector, with sellers adjusting expectations to facilitate transactions. Looking ahead, the outlook is mixed: 27% expect asset prices to rise over the next year, 42% believe asset values will remain stable, and 31% anticipate that values will decrease.
  • Perceptions on equity capital are down, with 51% believing availability is worse compared to a year ago, 15% thinking it is better, and 34% feeling it is the same. On the other hand, sentiment around debt capital is somewhat positive, as 44% said the availability of debt capital has improved from last year. Looking forward, 28% of respondents believe that equity capital availability will be better in one year and 17% believe debt capital availability will be better.

Roundtable View

  • “Higher interest rates, tariffs and geopolitical uncertainty are weighing on investment decisions,” said Jeffrey DeBoer, President and CEO of RER. “With the midterm elections behind us, both parties have a chance to give businesses a clearer sense of what to expect from Washington.
  • He added, “Affordability, energy prices, and data center growth will stay high on the policy agenda. Preserving key tax and regulatory rules, and streamlining permitting would give businesses more confidence to commit capital to new housing and infrastructure.”

Roundtable on the Road

  • RER SVP and Counsel Ryan McCormick presented at PwC and Maryland Association of CPAs (MACPA) conferences this week, discussing federal tax developments and how the midterm elections could shape the legislative agenda for the remainder of the year and in the next Congress.

Looking Ahead

  • While most respondents expect the current market setback to ease once interest rates stabilize, uncertainty over valuations and the broader economic outlook continues to delay investment decisions.
  • The post-election policy agenda, including housing affordability, energy costs, data center growth, and permitting reform, could help restore investor confidence.

Data for the Q4 survey was gathered by Chicago-based Ferguson Partners on RER’s behalf in October. See the full Q4 report.

NEWS: Higher Rates and Global Uncertainty Weigh on CRE Confidence in Q4

(WASHINGTON, D.C.) — The Real Estate Roundtable (RER) today released its Fourth Quarter 2026 Sentiment Index, a quarterly measure of confidence among senior commercial real estate (CRE) executives. The overall index fell 10 points from the previous quarter to 53 as higher interest rates and geopolitical uncertainty weighed on valuations and led investors to hold off on deals, even as property operations remained healthy across most sectors.

The Current Index fell 16 points to 47, while the Future Index declined 5 points to 58. 42% of respondents said market conditions were worse than a year ago, while 41% expect conditions to improve over the next year.

Current perceptions do not meet the expectations outlined 12 months ago, when 70% of participants anticipated an improvement in general market conditions, with only 30% of Q4 2026 participants believing conditions have in fact improved. (Q4 2025 report)

 “Higher interest rates, tariffs and geopolitical uncertainty are weighing on investment decisions,” said Jeffrey DeBoer, President and CEO of The Real Estate Roundtable. “With the midterm elections behind us, both parties have a chance to give businesses a clearer sense of what to expect from Washington. Affordability, energy prices, and data center growth will stay high on the policy agenda. Preserving key tax and regulatory rules, and streamlining permitting would give businesses more confidence to commit capital to new housing and infrastructure.”

The Q4 Sentiment Index topline findings include:

  • The Q4 2026 Real Estate Roundtable Sentiment Index registered an overall score of 53, a 10-point drop from the previous quarter. The Current Index registered 47, a 16-point decrease from Q3 2026. The Future Index posted a score of 58 points, a decrease of 5 points from the previous quarter. The decreased sentiment this quarter can be attributed to rising interest rates and ongoing geopolitical uncertainty weighing on the market. Interviewees noted a widening gap between how properties are performing and how the market is pricing them, and although operating conditions remain healthy across most sectors, higher rates have unsettled valuations and sent investors back to the sidelines. Most participants expect the setback to pass once rates stabilize. Some see the dislocation as a buying opportunity, though few are ready to commit capital until then.
  • Views continue to vary widely by property type. Open-air retail and industrial have held their value, supported by limited new supply. Office sentiment is improving in select gateway markets, helped in part by leasing from AI companies and the firms benefiting from them. Data centers continue to attract strong demand, though interviewees flagged growing political resistance and questions about long-term need. Multifamily drew the most divided views. Some participants pointed to oversupply in the Sun Belt and the risk that job losses could pressure rents. Others see the recent price declines and early occupancy gains as an attractive entry point.
  • More than half (56%) of respondents believe asset values are lower compared to a year ago, while 29% feel they are unchanged and 15% feel values have increased. Asset values continue to face downward pressure amid interest rate volatility and pricing uncertainty, though the extent of further declines varies by asset quality and sector, with sellers adjusting expectations to facilitate transactions. Looking ahead, the outlook is mixed: 27% expect asset prices to rise over the next year, 42% believe asset values will remain stable, and 31% anticipate that values will decrease.
  • Perceptions on equity capital are down, with 51% believing availability is worse compared to a year ago, 15% thinking it is better, and 34% feeling it is the same. On the other hand, sentiment around debt capital is somewhat positive, as 44% said the availability of debt capital has improved from last year. Looking forward, 28% of respondents believe that equity capital availability will be better in one year and 17% believe debt capital availability will be better.

Sample responses from participants in the Sentiment Index’s Q4 survey include:

“Geopolitical risk is top of mind for everybody. Between Iran, the midterms, and the divides within both parties, there is a great deal of uncertainty, and uncertainty is bad for business.”

“Data centers continue to do well, but the political backlash is building. There are real questions about how many data centers we need, since the technology changes quickly and these buildings have no adaptive reuse.”

“The price reset won’t be massive, and everyone knows it’s coming. What matters is that the whole industry makes it together.”

Data for the Q4 survey was gathered by Chicago-based Ferguson Partners on RER’s behalf in October. See the full Q4 report.

# # #

Senate Advances Bipartisan Permitting Reform Bill

On Nov. 9, the Senate voted 73–25 to begin consideration of the Bipartisan American Affordability and Jobs Act (S. 5653), clearing a key initial procedural hurdle but stopping short of approving the legislation. The bill would overhaul federal permitting for energy and infrastructure projects and modernize transmission planning. (U.S. Senate, Nov. 9)

State of Play

  • Bipartisan sponsors: The bill was introduced Sept. 30 by the leaders of the Senate Environment and Public Works Committee (Chair Shelley Moore Capito (R-WV) and Ranking Member Sheldon Whitehouse (D-RI)) and the Energy and Natural Resources Committee (Chair Mike Lee (R-UT) and Ranking Member Martin Heinrich (D-NM)). A revised version was released Nov. 7. (Bipartisan Policy Center, Oct. 2)
  • NEPA reforms: The bill would set deadlines for environmental reviews, narrow who can challenge projects in court, and limit the time to file challenges under the National Environmental Policy Act (NEPA) to 150 days, matching the House-passed SPEED Act. (Bipartisan Policy Center, Oct. 2)
  • Transmission and grid costs: The bill would give the Federal Energy Regulatory Commission (FERC) backstop authority to site certain interstate transmission lines. It would also require data centers to pay their full share of grid upgrade costs so other customers do not subsidize them. (White & Case, Nov. 11)

What’s Next

  • Senators will consider amendments, addressing concerns including provisions that would relax federal reviews of a project’s impacts on historic properties. Some Democrats who voted to begin debate have indicated they may oppose the final bill depending on the amendments. (Heatmap, Nov. 9)
  • A final Senate vote could come as early as the week of Nov. 16. The House would then need to consider the legislation before the lame-duck session ends.  (White & Case, Nov. 11)
  • President Trump said Nov. 9 that the bill “hasn’t been fully negotiated.” It remains unclear how his comments could affect the legislation’s prospects. (Heatmap, Nov. 9)

The Real Estate Roundtable (RER) continues to support permitting reform to improve energy affordability and meet growing electricity demand. RER has urged Congress to provide certainty for approved projects and eliminate redundant federal reviews that delay affordable, reliable power. (Roundtable Weekly, Oct. 2, 2026)

Ninth Circuit Allows California Scope 1 and 2 Reporting to Proceed, Blocks Scope 3 and Climate Risk Disclosures

On Nov. 9, the U.S. Court of Appeals for the Ninth Circuit ruled that California can enforce certain corporate climate disclosure requirements while blocking others that likely violate the First Amendment. (Foley & Lardner, Nov. 9)

State of Play

  • Scope 1 and 2 reporting: The court allowed California to enforce Senate Bill (SB) 253’s requirement that companies doing business in the state with more than $1 billion in annual revenue disclose emissions from their direct operations (“Scope 1”) and purchased energy (“Scope 2”). The Nov. 10 deadline for initial Scope 1 and 2 reports remained in effect, requiring covered companies to comply while litigation continues. (Foley & Lardner, Nov. 9)
  • Scope 3 reporting: The court found that SB 253’s requirement to report indirect supply chain and value chain emissions (Scope 3), scheduled to begin in 2027, likely violates the First Amendment. The requirement remains on hold while litigation continues. (Ninth Circuit ruling, Nov. 9)
  • Climate-related financial risk reports: The court maintained its freeze on SB 261, which requires companies doing business in California with more than $500 million in annual revenue to report climate-related financial risks. Enforcement remains on hold while litigation continues. (National Law Review, Nov. 9)

What’s Next

  • The case returns to the district court, which will determine, among other issues, whether the Scope 3 provisions can be separated from the rest of SB 253. Covered companies, including commercial real estate firms, remain subject to Scope 1 and 2 reporting requirements. (Cooley, Nov. 10)

The Real Estate Roundtable (RER) continues to advocate for practical, consistent climate disclosure requirements that limit compliance burdens for commercial real estate owners and operators. RER has raised concerns about mandatory Scope 3 reporting, particularly the challenges of obtaining reliable emissions data from tenants and other third parties, and has urged policymakers to avoid costly, overlapping reporting requirements. (Roundtable Weekly, Nov. 21, 2025)

CRE Leaders Gather in Washington to Discuss Post-Election Priorities, Tax Policy, Energy, Global Risks, and More

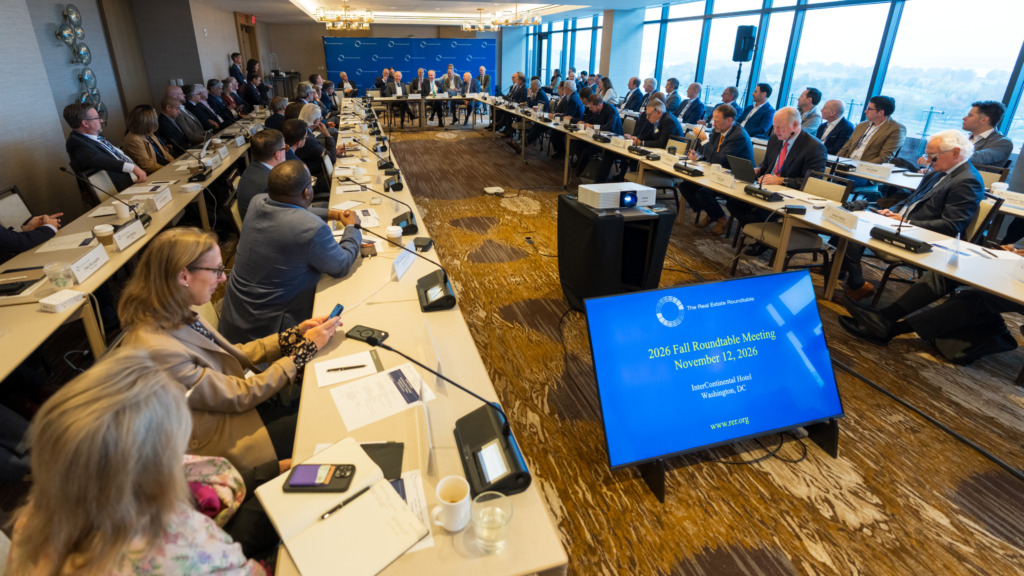
The Real Estate Roundtable’s (RER) Fall Roundtable Meeting convened members in Washington this week, on the heels of the historic midterms, to discuss prospects for year-end legislation and the new Democratic leadership’s expected 2027 agenda for tax, housing, banking, and energy policy.

The two-day program covered prospects for reauthorizing the Terrorism Risk Insurance Program, EB-5 legislation, and passing permitting reform before year-end, opportunities for bipartisan agreement on ways to expand housing supply in the next Congress, and what shifts in tax, trade, housing, and energy policy could mean for commercial real estate investment. (RER’s Fall 2026 Policy Priorities and Executive Summary)

Roundtable Leadership

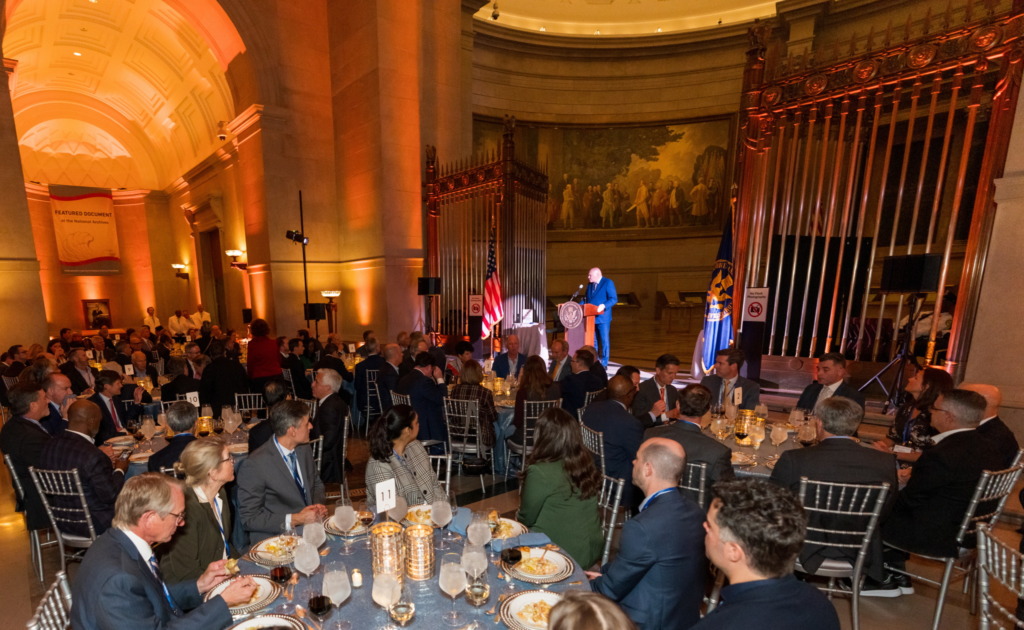
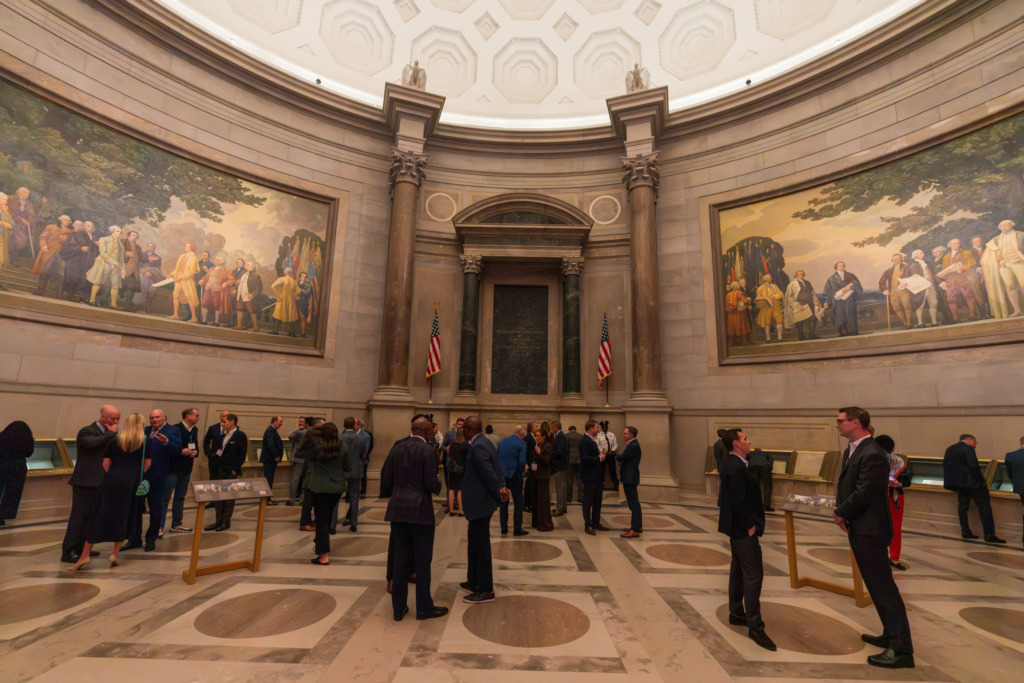
  • At his first Fall Roundtable Meeting as RER Board Chair, Owen D. Thomas (Chairman and CEO, BXP) welcomed members to the policymakers dinner at the National Archives and said he looks forward to leading The Roundtable’s advocacy in Washington and working with newly elected members of Congress to show how commercial real estate supports job creation and economic growth.
  • Speaking just steps from the U.S. Constitution at the National Archives, RER President and CEO Jeffrey D. DeBoer recalled how RER drew on the Fifth Amendment’s Takings Clause and a white paper it commissioned from former U.S. Solicitor General Paul Clement to challenge a provision in the ROAD to Housing Act that would have required companies that build single-family rental homes to sell them after seven years. “Ultimately, that forced-sale proposal … was removed by the language in that very document sitting right behind us,” DeBoer said.
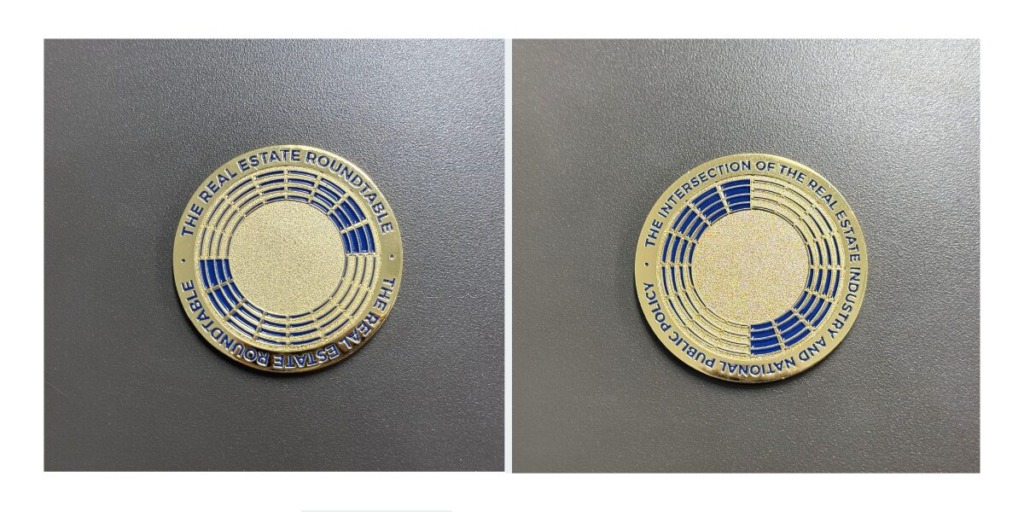
  • DeBoer also spoke about RER’s challenge coin, which members received. “Traditionally, challenge coins represent camaraderie, trust, and a shared mission among leaders,” he said. “This Roundtable coin represents the strength of bringing top real estate owners, lenders, managers, and trade associations together to speak as one cohesive voice in Washington.”

Speakers & Policy Issues

Roundtable members engaged in policy discussions with the following guests:

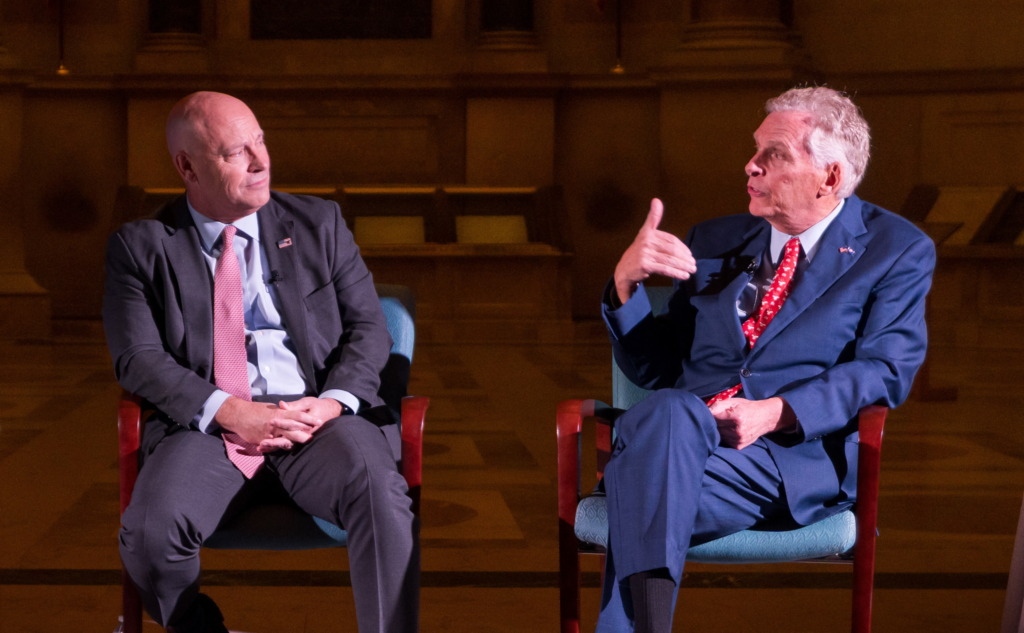
  • (L-R): Marc Short (former Chief of Staff to Vice President Mike Pence and Founding Partner, Advance Strategies Consulting) and Terry McAuliffe (former Governor of Virginia and Democratic National Committee Chair) joined for a bipartisan post-election conversation on the state of American politics, the shifting balance of power in Congress, and the economic issues driving voters.
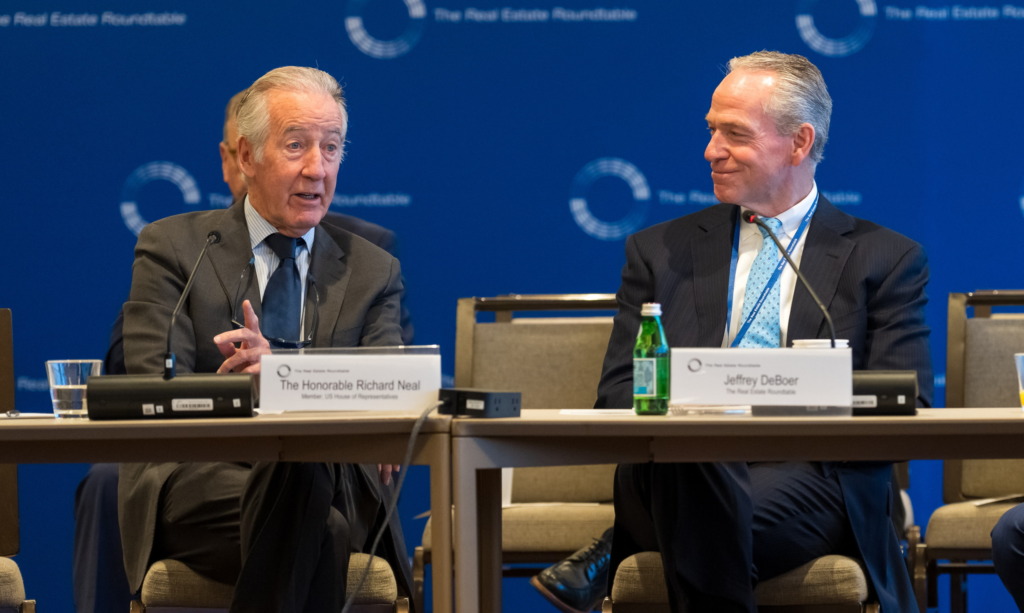
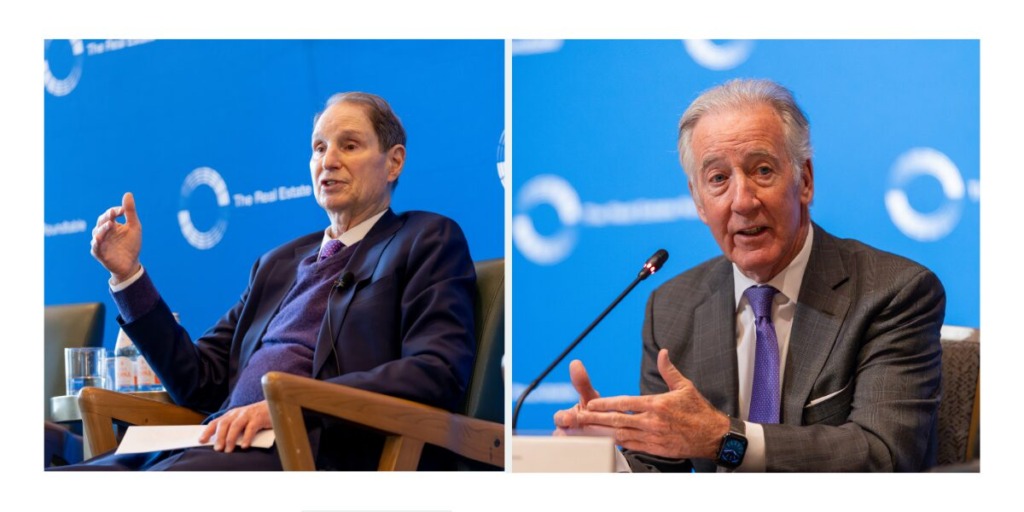
  • (L-R): Rep. Richard Neal (D-MA) (Ranking Member, House Ways and Means Committee), who is expected to return as committee chair in January, joined John Fish (Chairman and CEO, Suffolk; Past Chair, RER) to discuss economic policy priorities for the next Congress, Affordable Care Act tax credits, tariffs, the federal deficit, and how zoning and land-use decisions affect housing supply and affordability. (RER’s Tax Policy Priorities)
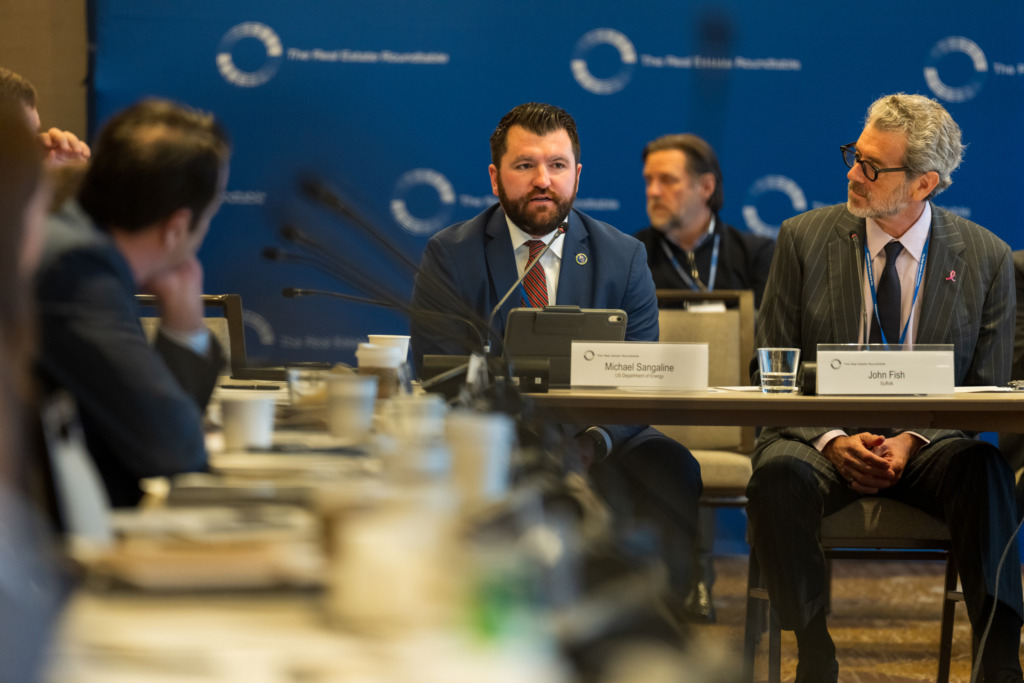
  • (L-R): Mike Sangaline (Deputy Assistant Secretary of Building Technologies and Development, U.S. Department of Energy (DOE)) and Anthony Malkin (Chairman and CEO, Empire State Realty Trust; Chair, RER’s Sustainability Policy Advisory Committee) discussed how energy production, grid access, ENERGY STAR’s transition to DOE, and rising electricity demand from data centers are shaping commercial real estate development. (RER’s Energy Policy Priorities)

Next on RER’s meeting calendar is the all-member State of the Industry Meeting (SOI) on Jan. 28-29, 2027, in Washington, D.C., which will include policy advisory committee meetings.

Democrats Outline Tax Policy Agenda Following Midterm Elections

Following Democrats’ sweeping victories in the midterm elections, the lawmakers expected to lead Congress’ two tax-writing committees outlined their priorities for the next Congress, emphasizing affordability, corporate taxation, trade policy, and congressional oversight. (Politico | Sen. Wyden Press Release, Nov. 4)

State of Play

  • Senate Finance Committee: Sen. Ron Wyden (D-OR) is positioned to regain the chairmanship he held from 2014-2015 and 2021-2025. Sen. Wyden indicated he intends to focus the Finance Committee on raising taxes on billionaires and corporations, strengthening tax enforcement, reducing health care costs, and reasserting congressional authority over trade and tariffs. Wyden also signaled plans for expanded oversight of major corporations. (Sen. Wyden Press Release, Nov. 4 | The Hill, Nov. 5)
  • House Ways and Means Committee: Rep. Richard Neal (D-MA) in line to return as Chairman, outlined an affordability-focused agenda that includes reducing costs for families, addressing health care, strengthening federal programs, and developing a more sustainable trade policy. (Rep. Neal Statement, Nov. 4)
  • Democrats are expected to focus on affordability and high costs and will be looking for ways to use the tax code to address those areas while sharpening their message ahead of the 2028 campaign, which will also likely lead to further focus on raising additional tax revenue from upper-income taxpayers. (PoliticoPro, Nov. 6)

Opportunity Zones

  • On Nov. 5, the Treasury Department and IRS announced the designation of 6,576 Qualified Opportunity Zones, including 2,594 rural census tracts, under the newly permanent Opportunity Zone program. The designations take effect Jan. 1, 2027, and will remain in place for 10 years. (Treasury Press Release, Nov. 5)
  • The new map is significantly smaller than the opportunity zone 1.0 map, which had 8,764 QOZs. (Bisnow, Nov. 5)
  • The updated program establishes a permanent framework for OZs, with new designations every 10 years, tighter eligibility criteria, and enhanced incentives for rural investment.
  • Since its creation in 2017, the program has attracted more than $110 billion in private investment to designated communities. (Treasury Press Release, Nov. 5)
  • “Today’s announcement of the new designations will help direct private investment to these communities, expand economic opportunity, support job creation, and unlock long-term growth in these communities across the country,” Treasury Sec. Scott Bessent said in a statement. (Bisnow, Nov. 5)
  • RER advocacy: RER’s Opportunity Zone Working Group met with Treasury and IRS officials in August and has emphasized the need for clear transition rules to ensure existing projects can continue under the permanent program. (Roundtable Weekly, Sept. 25)

Data Center Legislation

  • The legislation builds on Sen. Wyden’s August framework. It would eliminate 100% bonus depreciation for data center assets, restrict Opportunity Zone benefits, prevent certain privately held real estate investment trusts (REITs) from treating newly acquired data center rents as qualifying income, and exclude data center equipment and construction costs from research tax credits. (Grant Thornton, Nov. 3 | Roundtable Weekly, Aug. 7)
  • With Sen. Wyden positioned to chair the Senate Finance Committee, the proposal could receive greater attention in the next Congress as lawmakers from both parties examine data center tax incentives and their impact on energy costs and communities. (Roundtable Weekly, Oct. 23 | Roundtable Weekly, Sept. 25)

Roundtable on the Road

His presentation covered implementation of recent tax legislation, opportunities to support housing development and downtown revitalization, and proposals that could significantly change the tax treatment of real estate assets and investment.

What the Midterm Elections Mean for Commercial Real Estate

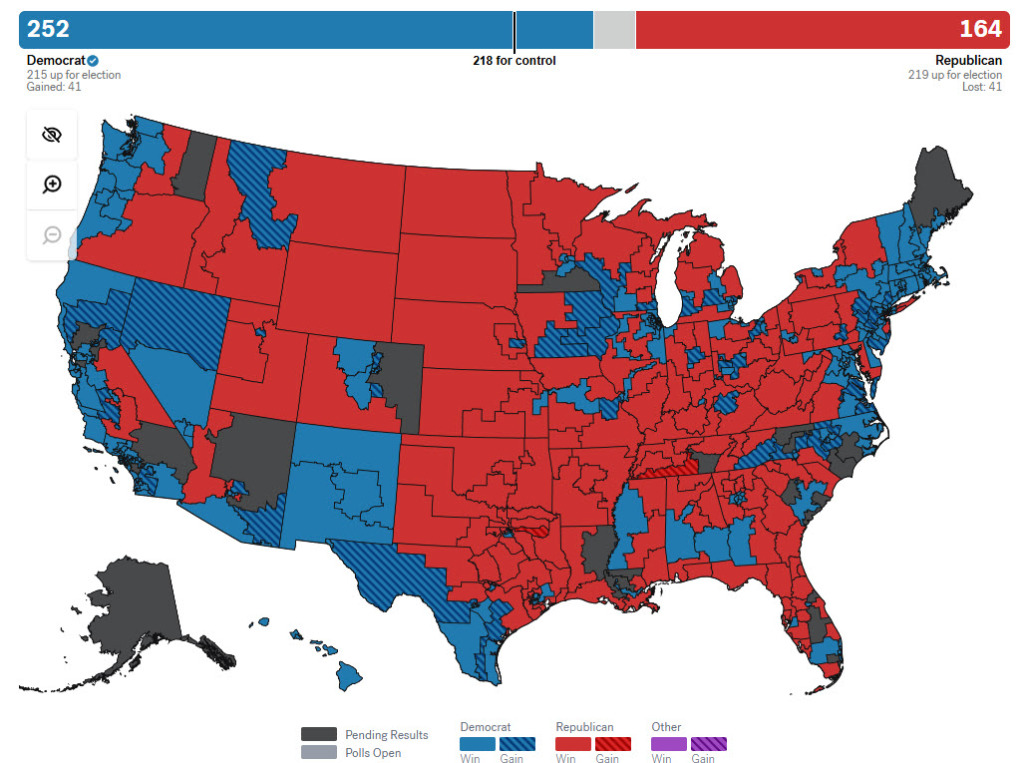
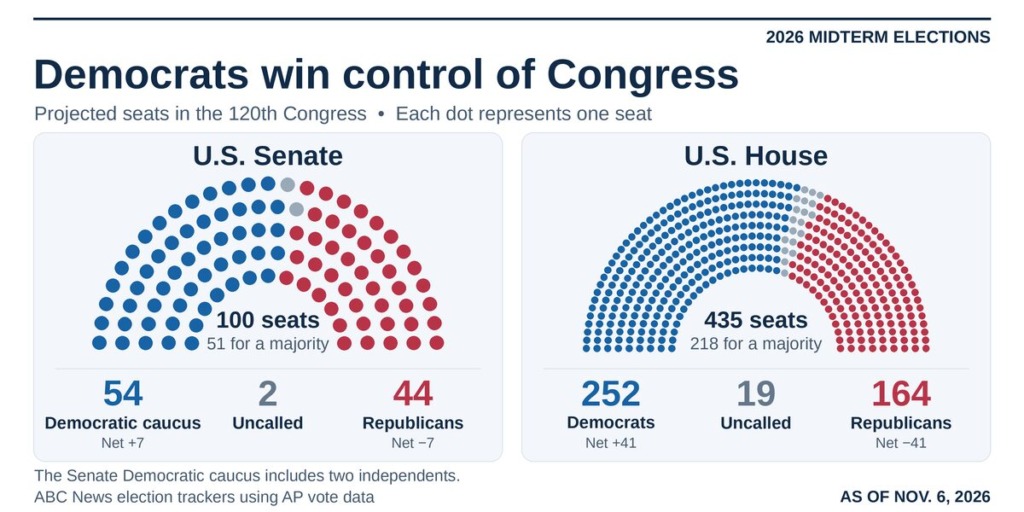
This week, Democrats won control of the House and Senate in Tuesday’s midterm elections. The shift in congressional leadership will put tax policy, housing affordability, and energy policy front and center for the 120th Congress. The first test comes Monday, when the Senate is expected to take a procedural vote on bipartisan permitting reform.

State of Play

  • Rep. Hakeem Jeffries (D-NY) is in line to become House Speaker, and Sen. Chuck Schumer (D-NY) is expected to return as Senate majority leader.
  • Sen. Schumer called the results a “generational remake of the Senate majority” and told reporters the first thing he would do is “reduce people’s costs and work the legislative process so it does.” (Commercial Observer, Nov. 5)
  • House Speaker Mike Johnson (R-LA) told Republican colleagues Wednesday that he would not seek a leadership post in the next Congress. House Majority Leader Steve Scalise (R-LA) and House Judiciary Committee Chair Jim Jordan (R-OH) are both running for minority leader. (Axios, Nov. 4)
  • Control of both chambers gives Democrats greater leverage over government funding and oversight, while President Trump’s veto power limits prospects for major policy reversals.  (Cushman&Wakefield, Nov. 4)
  • “The Roundtable looks forward to working with lawmakers in both parties to continue policy work to expand housing supply, modernize permitting, and support long-term investment in communities across the country,” said Jeffrey D. DeBoer, President and CEO of The Real Estate Roundtable (RER).

Tax Policy

  • Sen. Ron Wyden (D-OR) and Rep. Richard Neal (D-MA) are expected to return as chairs of Senate Finance and House Ways and Means, respectively.  (PoliticoPro, Nov. 4)
  • Both outlined their priorities this week, with Sen. Wyden announcing plans to raise taxes on the wealthiest households and corporations, reassert congressional authority over trade, and expand oversight. Rep. Neal emphasized affordability for working families and rebuilding relationships with U.S. trading partners. (The Hill, Nov. 5)
  • Sen. Wyden has previously released comprehensive proposals to tax unrealized gains, fundamentally reform the taxation of partnerships, and recharacterize all carried interest as ordinary income.
  • Rep. Neal is scheduled to speak at next week’s Fall Roundtable Meeting.
  • Issues to watch include housing supply incentives; partnership tax reform; tax increases on wealth, capital gains, and carried interest; potential new tax burdens on data centers and single-family rental homes; and retaliatory tax measures affecting foreign investment.

Energy Policy

  • Democrats are repositioning clean energy as one part of a broader focus on affordability and the economy. (Axios, Nov. 6)
  • Energy-related issues to watch: Sen. Wyden has said he plans to introduce legislation to restore clean energy tax credits. The broader debate could include efforts to restore Inflation Reduction Act incentives for clean electricity production and investment credits, building efficiency incentives, and credits for electric vehicles and charging equipment. (PoliticoPro, Nov. 3 | Axios, Nov. 6)
  • Data centers: Democrats are weighing stronger federal ratepayer protections, including proposals to require large facilities to pay for grid upgrades or secure their own power. (PoliticoPro, Nov. 5)
  • The bipartisan Ratepayer Protection Act (H.R. 9340), which passed the House 417–3 before stalling in the Senate, could serve as a starting point for stronger federal enforcement. Some Democrats also support temporary construction moratoriums. (PoliticoPro, Nov. 4)
  • Committee leadership: Reps. Jared Huffman (D-CA) and Frank Pallone (D-NJ) are expected to lead House Natural Resources and Energy and Commerce, respectively. Sen. Martin Heinrich (D-NM) is in line to chair Senate Energy and Natural Resources, and Sen. Jeff Merkley (D-OR) could lead Environment and Public Works.  (PoliticoPro, Nov. 3)
  • Appropriations leadership: Sen. Patty Murray (D-WA) is in line to chair Senate Appropriations and could also lead its Energy and Water Development Subcommittee. Sen. Lisa Murkowski (R-AK) is expected to become the full committee’s top Republican and could hold the same role on the Interior and Environment Subcommittee. Those assignments would give both senators a central role in funding negotiations for federal energy and environmental programs. (Bloomberg, Nov. 4)

Permitting Reform

  • The Senate is scheduled to vote Monday, Nov. 9, on whether to advance the bipartisan American Affordability and Jobs Act of 2026 (S. 5653). The bill would revise federal environmental reviews and streamline permitting for energy and infrastructure projects, including electric transmission. It needs 60 votes to advance. (Axios | PoliticoPro,  Nov. 6)
  • The election has complicated the bill’s path. Rep. Jeffries raised concerns through a spokesperson, saying that the bill needs more input from House Democrats. Rep. Huffman has called for waiting until the next Congress. Sen. Heinrich and Sen. Sheldon Whitehouse (D-RI) are pressing for action this year, and Senate negotiators have been working on an amendment to address House concerns. (Politico, Nov. 5 | Punchbowl News, Nov. 6)
  • The Trump administration said Friday that the Pentagon would advance nine new onshore wind projects that had been delayed by security reviews and are the subject of ongoing litigation. The move comes as the White House seeks support for bipartisan permitting reform ahead of the Senate’s Nov. 9 procedural vote. (Politico, Nov. 6)

Capital & Credit and Housing

  • Senate Banking: Sen. Elizabeth Warren (D-MA) is the leading contender to chair the committee in the next Congress. Both Senate Banking and House Financial Services are expected to step up oversight of financial institutions, consumer lending practices, and the administration’s approach to financial regulation. (Time | Reuters, Nov. 5)
  • House Financial Services: Rep. Maxine Waters (D-CA) formally launched her bid Friday to return as chair, a day after Rep. Sean Casten (D-IL) entered the race. Current Chair Rep. French Hill (R-AR) is expected to become the committee’s ranking member. On the Housing and Insurance Subcommittee, Rep. Emanuel Cleaver (D-MO) is seeking the chair, while Rep. Mike Flood (R-NE) is expected to serve as ranking member. (PoliticoPro, Nov. 5 | Reuters, Nov. 6)
  • Housing: Outlining her agenda, Rep. Waters called for expanding affordable housing programs, reforming mortgage finance, and passing legislation to “AI proof’” the financial system and economy. (Rep. Waters letter, Nov. 6)
  • As federal agencies implement the bipartisan 21st Century ROAD to Housing Act, lawmakers could consider follow-up legislation in the next Congress. (Commercial Observer, Nov. 5 | PoliticoPro, Nov. 6)

What’s Next

  • The Senate’s first order of business after the election is a Nov. 9 procedural vote that will test whether the bipartisan American Affordability and Jobs Act (S. 5653) can move before year-end. (Punchbowl News, Nov. 6)

If government funding or surface transportation legislation carries over into the new Congress, either could provide an opening for energy and climate measures. If the highway bill is not addressed in the lame duck, it will be the biggest transportation policy issue for Congress next year. (PoliticoPro, Nov. 3 | Punchbowl News, Nov. 4)

Fed Holds Rates Steady as Inflation Concerns Persist

The Federal Reserve held its benchmark interest rate steady at 3.75–4 percent on Wednesday, pausing after September’s quarter-point increase as policymakers assess persistent inflation and economic conditions. Two officials dissented in favor of another rate hike, underscoring continued pressure to tighten monetary policy. (Federal Reserve, Oct. 28 | The Wall Street Journal, Oct. 29)

State of Play

  • The Federal Open Market Committee (FOMC) voted 10–2 to maintain the current target range, with Federal Reserve Governor Lisa Cook and Cleveland Fed President Beth Hammack favoring a 25-basis-point increase. The decision follows September’s unanimous vote to raise rates for the first time since 2023. (Federal Reserve, Oct. 28 | Federal Reserve, Sept. 16)
  • The Fed characterized economic activity as “expanding at a strong pace,” supported by resilient consumer spending, strong productivity growth, and robust capital investment.
  • Inflation remains elevated, and policymakers emphasized the importance of additional economic data in determining the appropriate policy stance. (Federal Reserve, Oct. 28)
  • The October decision leaves open the possibility of another rate increase before year-end as the Fed continues working toward its 2 percent inflation target. (Federal Reserve)

Why It Matters

  • Elevated interest rates continue to weigh on commercial real estate (CRE) borrowing costs, refinancing activity, and investment. Continued inflation pressures and elevated Treasury yields can increase financing costs for property owners and developers.
  • Nearly $983 billion in U.S. CRE mortgages are estimated to mature in 2027, underscoring the importance of accessible financing as borrowers face higher debt service costs and potentially more challenging refinancing conditions. (RER Policy Priorities, Capital & Credit)
  • The rapid buildout of artificial intelligence (AI) data centers is adding complexity to the Fed’s inflation outlook. Data center investment is supporting economic growth while straining electricity supply and construction capacity. (Politico, Oct. 28)
  • Higher rates could weigh on housing and other interest-sensitive sectors without substantially slowing spending by well-capitalized technology companies. (Politico, Oct. 28)

The FOMC’s final scheduled policy meeting of 2026 will take place Dec. 8–9, when officials will release an updated Summary of Economic Projections.