Opportunity Zone Rules and Maps Take Shape as Congress Weighs Data Center Limits

As states finalize the next Opportunity Zone maps, Treasury and the IRS are seeking input on program rules while lawmakers weigh whether data centers should qualify for OZ tax benefits.

Treasury Seeks Input on OZ Rules

  • In a Sept. 22 notice, Treasury and the IRS requested comments on how to implement the permanent OZ program, specifically regarding housing investment, working capital rules, operating businesses and the tax treatment of long-held investments. Comments are due Nov. 23. (Tax Notes, Sept. 22 | Bloomberg Law, Sept. 23)
  • The request follows proposed regulations issued Sept. 11 on reporting requirements for Qualified Opportunity Funds (QOFs) and OZ businesses, as well as fund certification and decertification. Comments on that separate proposal are due Oct. 16. (PoliticoPro, Sept. 10)

RER Advocacy

  • RER’s Opportunity Zone Working Group has urged Treasury and the IRS to adopt clear, workable rules that allow existing projects to continue through the transition to the permanent program.  The Group also recently met with Treasury and IRS staff in August to discuss guidance for projects spanning the original and permanent OZ programs.
  • The new maps and forthcoming rules will shape where and how OZ capital can support housing, redevelopment and other projects in low-income communities.

New Opportunity Zones Maps

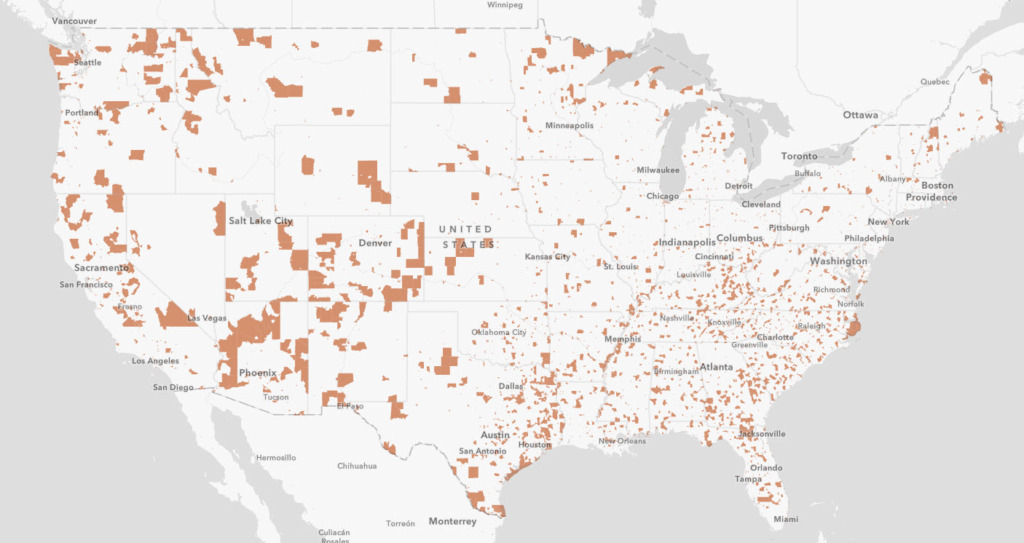
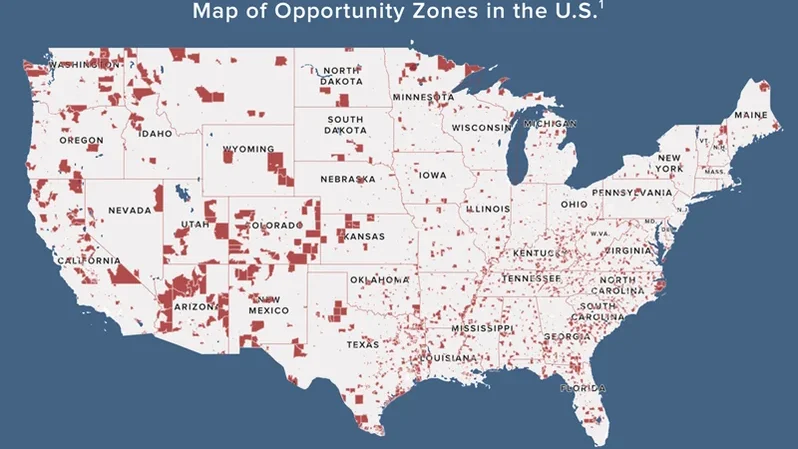
  • Governors are finalizing nominations for the next generation of OZs ahead of a Sept. 28 deadline, with a 30-day extension available upon request. Treasury will certify the new designations, which take effect Jan. 1, 2027 and remain in place for 10 years.
  • The tighter eligibility rules are expected to significantly reduce the number of designated OZs. Roughly, 6,500 zones could be selected nationwide, nearly 26% fewer than the 8,764 designated under the original program. (Bisnow, Sept. 15)
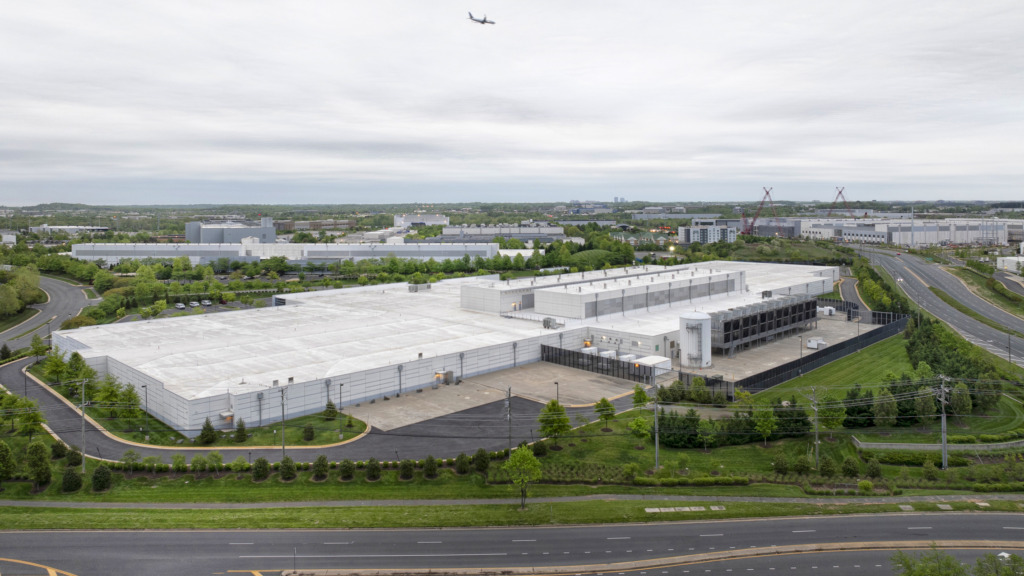
  • The designation process will help determine where new OZ-supported investment can occur beginning in 2027. While the original program attracted significant multifamily investment, developers are now pursuing designations for a broader range of real estate projects, including mall redevelopments and data centers. (Bisnow, Sept. 15)

Data Center OZ Legislation
RER will continue working with Congress, Treasury, and the IRS to secure and improve  OZ rules to ensure the incentives support economic development and job growth, new sources of local tax revenue,  and expanded housing supply.
Tax Policy Roundup: Foreign Investment, Demolition Expenses, Data Centers, and Partnership Taxes

FIRPTA

The Real Estate Roundtable (RER) submitted recommendations this week aimed at removing barriers to foreign investment in US real estate and reforming the tax treatment of demolition costs, as lawmakers introduced data center tax legislation and a federal appeals court ruled on the self-employment tax treatment of limited partners.

FIRPTA: RER Requests Repeal of IRS Notice

  • This week, RER submitted a letter to Treasury Secretary Scott Bessent requesting revocation of IRS Notice 2007-55, citing its negative impact on foreign investment in U.S. commercial real estate. (Letter, Sept. 15)
  • The IRS Notice took the position that REIT distributions are not exempt from tax under the tax exemption for foreign governments (section 892). It also treats REIT liquidating distributions as sales of real property subject to tax under the Foreign Investment in Real Property Tax Act (FIRPTA).
  • The letter notes that nearly 20 years have passed without regulations implementing the Notice. Since that time, statutory changes to FIRPTA have eliminated much of its original rationale, and foreign capital’s importance to U.S. real estate investment and jobs has only increased. (Letter, Sept. 15)
  • RER contends that the Notice creates unnecessary transaction costs, limits investment flexibility, and discourages otherwise productive transactions. (Letter, Sept. 15)
  • “[S]ound legal reasoning, good governance, and favorable economic policy strongly support an administrative action to revoke Notice 2007-55,” wrote RER President and CEO Jeffrey DeBoer. “Repeal of the Notice would align squarely with the Administration’s stated priority of ‘unleashing prosperity through deregulation.’”

Property Redevelopment and Demolition Costs: Coalition Seeks Tax Reforms

  • On Wednesday, RER and 13 other national real estate organizations sent Congress a letter encouraging changes to the tax treatment of demolished buildings and demolition expenses.  (Letter, Sept. 15)
  • Current treatment: Section 280B generally requires both demolition expenses and a demolished building’s remaining tax basis to be added to the basis of nondepreciable land. Owners typically cannot recover those amounts for tax purposes until the land is sold, potentially years or decades later.
  • “This treatment can delay or deter redevelopment projects that would otherwise support increased housing supply and commercial activity, particularly in high-cost areas and downtown corridors facing elevated vacancy rates,” the 14 organizations wrote. (Letter, Sept. 15)
  • Proposed changes: The coalition recommends allowing taxpayers to deduct as a loss any remaining tax basis of a demolished building and allowing taxpayers to deduct the actual demolition expenses. The reforms should be paired with reasonable guardrails to protect historic buildings and ensure timely redevelopment of the property.

  • The issue was recently highlighted in an op-ed written by RER Tax Policy Advisory Committee Chairman Joshua Parker and published in The Hill. (The Hill, Aug. 30 | Roundtable Weekly, Sept. 11)
  • Future legislation in this area could also restore the deductibility of environmental remediation expenses.
  • The recently enacted, bipartisan ROAD to Housing Act removed many barriers to creating new housing. The organizations’ proposal would continue building on these efforts by promoting productive real estate investment.

Data Centers: House Democrats Propose Tax Restrictions

  • Reps. Kristen McDonald Rivet (D-MI) and Don Davis (D-NC) introduced the Reverse Big Ugly Tax Breaks for Data Centers Act on Sept. 16, seeking to exclude covered data centers from investment incentives expanded in the 2025 tax law. (Politico |  Rep. Rivet Press Release, Sept. 16)
  • The bill would deny 100% bonus depreciation and Opportunity Zone eligibility to covered data-center property. Its definition covers facilities exceeding 50 megawatts of maximum rated power capacity or total peak power load, including property dedicated to their operation. (Bill text)
  • The legislation follows an August white paper from Senate Finance Committee Ranking Member Ron Wyden (D-OR) addressing bonus depreciation, Opportunity Zones and REIT treatment for data centers, along with a proposed excise tax on operators. (Senate Finance proposal, Aug. 6 | Roundtable Weekly, Aug. 7)

Partnership Taxes: Second Circuit Rules in Soroban

  • The U.S. Court of Appeals for the Second Circuit on Sept. 17 affirmed the Tax Court’s decision in Soroban Capital Partners LP v. Commissioner, holding that three principals did not qualify for the limited partner exception from self-employment tax because they exercised managerial control over the firm. (Opinion, Sept. 17)
  • The court focused on the partners’ actual responsibilities, including managing investments, serving on governing committees, and directing personnel decisions. It clarified that partners may provide some services and still qualify for the exception if those activities do not involve controlling, managing or running the business. (Bloomberg Law, Sept. 17)
  • The opinion appears to align, at least in significant part, with the Fifth Circuit’s revised approach in K Alain, formerly Sirius Solutions. (Court Opinion | JD Supra, Aug. 12)
  • RER filed an amicus brief supporting the taxpayer in Soroban as part of its broader challenge to the IRS’s restrictive interpretation of the limited partner exception from self-employment tax. RER also filed briefs supporting taxpayers in Sirius Solutions in the Fifth Circuit and Denham Capital in the First Circuit. (Roundtable Weekly, Jan. 30 | Feb. 13 | Sept. 11)

RER will continue working with Congress, Treasury and the IRS to advance tax policies that expand access to capital, encourage redevelopment and support long-term economic growth.

Tax Policy Roundup: Community Revitalization, Opportunity Zones, Foreign Investment, and Judicial Developments

As Congress returns to Washington, The Real Estate Roundtable (RER) is working to advance several tax policy initiatives aimed at expanding housing supply, revitalizing communities, and removing barriers to capital formation for real estate investment.

Tax Policies to Support Community Revitalization

  • On August 30, RER’s Tax Policy Advisory Committee (TPAC) Chairman Joshua Parker published an op-ed in The Hill newspaper setting forth a three-part framework for how lawmakers should think about potential tax policies to support community revitalization. (The Hill, Aug. 30)
  • “Preserve buildings that can serve again,” wrote Parker. “Convert those that can meet a new need. Clear those that cannot and require the land to be rebuilt.”
  • Parker’s op-ed outlines three actionable tax changes advocated by RER to advance this framework: (1) reforming the tax treatment of demolition costs, including the lost tax basis when a building is torn down; (2) strengthening the historic tax credit, and (3) incentivizing commercial-to-residential conversions through the bipartisan Revitalizing Downtowns and Main Streets Act (H.R. 2410).

Opportunity Zones

  • RER is continuing to encourage Treasury and the IRS to move forward with transitional tax guidance that will provide much-needed clarity to Opportunity Zone (OZ) investors pursuing new housing and other real estate projects that straddle the pre- and post-2025 OZ statutory regimes.
  • IRS Notice 2026-40, released in June, embraced several RER recommendations and clarified certain key issues for taxpayers with OZ projects in expiring census tracts. (Roundtable Weekly, June 26)
  • RER followed up the Notice with additional suggestions, and met virtually with Treasury and IRS staff, along with other stakeholders, on Aug. 27. Formal proposed regulations from Treasury are expected before the end of the year. (Letter, July 29 | Roundtable Weekly, July 31)
  • This week, Treasury and the IRS issued proposed regulations implementing new reporting requirements for Qualified Opportunity Funds and Qualified Opportunity Zone Businesses. (PoliticoPro, Sept. 10)

FIRPTA and Tax Barriers to Foreign Investment in US Real Estate

FIRPTA
  • RER is finalizing a request to Treasury to revoke outdated administrative guidance (IRS Notice 2007-55) that creates unnecessary hurdles and tax burdens for foreign investors seeking to deploy capital in US real estate.
  • Notice 2007-55 treats REIT liquidating distributions as a sale of real property rather than the sale of stock, thus subjecting the transactions to tax under FIRPTA. The Notice also treats REIT distributions as ineligible for the section 892 foreign government tax exemption.
  • RER believes the Notice’s conclusions were incorrect at the time, and more recent events strongly favor its repeal.
  • These include changes in the FIRPTA statute since the Notice was issued, growth in the importance of foreign capital to U.S. real estate jobs and investment, and the corrosive effect of 20 year-old sub-regulatory guidance that has never been subject to the formal rulemaking process.

SECA Limited Partner Exception

  • On Aug. 12, the Fifth Circuit withdrew its January opinion in Sirius Solutions and issued a substitute opinion holding that the self-employment tax exception applies to a limited partner who plays “no significant role in managing or running a business.” (JD Supra, Sept. 9)
  • The new standard is a step back from the court’s earlier ruling, which based eligibility on limited liability and state-law limited partner status. However, the court again rejected the Tax Court’s stricter “passive investor” test and remanded the case for further consideration. (Grant Thornton, Aug. 17)
  • RER has filed amicus briefs supporting taxpayers in Sirius and two related appeals—Denham Capital in the First Circuit and Soroban Capital Partners in the Second Circuit. (Roundtable Weekly, Jan. 30 | Feb. 13)

RER will continue engaging with Congress, Treasury, and the IRS to advocate for clear, effective tax rules that expand access to capital, encourage investment and redevelopment, and support long-term economic growth.

Roundtable Submits Recommendations to Further Improve New Opportunity Zone Transition Relief

The Real Estate Roundtable (RER) submitted comments this week on IRS Notice 2026-40, welcoming the guidance as an important step in the transition from Opportunity Zones (OZ) 1.0  (TCJA) to the permanent OZ framework enacted under the One Big Beautiful Bill (OB3) Act. RER urged the Treasury Department and IRS to clarify the Notice’s Written Plan and Ordinary Course safe harbors for multiphase investments and allow opportunity funds to continue investing in OZ 1.0 census tracts through their statutory expiration on Dec. 31, 2028. (Letter, July 29)

OZ Transition Recommendations

  • The Notice incorporated several concepts previously recommended by RER and has helped unlock capital that had been delayed by uncertainty surrounding investments in expiring OZ 1.0 census tracts. (Roundtable Weekly, June 26)
  • Post-2026 investments in OZ 1.0 census tracts must comply with either (1) the “Written Plan” exception, which requires compliance with the existing working capital safe harbor rules and related funding requirements; or (2) the “Ordinary Course” exception, which relates to the purposes of the expenditures (e.g., the permissible modernization or continued operations of the trade or business, as opposed to impermissible expansion of the business or starting a new trade or business).
  • RER’s July 29 comments urged Treasury to make both exceptions clear and workable for real estate investors, developers, and entrepreneurs undertaking long-term and multiphase projects. (Letter, July 29)
  • Additional clarifications would provide helpful certainty, reduce regulatory risk, and further unlock capital for greater investment in low-income communities. (Letter, July 29)
  • Under the Written Plan exception, RER asked Treasury to confirm that capital provided after 2026 does not need to come from the same Qualified Opportunity Fund (QOF) that financed the project earlier and that subsequent phases of an existing real estate business may qualify. (Letter, July 29)
  • For the Ordinary Course exception, RER requested administrable rules distinguishing permissible upgrades—such as energy-efficiency measures, accessibility improvements and interior reconfigurations—from business expansions. The letter also seeks clarity for projects involving new floors, conversions of existing space, parking structures, and other improvements that may fall between those categories.
  • RER also asked Treasury to allow new QOF equity to fund qualifying ordinary-course improvements, rather than requiring projects to rely on debt, existing cash, or non-QOF equity.
  • RER further encouraged Treasury to allow QOFs in OZ 1.0 census tracts to continue investing and acquiring property outside the two exceptions through the tracts’ statutory expiration on Dec. 31, 2028—two years longer than contemplated by the Notice. (Letter, July 29)

RER Advocacy

  • RER has consistently urged Treasury and the IRS to provide workable transition rules for OZ 1.0 projects, including through a December 2025 letter, follow-up comments and draft guidance submitted by RER’s Opportunity Zone Working Group in March 2026, and meetings with agency officials. (Roundtable Weekly, March 6) (Roundtable Weekly, Dec. 2025)

RER’s Opportunity Zone Working Group will continue engaging with Treasury and the IRS to support clear, workable implementation of the permanent OZ framework.

IRS Issues Long-Awaited Transition Guidance for Opportunity Zones

The Treasury Department and IRS issued new guidance last week, IRS Notice 2026-40, providing transition rules for Opportunity Zone investments made or initiated under the original OZ 1.0 regime.

The notice previews rules Treasury and IRS intend to include in forthcoming regulations. It focuses on new OZ designations going forward, transition rules for investors with existing deferred gains, and transition rules for Qualified Opportunity Funds (QOFs) and Qualified Opportunity Zone Businesses (QOZBs) operating in OZs designated under the prior law. (Tax Notes, June 18 | Reuters, June 22)

Why It Matters

  • The guidance is a major development for Opportunity Funds and OZ businesses with projects in OZ 1.0 census tracts as the program transitions to the new permanent OZ framework under the One Big Beautiful Bill (OB3)Act.
  • While the OB3 Act permanently extended and improved the OZ tax incentives, it left unresolved tax questions affecting investments in expiring OZ 1.0 tracts, including how far along a project must be before a census tract expires and whether future capital expenditures can continue to qualify for the tax incentives.

The Notice

  • Under the notice, property acquired after Dec. 31, 2026, in a previously designated OZ may still qualify if certain conditions are met. (Seyfarth, June 23)
  • To qualify, the OZ business must have a written working capital plan in place by Dec. 31, 2026; future property acquisitions must be consistent with that plan; the business must receive at least 10% of its estimated working capital assets by year-end; and it must expend at least 5% of those assets by Dec. 31, 2026. (IRS Notice 2026-40, June 18)
  • The notice also clarifies how OZ compliance tests apply after an OZ 1.0 census tract expires. In certain cases, a previously designated OZ can continue to be treated as a qualifying zone for purposes of the “substantial use” test and the requirement that at least 50% of a business’s gross income be derived from the active conduct of a trade or business in a qualified OZ. (IRS Notice 2026-40, June 18 | Reuters, June 22)
  • The guidance provides important certainty for real estate investors, developers, and businesses seeking to move forward with projects in low-income communities during the transition from OZ 1.0 to the new permanent OZ framework.

RER Advocacy

  • RER emphasized that unresolved questions surrounding expiring census tract designations could delay projects, discourage new fund formation, and undermine housing production and community development efforts.
  • While the notice includes many important details that remain under review, its issuance marks a major step forward in providing greater certainty for long-term OZ investment in underserved communities.

RER’s Opportunity Zone Working Group will review the implications of Notice 2026-40 in the days ahead and continue to engage with Treasury and the IRS to support clear, workable implementation of the new OZ framework.

Treasury Extends Tax Relief to Foreign Governmental Investors in U.S. Real Estate

The U.S. Department of the Treasury and Internal Revenue Service (IRS) took a positive step last Friday in response to The Real Estate Roundtable (RER) and other stakeholder concerns, partially withdrawing and modifying proposed regulations on the taxation of sovereign wealth funds and other foreign governmental investors. (Treasury Press Release, May 29)

Why It Matters

  • Foreign investment, including investment by sovereign wealth funds, foreign pension funds, and other government entities, is a critical source of financing for capital-intensive U.S. real estate projects.
  • Section 892 of the tax code generally exempts from U.S. tax certain dividends, interest, and gains earned by foreign governments, unless the income is treated as commercial activity income or income from a controlled commercial entity. Foreign investors rely heavily on Section 892 when planning and structuring U.S. real estate investments.
  • In December, Treasury issued proposed regulations addressing two key questions under Section 892: (1) when a foreign government has effective control of an entity engaged in commercial activities, and (2) when an acquisition of debt is considered commercial activity. (Tax Notes, June 1)
  • The new regulations published on June 1 would ensure that existing foreign government investments, as well as investments acquired during a transition period, are not subject to the more stringent standards in the 2025 proposed rules. (Skadden, May 29)
  • As Treasury and the IRS continue to evaluate the underlying substantive issues, this most recent action ensures that the new rules will not retroactively increase the tax burden on existing real estate investments or have a chilling effect on foreign real estate investments currently under consideration.

RER Advocacy

  • In February, RER submitted comments urging Treasury to avoid imposing a retroactive new tax on existing investments and recommended clear grandfathering and transition rules as part of any final Section 892 regulations. The new Treasury proposal is a positive step that directly addresses those concerns. (Letter | Roundtable Weekly, Feb. 13 | Feb. 27)
  • RER also provided detailed comments on the underlying section 892 issues, urging Treasury to clarify that customary minority investor protections do not create effective control, confirming withholding agents may rely on foreign government self-certifications, and establishing safe harbors for certain debt-related situations. (Roundtable Weekly, Feb. 27)
  • In March, TPAC Chair Joshua Parker (Founder, Chairman and CEO, Ancora) reinforced RER’s concerns in a Bloomberg Tax op-ed urging Treasury to modernize Section 892 rules without discouraging sovereign investment in U.S. real estate and other long-term assets. (Roundtable Weekly, March 13)

What’s Next

  • Treasury Secretary Scott Bessent said the new guidance provides certainty for current investments and transition relief for sovereign investors, while Treasury continues to evaluate feedback to “uphold established market practices” and maintain a stable environment for sovereign wealth fund investment. (Treasury Press Release, May 29)
  • Treasury has not yet modified the substantive provisions related to effective control, commercial activity, and acquisitions of debt.
  • RER will continue working with Treasury and IRS to ensure final Section 892 rules preserve foreign government capital flows into U.S. real estate while maintaining the statute’s distinction between tax-exempt investment activity and taxable commercial activity.

Section 892 regulations and other foreign investment tax policy issues will be discussed next week during RER’s Tax Policy Advisory Committee meeting on June 10.

IRS and Treasury Issue Guidance on Opportunity Zone Nominations

The IRS and Treasury Department released new guidance Monday outlining the process for states to nominate census tracts for designation as Qualified Opportunity Zones (QOZs) under the expanded, permanent program enacted in the One Big Beautiful Bill (OB3) Act. (Treasury News Release, April 8)

Proposed Guidance

  • Treasury and IRS released new guidance establishing the process for chief executive officers of any state, the District of Columbia, and U.S. territories to nominate eligible low-income census tracts for QOZ designation, as well as a list of 25,332 census tracts that meet the low-income requirements. (Treasury dataset | Politico Pro, April 6)
  • The guidance is a step toward implementing the Opportunity Zone (OZ) changes enacted in the OB3 Act, which made the incentive permanent and expanded it to provide enhanced tax benefits for investments in rural OZs. Rural OZs have lower investment requirements than urban tracts. (IRS News Release, April 6 | Politico Pro, April 6)
  • Under the statute, states generally may designate no more than 25 percent of their eligible low-income communities as QOZs, subject to special rules for states with fewer qualifying tracts. (IRS News Release, April 6)
  • The new designations will take effect on Jan. 1, 2027, and future designation rounds will occur every 10 years, replacing the original one-time map established under the 2017 Tax Cuts and Jobs Act (TCJA). (IRS News Release, April 6)
  • Treasury is developing an online nomination tool to streamline the designation process. (Bloomberg, April 6)

Roundtable Advocacy

  • Following the passage of the OB3 Act, RER actively engaged Treasury and IRS to support a smooth transition from OZs 1.0 to 2.0, including submitting a detailed comment letter and providing draft guidance for consideration. (Letter, Dec. 19)
  • RER’s December 2025 comment letter requested urgent tax guidance to ensure investment and capital continue to flow to low-income communities during the transition from the TCJA OZ regime to the new OB3 Act rules. (Letter, Dec. 19)
  • RER urged policymakers to confirm that contributions to existing TCJA qualified opportunity funds and businesses would continue to qualify for OZ benefits after current zone designations lapse, provided certain conditions are met. (Letter, Dec. 19)
  • Without clear transition rules, investors could delay or redirect capital, creating unnecessary uncertainty and slowing affordable housing development and economic activity in distressed communities. (Letter, Dec. 19)
  • OZ incentives have already mobilized more than $120 billion in capital to support housing, retail, and mixed-use development in underserved areas. (Letter, Dec. 19)

What’s Next

  • The QOZs nomination window opens on July 1, 2026 and runs for 90 days, subject to a single 30-day extension. (IRS News Release, April 6)
  • Treasury and IRS expect to issue additional guidance identifying designated QOZs before the Jan. 1, 2027 effective date. (IRS News Release, April 6)
  • New OZ designations will run through Dec. 31, 2036, with new nomination rounds occurring every 10 years thereafter. (IRS News Release, April 6)

RER will continue to engage with policymakers to support clear, workable implementation of the new OZ framework, ensure continuity for existing projects, and encourage tax policies that incentivize long-term investment in underserved communities.

Cost Recovery Reform to Spur New Housing Supply Gains Traction in Washington

A new report from the influential Center for American Progress (CAP) suggests that allowing immediate expensing for new multifamily rental housing could spur a major increase in multifamily construction and bring down housing costs over the next decade. (CAP Report, March 11)

Report Findings

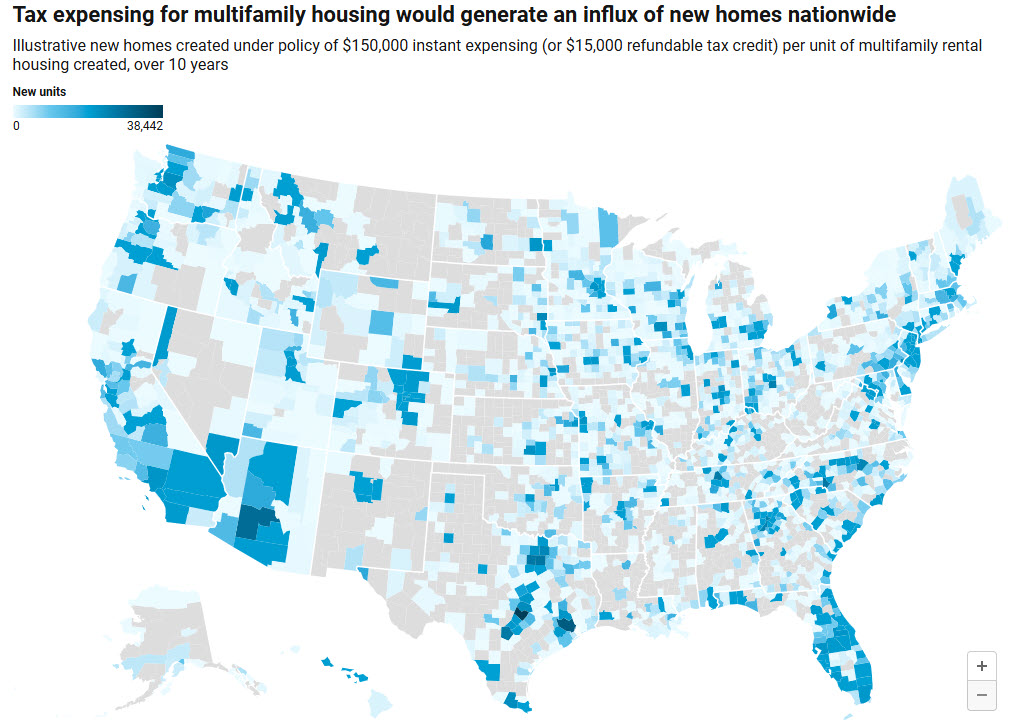
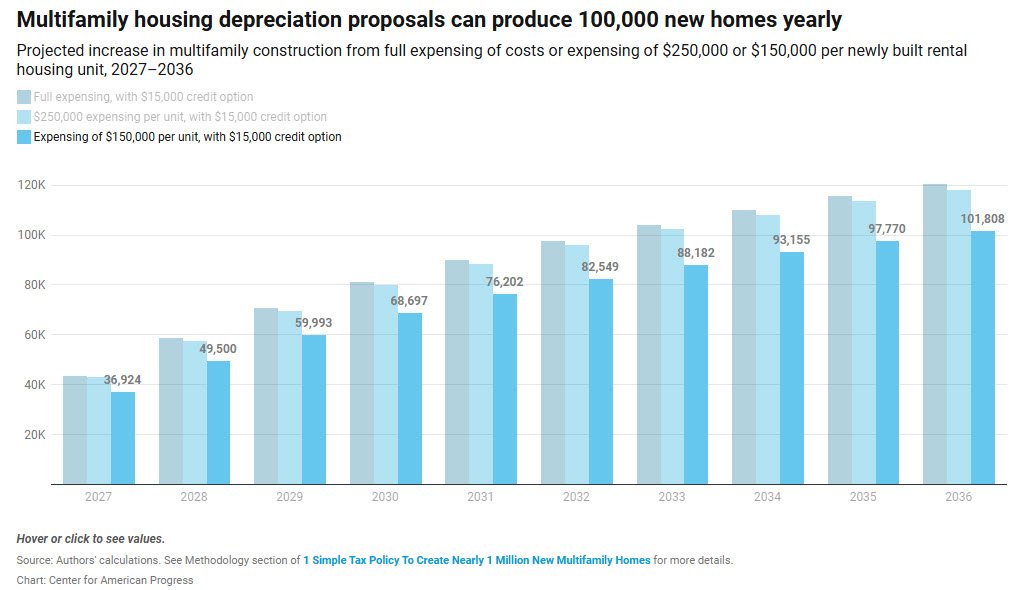
  • The CAP report found that immediate expensing for new multifamily rental housing, with a per-unit cap of $150K-$250K, could spur the creation of 706,000 to 1.06 million new homes over 10 years, at a cost of up to $206 billion. (PoliticoPro, March 12)
  • The researchers claim that faster cost recovery would lower the cost of capital, improve project cash flow, and help move more rental developments from infeasible to financeable.
  • The research also shows that full or partial expensing could increase housing supply at a lower cost per unit than many direct subsidy programs. (Tax Policy Center, March 17)
  • The researchers’ preferred approach would cap immediate expensing at $150,000 per unit, paired with a refundable credit option to address the fact that many real estate investors are tax-exempt or otherwise unable to use additional tax deductions. They estimate the proposal could produce roughly 755,000 new homes over a decade for about $154 billion.
  • The proposal also parallels last year’s One Big Beautiful Bill Act, which provided full expensing for new factories. The Tax Foundation called that change a step forward, but said its economic benefits would be limited because it is temporary and narrowly targeted. (Tax Foundation, Oct. 27, 2025)
  • The Tax Foundation published a reply to the CAP report that generally supports the approach while outlining a variety of cost recovery reform options for policymakers to consider, including: neutral cost recovery, and investment tax credit, tax deduction transferability, shorter asset lives, and partial expensing. (The Tax Foundation, Mar. 23)
  • The recent reports by the two influential think tanks are further evidence that policymakers are open to new approaches aimed at addressing housing affordability challenges.

On the Hill

  • Sen. Lisa Blunt Rochester (D-DE) introduced the Rental Housing Investment Act on March 12, which would allow builders to immediately deduct a portion of new multifamily construction costs rather than recover them over 27.5 years. (Sen. Rochester News Release, Mar. 12)
  • The bill would allow builders to immediately deduct up to $150,000 per unit in construction costs, with an enhanced deduction of up to $250,000 per unit for projects that include income-restricted units under long-term attainability commitments. The incentive would apply only to newly constructed multifamily rental housing. (USA Today, Mar. 11)
  • The measure is intended to support efforts to expand rental supply and address affordability pressures by improving the tax treatment of new multifamily development, as high interest rates and rising construction costs continue to weigh on housing production.

Property Conversions

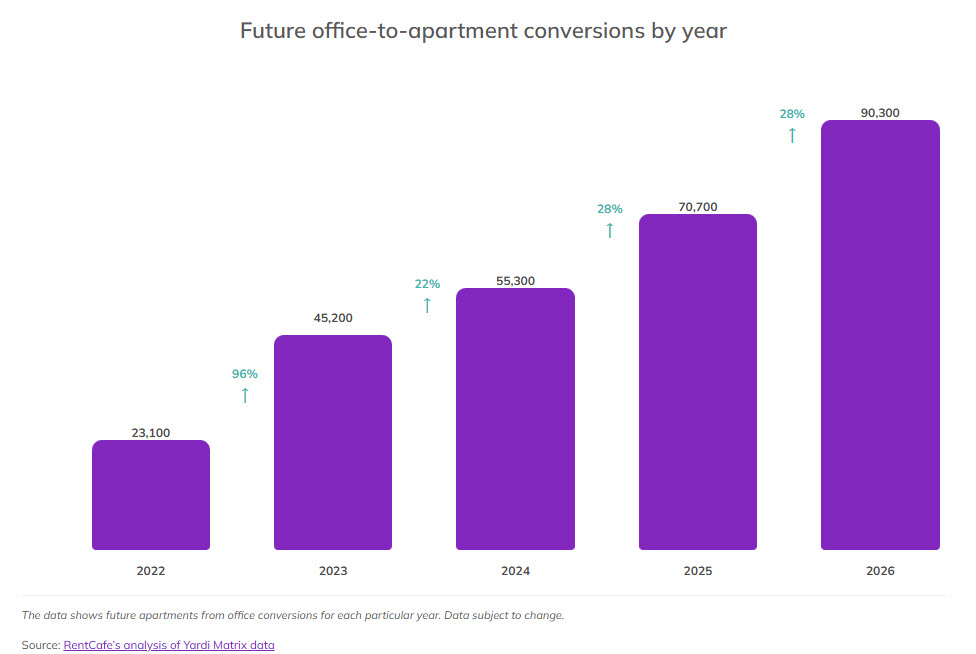
  • Office conversions now account for nearly half of all future adaptive reuse projects. (CRE Daily, Mar. 25)
  • RentCafe reported that 90,300 apartments were in the conversion pipeline nationwide at the start of 2026, up 28% from 70,600 a year earlier, as the trend continues to gain momentum in both major and mid-sized markets. (RentCafe, Mar. 24)
  • New York leads the pipeline, followed by Washington, D.C., and Chicago. (Bisnow, March 26 | Cushman & Wakefield, Feb. 2026)
  • New research from Pew and Gensler highlights office-to-residential conversions, particularly lower-cost co-living microapartments in underused downtown buildings.  (Pew Research, Mar. 24)
  • Pew found the model could cut per-unit development costs by more than half in some markets and deliver nearly four times as many affordable homes per subsidy dollar compared to traditional studio development. (Pew Research, Mar. 24)
  • RER has strongly backed the bipartisan Revitalizing Downtowns and Main Streets Act of 2025 (H.R. 2410), which would create a market-based tax incentive for converting older commercial buildings to residential use to help expand housing and support the recovery of downtowns and neighborhoods still feeling the effects of the pandemic. (Roundtable Weekly, Mar. 2025)

RER will continue working with policymakers to advance tax and regulatory policies that encourage property conversions, reduce barriers to development, and help expand the nation’s housing supply.

IRS Relief Expands Real Estate’s Access to Bonus Depreciation Tax Benefit

IRS building in Washington, DC

The IRS and Treasury Department this week issued new guidance allowing real estate companies to withdraw prior elections that had prevented many from fully benefiting from the One Big Beautiful Bill Act’s (OB3 Act) restored 100% bonus depreciation provision. Revenue Procedure 2026-17 outlines how taxpayers may revoke those elections under Section 163(j), clearing the way for broader use of immediate expensing across commercial real estate. (Bloomberg, March 18)

Why It Matters

  • The Real Estate Roundtable (RER) has urged Treasury to allow real estate owners who previously elected out of strict limitations on the deductibility of business interest to withdraw or amend those elections. This would enable them to fully benefit from the OB3 Act’s restored bonus depreciation benefit. (Roundtable Weekly, Feb. 6)
  • Under the Tax Cuts and Jobs Act of 2017 (TCJA), an electing real property trade or business (RPTOB) is exempt from the Section 163(j) limit on business interest deductibility, but must use the alternative depreciation system to recover the cost of its investment. As a result, electing RPTOBs are ineligible for bonus depreciation on leasehold and nonresidential interior property improvements.
  • Beginning in 2022, the Section 163(j) business interest limitation tightened, and starting in 2023, bonus depreciation began to phase out. Those two changes led many real estate owners to make the RPTOB election.
  • The OB3 Act reversed both provisions by restoring the original TCJA parameters for Section 163(j) and permanently extending 100% bonus depreciation. While that was a major positive development for new real estate investment, it left existing property owners locked into irrevocable RPTOB elections made under prior law.
  • Revenue Procedure 2026-17 addresses that problem by allowing taxpayers to retroactively withdraw an RPTOB election for taxable years 2022, 2023, or 2024. If a real estate owner withdraws the election under the revenue procedure, the owner is treated as if the election had never been made.
  • This change makes 100% bonus depreciation available to a much larger share of U.S. commercial real estate, ensures that property owners are not penalized for elections made under a tax regime that no longer applies, and should support additional capital formation.
  • The revenue procedure also provides guidance on the administrative steps for withdrawing an election, partnership filing requirements, and procedures for amending returns for intervening years.

RER Advocacy

  • In an Oct. 17, 2025, letter, RER wrote to Treasury urging guidance allowing real estate businesses to amend or revoke prior RPTOB elections to ensure the OB3 Act’s restored 100 percent bonus depreciation provision supports real estate investment, job creation, and economic growth. (Roundtable Weekly, Feb. 6)
  • The letter emphasized that clear implementing rules will help bonus depreciation “facilitate the modernization and repurposing of real estate assets,” including underutilized offices, shopping centers, hotels, and mixed-use properties. (Roundtable Weekly, Oct. 17)

Treasury’s action addresses a key transition issue created by the new law. It helps ensure that restored bonus depreciation can work as intended across a broader share of commercial real estate investment.

In the News: Roundtable TPAC Chair Urges Treasury to Modernize Foreign Investment Tax Rules, Preserve U.S. Access to Foreign Capital

A new Bloomberg op-ed by RER Tax Policy Advisory Committee Chair Joshua Parker (Founder, Chairman and Chief Executive Officer, Ancora) reinforces The Real Estate Roundtable’s (RER) push for Treasury to modernize Section 892 regulations without discouraging sovereign investment in U.S. real estate and other long-term assets. (Bloomberg Tax, March 11)

Op-Ed Highlights

RER Tax Policy Advisory Committee Chair Joshua Parker
  • Section 892 of the tax code generally exempts investment income earned by foreign governments, including sovereign wealth funds, from U.S. income tax. The 892 exemption does not apply, however, if the foreign government effectively controls the U.S. business or is deemed to be engaged in a commercial activity.
  • Parker writes that Treasury’s regulatory effort is “constructive and necessary,” but cautions that the rules must distinguish between legitimate investor stewardship and effective control of a business. (Bloomberg Tax, March 11)
  • The op-ed argues that Section 892 needs to catch up with major changes in capital markets, including the growth of private credit, direct lending, and co-investment strategies that were not significant features of the market when the statute was enacted.
  • Parker emphasizes that policymakers should not “sweep fundamentally different forms of investor participation into the same regulatory framework.
  • Responsible investors “must exercise fiduciary oversight, manage risk, and ensure disciplined capital deployment,” Parker adds. Customary minority protections such as consent rights, veto rights, and approval of extraordinary actions are forms of stewardship, not day-to-day business control.

Why It Matters

  • Since 2011, foreign governmental investors have invested more than $100 billion in U.S. commercial real estate. (Roundtable Weekly, Feb. 13)
  • Foreign capital invested in the U.S. has supported housing supply, infrastructure development, research facilities, and place-based economic growth. (Bloomberg Tax, March 11| RER Letter, Feb. 12)

RER Advocacy

  • In February, RER submitted a comment letter to Treasury Secretary Scott Bessent on the Section 892 regulations and proposed rules, urging clear grandfathering rules and changes to prevent disruptions to sovereign investment in U.S. real estate. (Letter, Feb. 12 | Roundtable Weekly, Feb. 27)

RER will continue engaging Treasury to ensure the final rules provide clarity for investors while avoiding unintended disruptions to U.S. real estate capital formation.