Fed Holds Rates Steady as Inflation Concerns Persist

The Federal Reserve held its benchmark interest rate steady at 3.75–4 percent on Wednesday, pausing after September’s quarter-point increase as policymakers assess persistent inflation and economic conditions. Two officials dissented in favor of another rate hike, underscoring continued pressure to tighten monetary policy. (Federal Reserve, Oct. 28 | The Wall Street Journal, Oct. 29)

State of Play

  • The Federal Open Market Committee (FOMC) voted 10–2 to maintain the current target range, with Federal Reserve Governor Lisa Cook and Cleveland Fed President Beth Hammack favoring a 25-basis-point increase. The decision follows September’s unanimous vote to raise rates for the first time since 2023. (Federal Reserve, Oct. 28 | Federal Reserve, Sept. 16)
  • The Fed characterized economic activity as “expanding at a strong pace,” supported by resilient consumer spending, strong productivity growth, and robust capital investment.
  • Inflation remains elevated, and policymakers emphasized the importance of additional economic data in determining the appropriate policy stance. (Federal Reserve, Oct. 28)
  • The October decision leaves open the possibility of another rate increase before year-end as the Fed continues working toward its 2 percent inflation target. (Federal Reserve)

Why It Matters

  • Elevated interest rates continue to weigh on commercial real estate (CRE) borrowing costs, refinancing activity, and investment. Continued inflation pressures and elevated Treasury yields can increase financing costs for property owners and developers.
  • Nearly $983 billion in U.S. CRE mortgages are estimated to mature in 2027, underscoring the importance of accessible financing as borrowers face higher debt service costs and potentially more challenging refinancing conditions. (RER Policy Priorities, Capital & Credit)
  • The rapid buildout of artificial intelligence (AI) data centers is adding complexity to the Fed’s inflation outlook. Data center investment is supporting economic growth while straining electricity supply and construction capacity. (Politico, Oct. 28)
  • Higher rates could weigh on housing and other interest-sensitive sectors without substantially slowing spending by well-capitalized technology companies. (Politico, Oct. 28)

The FOMC’s final scheduled policy meeting of 2026 will take place Dec. 8–9, when officials will release an updated Summary of Economic Projections.

Fed Beige Book Highlights Mixed CRE Conditions and Continued Financing Pressures

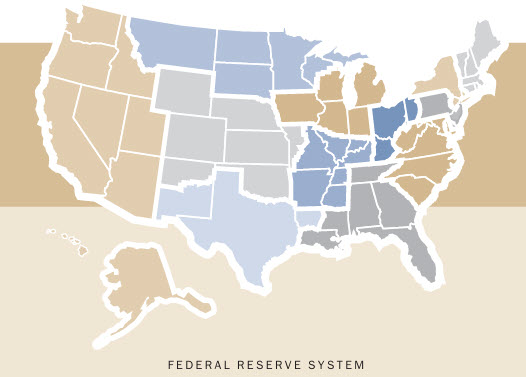
The Federal Reserve’s October Beige Book, released Oct. 14, found that economic activity grew slightly or modestly across most districts, while commercial real estate conditions varied by region. Higher borrowing costs, tighter credit conditions, and rising construction expenses continued to weigh on investment and development. (Beige Book, Oct. 14 | GlobeSt., Oct. 16)

Regional CRE Trends

  • New York: Commercial property sales slowed as rising interest rates reduced demand, despite strong Manhattan office leasing and industrial demand driven by data centers. Banks reported slightly tighter credit standards for commercial mortgages, with concerns over interest rate exposure and refinancing costs. (New York Fed)
  • Chicago: Construction and real estate activity declined slightly, although commercial real estate activity remained unchanged overall. Financial conditions tightened modestly, while major development projects competed for construction capacity and electrical equipment needed for data centers. (Chicago Fed)
  • National Outlook: Nine of the 12 Federal Reserve districts reported slight to moderate economic growth, while three reported little change. Businesses continued to face higher costs from energy, tariffs, and insurance, along with shortages of specialized technical and skilled-trade workers. (Federal Reserve)

Why It Matters

  • Nationally, businesses continued to report higher input costs, including pressure from tariffs, insurance, and energy prices. Several districts also noted continued shortages of specialized technical and skilled-trade workers, which could affect construction costs and development timelines. (Federal Reserve, Oct. 14)
  • Financing pressures and rising development costs remain key challenges for CRE investment. Higher borrowing costs and tighter lending standards can complicate refinancing and property transactions, while labor shortages and competition for construction materials and infrastructure capacity can delay new projects. 

Roundtable on the Road

  • This week, RER President and CEO Jeffrey DeBoer joined Kristen Silverberg, Business Roundtable’s President and COO and incoming President and CEO, for a policy and business panel at Marriott International’s North America (MINA) Conference. The discussion focused on policy issues affecting the economy, job creation and investment.
  • The panel also addressed the upcoming elections and next year’s legislative outlook. DeBoer and Silverberg encouraged business leaders to engage with state and local officials, noting that nearly 50 members of Congress previously served as mayors or governors.

RER will release its Q4 2026 Sentiment Index Report in the coming weeks, providing an updated assessment of commercial real estate executives’ views on market conditions, capital availability, and the outlook for the industry.

Fed Raises Rates for the First Time Since 2023

The Federal Reserve raised its benchmark interest rate by a quarter point on Wednesday to a target range of 3.75-4 percent, its first increase since 2023. The Federal Open Market Committee (FOMC) voted unanimously, a sharp turn from July when three officials dissented in favor of a hike. (Cushman & Wakefield, Sept. 17)

Fed’s Decision

  • The FOMC voted 12-0 to raise the target range by 25 basis points, citing economic activity expanding at a solid pace, resilient domestic spending, strong productivity growth, robust capital investment, and job gains keeping pace with the workforce. (Federal Reserve | Implementation Note, Sept. 16)
  • Chair Warsh said this summer’s readings do not show underlying inflation trends meaningfully improving, putting 12-month total PCE inflation at roughly 3.6 percent in August, with too many categories still running above 3 percent. (Opening Statement, Sept. 16)
  • Repeating a point from Jackson Hole, Warsh said he would be “hard-pressed to describe broad financial conditions as restrictive,” a view he said the Committee widely shared. (Opening Statement, Sept. 16)
  • The Summary of Economic Projections put median real GDP growth at 2.3 percent this year, total PCE inflation at 3.7 percent falling to 2.3 percent next year, and unemployment steady near 4.1 percent. (Projections | Opening Statement, Sept. 16)

Housing and CRE Outlook

  • The 10-year Treasury breached 5 percent on Sept. 15, and the 30-year topped 5.4 percent, both the highest since 2007. Most permanent commercial mortgages price off Treasury benchmarks rather than the federal funds rate. (Scotsman Guide, Sept. 16)
  • Lenders report that higher debt service costs are reducing loan proceeds and widening the gap between buyers and sellers, requiring sponsors to contribute more equity. Deal structures are adapting, with more cash-in refinancings, recapitalizations, and loan sales as lenders grow less willing to extend. (Commercial Observer, Sept. 16)

What to Watch

  • The FOMC next meets Oct. 27-28, followed by Dec. 8-9. With the median projection pointing to one more increase this year, attention will remain on both meetings for signs of when the Fed could make its next move. (Federal Reserve Calendar)
  • Nearly $983 billion of U.S. commercial real estate mortgages are estimated to mature in 2027. Sustained higher long-term yields would increase refinancing costs as those loans come due. (RER Policy Priorities, Capital & Credit)

RER will continue to advocate for policies that strengthen capital markets, preserve access to credit, and support the capital formation needed to drive long-term economic growth.

Fed Holds Rates Steady as Inflation Risks Persist

The Federal Reserve held its benchmark interest rate steady at 3.50-3.75 percent for a fifth consecutive meeting on Wednesday, with three officials dissenting in favor of a quarter-point hike. Chair Kevin Warsh said inflation remains above the Fed’s 2 percent target, partly reflecting energy-related supply shocks, and reaffirmed the Committee’s commitment to restoring price stability.

Fed’s Decision

  • The Federal Open Market Committee (FOMC) voted 9-3 to hold rates steady. Cleveland Fed President Beth Hammack, Minneapolis Fed President Neel Kashkari, and Dallas Fed President Lorie Logan preferred a 25-basis-point increase. It was the first time since 2016 that three officials dissented in favor of the same policy action. (Federal Reserve, July 29; CNN, July 29)
  • The policy statement was nearly unchanged from June, citing solid economic growth, strong productivity and investment, stable labor conditions and inflation that remains above the Fed’s 2 percent goal. (Federal Reserve, July 29; Opening Statement, July 29)
  • Chair Warsh said Treasury yields had risen materially since June, with some of the increases ranking among the largest of the past two decades. (Opening Statement, July 29; Watch Press Conference)
  • He described the Committee’s stance as “watchful thinking, not watchful waiting.” He said higher interest rates could be part of the solution if inflation remains elevated, while stopping short of signaling a specific September move. (Federal Reserve Calendar; Wall Street Journal Transcript, July 29)

Housing and CRE

  • The decision provides near-term stability in short-term rates, but many CRE financing costs remain tied to longer-term yields. The 10-year Treasury yield was about 4.66 percent Wednesday afternoon, while the average 30-year fixed mortgage rate was about 6.6 percent for the week ending July 23. (Wall Street Journal, July 29; USA Today, July 29)
  • Chair Warsh said AI-related investment is growing nearly 20 percent, a trend that could support continued demand for data centers and related infrastructure development.(Opening Statement, July 29)
  • Major banks are selectively returning to CRE lending. Bank of America, U.S. Bancorp, PNC and Truist reported year-over-year CRE loan growth ranging from more than 8 percent to about 25 percent, concentrated in multifamily housing, industrial, and data-center projects. While banks see attractive growth opportunities, office exposure continues to be approached cautiously. (Wall Street Journal, July 23)
  • The Fed’s next meeting on Sept. 15-16 will provide updated economic projections and a clearer indication of whether the growing internal divide is moving the Committee closer to a rate increase.

Policy Outlook

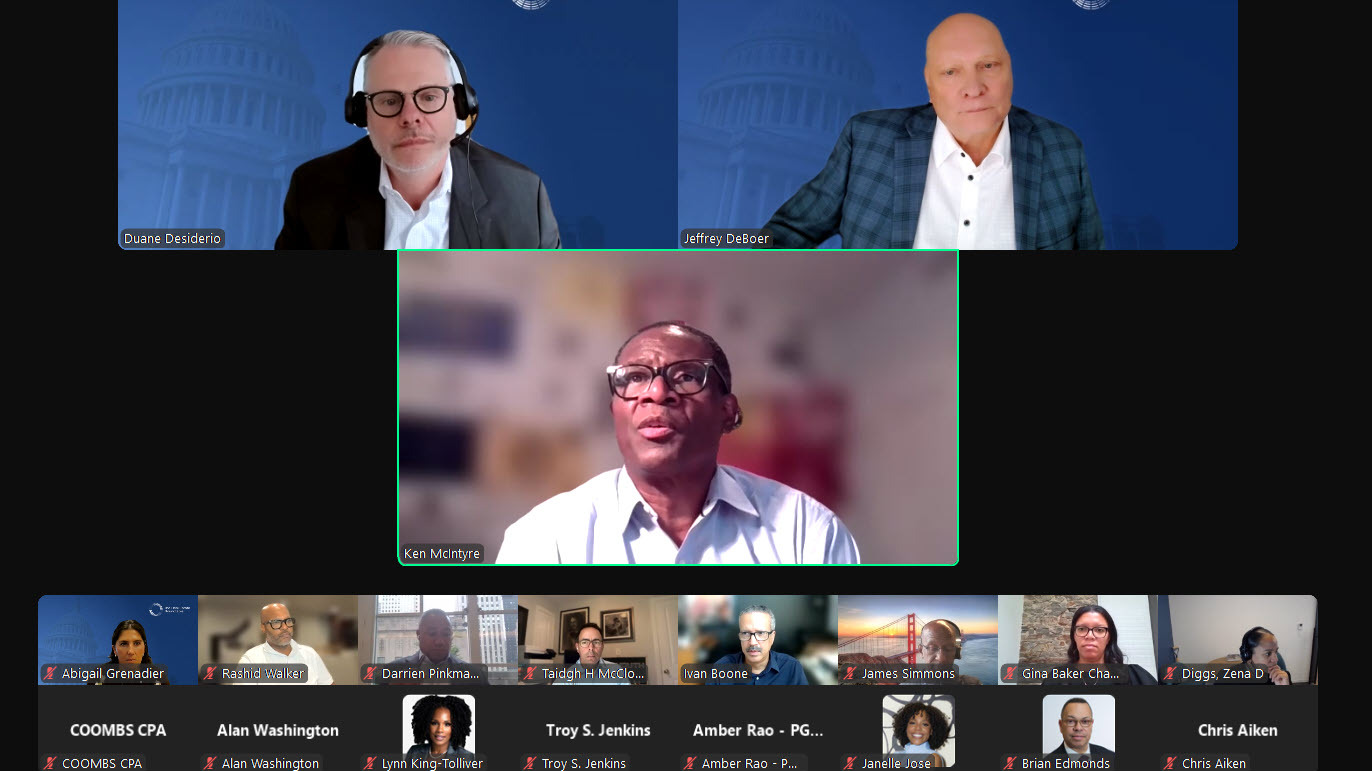
  • RER President and CEO Jeffrey DeBoer and SVP and Counsel Duane Desiderio joined Real Estate Executive Council (REEC) CEO Ken McIntyre for REEC’s monthly virtual town hall with members on the policy landscape in Washington, what CRE can expect in the coming months and RER’s advocacy priorities.

The discussion also covered housing affordability, electricity demand and emerging data center legislation, as well as RER’s efforts during negotiations over the 21st Century ROAD to Housing Act to remove the unconstitutional forced-sale provision that could have set a damaging precedent for other property types.

Fed Holds Rates Steady as Officials Split on Path Ahead

The Federal Reserve held its benchmark interest rate steady this week at a range of 3.50% to 3.75% for the third consecutive meeting, citing solid economic activity, low job gains, elevated inflation, and heightened uncertainty tied to developments in the Middle East. (FOMC Press Release, April 29)

The Fed’s Decision

  • The Federal Open Market Committee’s 8-4 vote exposed growing divisions within the central bank, with four dissents—the most at a Fed policy meeting since 1992. (Axios, April 29)
  • Governor Stephen Miran favored a 25-basis-point rate cut, while Cleveland Fed President Beth Hammack, Minneapolis Fed President Neel Kashkari, and Dallas Fed President Lorie Logan supported holding rates steady but objected to language they viewed as suggesting an easing bias.
  • Fed Chair Jerome Powell said there is “no rush” to signal the Fed’s next move as officials assess how the Iran war and higher energy prices affect inflation and growth. Developments over the next “30, 60 days,” he told reporters, could change the outlook before the Fed’s next meeting. (FOMC Press Release, April 29)
  • The split reflects a central tension facing the Fed: whether inflation risks warrant a more cautious posture—or whether slowing economic momentum strengthens the case for lower rates later this year. (Axios, April 30)

Why It Matters

  • For commercial real estate, the Fed’s cautious stance and internal divide add uncertainty around the timing of future rate cuts, keeping borrowing costs elevated and weighing on refinancing, transaction activity, asset valuations, and capital deployment.

What to Watch

  • The Senate Banking Committee advanced Kevin Warsh’s nomination to chair the Federal Reserve Board on Wednesday, putting him on track for possible Senate confirmation before the Fed’s next policy meeting in June. (PoliticoPro, April 29)
  • Chair Powell said that after his term as chair ends on May 15, he plans to continue serving as a Fed governor “for a period of time to be determined.” His Board term runs through 2028. (Barrons, April 30)

RER will continue to track monetary policy developments and engage policymakers on the need for stable capital markets, access to credit, and policy solutions that support long-term economic growth and real estate investment.

FSOC Hearing Highlights Nonbank Oversight as CRE Reacts to Fed Chair Nomination

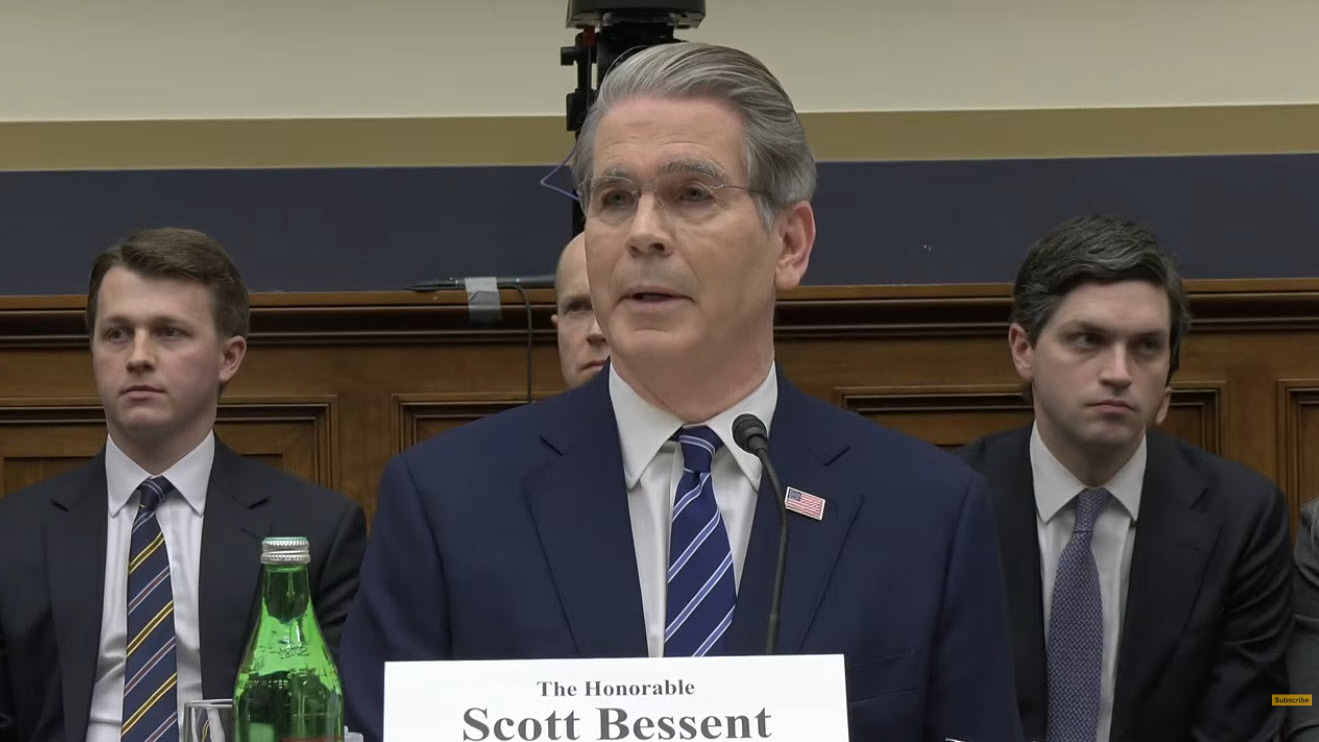
This week, the House Financial Services Committee (HFSC) and Senate Banking, Housing and Urban Affairs Committee held hearings with Treasury Secretary Scott Bessent to review the Financial Stability Oversight Council’s (FSOC) 2025 Annual Report. Lawmakers used the session to raise broader concerns about financial regulation, capital formation, and credit availability, including attention on FSOC’s role in banking regulation.

FSOC and Regulatory Direction

  • In his testimony, Sec. Bessent described a recalibrated approach at FSOC that focuses on identifying specific risky activities, rather than broadly regulating entire firms or sectors. He criticized prior “regulation by reflex” and stated that FSOC should avoid labeling wide swaths of the financial system as vulnerable, absent clear, material risk. (Watch Hearing)  
  • “FSOC should… work with its members to support efforts to avoid or pare back existing regulation that stifles pro-growth lending, capital formation, and innovation. And the best way to achieve these goals is by centering economic growth and economic security at the heart of FSOC’s agenda,” Sec. Bessent said. (Politico Pro, Feb. 4)
  • Several exchanges focused on FSOC’s authority to designate nonbank financial companies as Systemically Important Financial Institutions (SIFIs). Sec. Bessent confirmed a preference for an activities-based framework, signaling openness to clearer standards and restraint in the use of entity-based designations. (Watch Hearing)  
  • Sec. Bessent added that he would propose new nonbank guidance later this year, and that he supports higher deposit insurance to protect small banks’ competitiveness against larger institutions. (Politico Pro, Feb. 4)
  • He also supported HFSC Chairman French Hill’s (R-AR) community banking legislative package. He emphasized that small and community banks need tailored capital and risk standards to succeed. (American Banker, Feb. 4)
  • Democratic lawmakers warned that easing regulatory scrutiny could increase systemic risk and repeat conditions that preceded the 2008 financial crisis, with HFSC Ranking Member Maxine Waters (D-CA) arguing that FSOC should play a stronger role in identifying risks across the financial system, including among nonbank entities. (Watch Hearing)

Affordability and Tariffs

  • During the HFSC hearing, Ranking Member Waters pressed Sec. Bessent on whether the administration’s tariffs have contributed to persistent inflation. Sec. Bessent rejected that characterization and disputed claims that he had previously warned investors tariffs were inflationary. (American Banker, Feb. 4)
  • Ranking Member Waters also linked tariffs directly to worsening housing affordability, pointing to duties on key construction inputs such as lumber, steel, and appliances. (American Banker, Feb. 4)
  • While Democrats argued that tariffs and high prices continue to burden consumers, Sec. Bessent cited a Wharton study that points to immigration-driven demand as a contributing factor to higher housing costs. (CNBC, Feb. 4)

Roundtable Advocacy

  • The Real Estate Roundtable (RER) and coalition partners have supported the Financial Stability Oversight Council Improvement Act (H.R.3682), which would require FSOC to consult with a company and its primary regulator before designating a nonbank as a SIFI. (Letter, Oct. 28)
  • The bill is intended to strengthen due-process protections, improve interagency coordination, and ensure designations are based on rigorous analysis.
  • RER has consistently urged regulators to focus on activities that pose genuine systemic risk, rather than imposing broad designations that can create regulatory overreach and unintended consequences for credit markets. (Roundtable Weekly, Oct. 31)

CRE’s Reaction to Fed Chair Nomination

  • Last week, President Donald Trump announced his nomination of Kevin Warsh, a former Federal Reserve Governor, to succeed Fed Chair Jerome Powell. (Axios, Jan. 30)
  • As industry media outlets have reported, commercial real estate and finance leaders have broadly welcomed the nomination, citing Warsh’s experience from the financial crisis and his capital markets expertise. (Bisnow, Jan. 30)
  • “Kevin Warsh is a smart, thoughtful, and experienced nominee. His deep understanding of monetary policy and financial markets would help maintain and strengthen market confidence at a time when economic certainty matters most,” Jeffrey D. DeBoer, RER President and CEO, said.
  • Bob Broeksmit, President and CEO of the Mortgage Bankers Association, said in a statement that Warsh’s prior service on the Fed board gave him a reputation as “a prudent, thoughtful voice on monetary policy.”(ConnectCRE, Jan. 30)
  • CRE finance experts noted that while Warsh’s nomination could raise expectations for near-term rate cuts, uncertainty surrounding the confirmation process and Fed independence may keep long-term Treasury yields, as well as permanent financing costs, elevated. (ConnectCRE, Jan. 30)

RER remains committed to engaging policymakers on FSOC reform and related financial regulations to ensure oversight frameworks support capital formation, liquidity, and economic growth.

Fed Cuts Rates Again Amid Split Outlook; Hearing Targets Capital Rules

The Federal Reserve on Wednesday cut its benchmark interest rate by 25 basis points for the third straight meeting, lowering the federal funds target range to 3.50-3.75 percent. Fed Chair Jerome Powell emphasized that while policy is easing, the bar for additional reductions in early 2026 remains high.

Fed’s Decision

  • The Federal Open Market Committee (FOMC) vote was 9-3, with two policymakers preferring to hold rates steady and one seeking a deeper cut. (CNBC, Dec. 10)
  • Chair Powell said policy is “well positioned,” but stressed decisions are not on a preset path, citing mixed inflation signals and slowing but still resilient labor conditions. (Watch Press Conference)
  • The Chair noted that the latest projections show only one rate cut expected in 2026, signaling a potential pause in additional easing absent clearer labor and inflation trends.
  • Officials highlighted labor market softening as a key factor, with Chair Powell acknowledging it’s a “labor market that seems to have significant downside risks,“ even as inflation remains elevated.
  • He also expressed some optimism about growth, with the FOMC raising its outlook for 2026 GDP by half a percentage point, to 2.3 percent. (CNBC, Dec. 10)

Housing and CRE Outlook

  • Rate cuts alone won’t materially reprice CRE, as valuations and returns depend on multiple factors beyond monetary policy, and CRE has historically performed well even in higher-rate environments, industry analysts noted. (Connect CRE, Dec. 10)

  • Multifamily and industrial have already benefitted from the current rate environment, with multifamily development borrowing costs falling from 7.5-9 percent to ~6-7.25 percent and industrial cap rates expected to compress modestly. (Connect CRE, Dec. 10)

  • Commercial Mortgage-Backed Securities refinancing challenges remain acute, as lenders are unwilling to extend maturities without new borrower equity or substantive restructuring proposals. (Commercial Observer, Dec. 10)

Congressional Oversight & Capital Framework

  • At a House Financial Services Subcommittee hearing Thursday, witnesses largely urged regulators to calibrate the emerging Basel III Endgame proposal to support competitiveness, credit availability, and economic growth. (Watch Hearing)
  • Andrew Olmem (Partner, Mayer Brown) emphasized that capital decisions are policy choices: “Improperly calibrated requirements can reduce credit, raise borrowing costs, and slow wealth creation.”
  • GOP leaders on the subcommittee stressed the need for a tailored, data-driven framework that avoids the “gold-plated” standards identified by the Basel Committee.
  • Subcommittee Chair Andy Barr (R-KY) stated that the initial Basel III Endgame proposal was “deeply flawed” and pointed out that it has received bipartisan criticism. (Rep. Barr Press Release, Dec. 11)  

RER Advocacy

  • Thursday’s hearing was the latest in a series of recent steps policymakers have taken toward re-evaluating bank capital requirements.
  • Last week, RER and a coalition of leading business trade organizations encouraged prudential regulators to adopt requirements for large banks that support consumers, businesses, and the broader economy. (Roundtable Weekly, Dec. 5)

RER will continue to advocate policies that protect the safety and soundness of our financial system without harming credit flows and capital formation vital for CRE.   

Stabilizing Market Conditions Drive Optimism in Q3 Sentiment Index

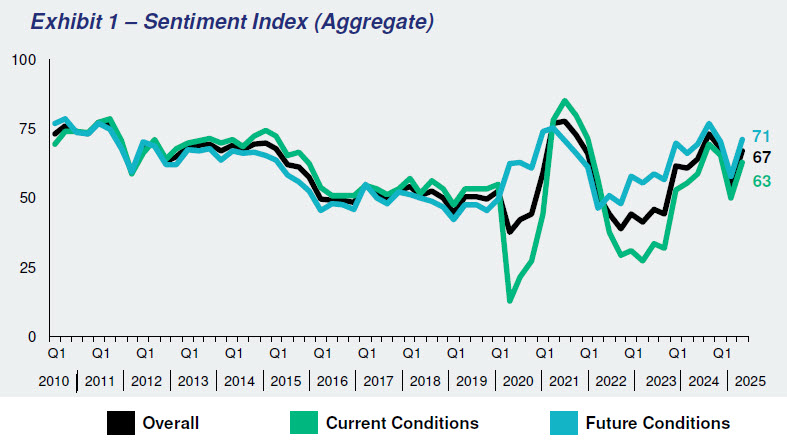
The Real Estate Roundtable’s Q3 2025 Sentiment Index shows increased confidence among industry executives as market conditions stabilize and sector-led growth emerges. The overall Index registered a score of 67—up 13 points from Q2—with notable increases in both the Current (63) and Future (71) indices. (Full Report)

Roundtable View

  • RER President and CEO Jeffrey DeBoer said, “Our Q3 Sentiment Index results show that market conditions have continued to stabilize in a meaningful way, supported by improved supply and demand. Commercial real estate executives are increasingly optimistic that the next 12 months will bring continued improvement. That said, certain property types continue to face headwinds, and capital access remains uneven across markets and sectors. Even so, the prevailing sentiment is that stability is returning and opportunities are emerging.” (Press Release, Aug. 14)
  • DeBoer added, “The provisions in the One Big Beautiful Bill Act should help accelerate this momentum—expanding housing supply, revitalizing communities, spurring job-creating investment nationwide, and strengthening the broader economy. Coupled with improving debt capital availability and stabilizing asset values, these policies set the stage for renewed growth. Moving forward, industry leaders and policymakers must continue to work together to promote investment, ensure credit access, and address persistent supply-demand imbalances in housing and other high-need property sectors.” (ConnectCRE, Aug. 14)

Topline Findings

The Q3 Sentiment Index topline findings include:

  • The Q3 2025 Sentiment Index registered an overall score of 67, an increase of 13 points over the previous quarter. The Current Index registered a score of 63, a 13-point increase over Q2 2025. The Future Index posted a score of 71 points, an increase of 13 points over the previous quarter, reflecting sentiment that operating conditions have largely stabilized. Occupancy and demand are holding, and values appear to have bottomed. Participants expect modest, sector-led growth, yet acknowledge lingering headwinds for weaker property types.
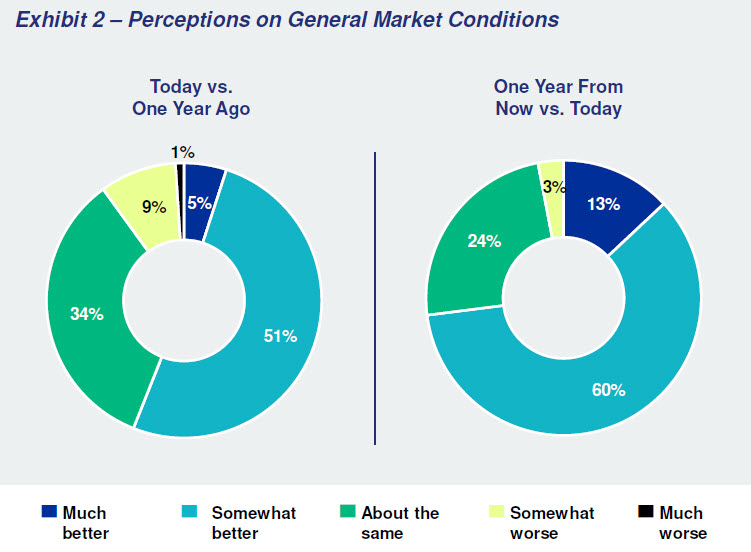
  • Sentiment around general market conditions has markedly increased since last quarter (Q2). Only 10% of respondents believe that general market conditions are worse than this time last year, and 56% of respondents believe that general market conditions are better than this time last year. Almost three-quarters (73%) of Q3 survey participants expect general market conditions to show improvement one year from now. Multifamily, data centers, and NYC office shine while industrial supply is overbuilt.
  • Half of respondents believe asset values are roughly unchanged compared to a year ago. The remaining respondents are divided, with 32% believing asset prices have increased and 18% believing they have declined. Looking ahead, the outlook is optimistic: 59% expect asset prices to rise over the next year, 32% believe asset values will remain stable, and only 9% anticipate a slight decline.
  • Perceptions on the availability of equity capital relative to last year are muted, with 50% of respondents believing equity availability is unchanged compared to a year ago. On the other hand, sentiment around debt capital has risen significantly, as 65% said the availability of debt capital has improved from last year. Looking forward, 55% of respondents believe that equity capital availability will be better in one year, and 48% believe debt capital availability will be better.

Market Dynamics

  • Survey participants emphasized the sector-specific nature of today’s market, with performance tied closely to location, asset quality, and loan maturity schedules. Sample responses noted that conditions feel “far steadier than we have seen in recent years,” while others highlighted that “quality product will still get funded” despite a “haves and have-nots” equity environment. (ConnectCRE, Sept. 2)
  • The Federal Reserve’s Beige Book released this week, noted that while overall economic momentum remains muted, commercial real estate showed resilience, especially in data center construction.
  • Districts such as Philadelphia, Cleveland, and Chicago reported a surge in development, fueled by the push to deploy AI and select infrastructure projects. The Fed described this trend as a rare bright spot for CRE in an otherwise cautious market, while conditions in other property sectors varied widely. (GlobeSt. Sept. 4)
  • The commercial real estate industry continues to face persistent challenges from a shortage of skilled labor and rising construction costs, underscoring the urgent need for workforce development and training initiatives.
  • Labor Secretary Lori Chavez-DeRemer, joined Punchbowl News Thursday to discuss workforce innovation, calling for more apprenticeship and training programs to address the growing construction labor shortage. (Punchbowl News, Sept. 5)

RER’s Q3 survey was conducted in July by Chicago-based Ferguson Partners. Read the full Q3 report.

Interest Rates Hold Steady: All Eyes Now on September FOMC Meeting

This week, the Federal Open Market Committee (FOMC) voted 9-2 to hold rates steady. Two Trump-appointed Fed governors, Michelle Bowman and Christopher Waller, voted against the decision, marking the first FOMC meeting since 1993 in which more than one board governor dissented from the majority.

The Fed’s Decision

  • Fed officials continue to follow a “wait-and-see” approach regarding the impact of tariffs on the economy and the question of who will ultimately bear the costs.
  • The central bank left borrowing rates unchanged at 4.25 percent to 4.5 percent after meeting on Wednesday, despite an aggressive push from President Trump to slash borrowing costs to 1 percent. (Financial Times, July 30)
  • The FOMC’s post-meeting statement expressed only a couple of changes in its views on economic conditions since its last meeting in June.
  • “The unemployment rate remains low, and labor market conditions remain solid. Inflation remains somewhat elevated,” read the statement. At the FOMC’s June meeting, the committee had a more optimistic view, saying the economy “continued to expand at a solid pace.” (CNBC, July 31)
  • Fed Chair Jerome Powell was committed to making sure any one-time increases in prices didn’t lead to more persistent inflation. “We want to [lower rates] efficiently… If you move too soon, you wind up maybe not getting inflation all the way fixed and you have to come back [and raise rates]. That’s inefficient. If you move too late, you might do unnecessary damage to the labor market,” said the chair.” (WSJ, July 30)

Implications for CRE

  • Wednesday’s hold, which was widely expected, is unlikely to push investors in any new direction, as U.S. CRE capital markets are already outperforming forecasts this year. (BisNow, July 30)
  • In parallel, many lenders have started the process of taking enforcement actions on loans past their maturity date while also tracking what may happen with interest rates before executing. (Commercial Observer, July 30)
  • The Fed’s decision reinforces findings from RER’s Q2 2025 Sentiment Index, which indicated that the CRE executives expressed a decline in market confidence, as policy uncertainty, rising costs, and investor caution continue to cloud the outlook. (RW, June 20)

Looking Ahead

  • Focus will now turn towards the September FOMC meeting, as the central bank confronts competing signals about the health of the U.S. economy. (WSJ, July 30)
  • The Personal Consumption Expenditures (PCE) index, the Fed’s preferred inflation gauge, rose last month, suggesting that tariffs may be driving some prices higher. (CBS News, July 31)
  • However, new economic data this week suggested that the U.S. economy so far seems to have avoided significant tariff-related inflation. (Semafor, July 30)
  • The Commerce Department said U.S. gross domestic product—the value of all goods and services produced across the economy—rose at a seasonally and inflation adjusted 3% annual rate in the second quarter. That is up from a 0.5% contraction in the first quarter. (Wall Street Journal, July 30)
  • Despite some encouraging signs, Chair Powell’s reluctance to signal a September rate cut was perceived as hawkish. (Financial Times, July 30)
  • In the meantime, the coming months will likely come with more debate among political leaders around the role of the Fed in the U.S. economy.
  • President Trump’s displeasure with the Fed’s resistance to cut rates has twice taken him to the verge of trying to fire Powell, spooking markets and raising concerns about the central bank’s independence. (Axios, July 31)

Chair Powell is expected to speak at the Jackson Hole Economic Symposium on August 22. With the labor market weakening, inflation holding steady, and political pressure mounting, the speech could offer hints about the likelihood of a rate cut in September. (Barrons, July 30)

Coalition Pushes Back on FSOC Nonbank Rules Amid Broader Scrutiny of Financial Oversight

The Real Estate Roundtable (RER) and a coalition of national trade associations submitted a joint letter on July 14 to Treasury Secretary Scott Bessent, urging the Financial Stability Oversight Council (FSOC) to rescind its 2023 interpretive guidance and reinstate the Council’s 2019 framework for designating nonbank financial companies.

Coalition Letter

  • The 2023 guidance significantly alters FSOC’s designation process, removing procedural safeguards such as cost-benefit analysis and coordination with a company’s primary regulator. (Letter, July 14)
  • The letter warns that FSOC’s shift away from an activities-based approach creates regulatory uncertainty that could chill capital formation, disrupt access to credit, and hinder innovation in risk management. (Pensions & Investments, July 14)
  • The letter signed by RER, the U.S. Chamber of Commerce, Mortgage Bankers Association, American Investment Council, and others, calls on FSOC to withdraw the 2023 guidance, refocus on systemic activities rather than specific firms, and restore due process protections.

Congressional Hearing

  • Lawmakers expressed concern that the 2023 guidance could revive pre-Dodd-Frank regulatory “blind spots” by enabling opaque designations that sidestep traditional supervisory processes. (PoliticoPro, July 16)
  • Committee Vice Chair Rep. Bill Huizenga (R-MI), also raised concerns, and introduced the prospect of curbing FSOC’s authority (American Banker, July 15)
  • At the hearing, lawmakers critically examined the expansive regulatory bureaucracy created by the law and its structural impact on CRE lending. Federal Reserve and FDIC data show that small and midsize banks (assets under $250B) now account for a majority of all CRE lending, particularly construction and land development loans. Exempted from some of Dodd-Frank’s most burdensome provisions, smaller lenders are stepping in to fill the gap left by larger banks scaling back amid accelerating debt maturities. (GlobeSt. July 16)
  • Some members also highlighted the need to restore bipartisan consensus around the Council’s systemic risk role, especially as market complexity grows.

The Fed

The Federal Reserve in Washington, DC
  • The Fed’s independence was also in the spotlight this week as President Trump floated—but ultimately backed off removing Fed Chair Jerome Powell, citing frustration over interest rate policy and the central bank’s headquarters renovation. (PoliticoPro, July 17)
  • Tensions over the Fed’s future rattled markets, with bond yields spiking and CRE leaders cautioning against politicizing monetary policy. (GlobeSt., July 17 | Axios, July 17)
  • JPMorgan Chase CEO Jamie Dimon warned that “playing around with the Fed” could carry serious consequences for U.S. financial credibility. (WSJ, July 15)

The Fed’s next policy meeting is scheduled for July 29–30. Policymakers are expected to keep interest rates steady at 4.25% to 4.5%—marking the fifth consecutive meeting without a change since the central bank paused rate cuts in December. (Reuters, July 17 | Axios, July 18)