Fed Holds Rates Steady as Inflation Concerns Persist

The Federal Reserve held its benchmark interest rate steady at 3.75–4 percent on Wednesday, pausing after September’s quarter-point increase as policymakers assess persistent inflation and economic conditions. Two officials dissented in favor of another rate hike, underscoring continued pressure to tighten monetary policy. (Federal Reserve, Oct. 28 | The Wall Street Journal, Oct. 29)

State of Play

  • The Federal Open Market Committee (FOMC) voted 10–2 to maintain the current target range, with Federal Reserve Governor Lisa Cook and Cleveland Fed President Beth Hammack favoring a 25-basis-point increase. The decision follows September’s unanimous vote to raise rates for the first time since 2023. (Federal Reserve, Oct. 28 | Federal Reserve, Sept. 16)
  • The Fed characterized economic activity as “expanding at a strong pace,” supported by resilient consumer spending, strong productivity growth, and robust capital investment.
  • Inflation remains elevated, and policymakers emphasized the importance of additional economic data in determining the appropriate policy stance. (Federal Reserve, Oct. 28)
  • The October decision leaves open the possibility of another rate increase before year-end as the Fed continues working toward its 2 percent inflation target. (Federal Reserve)

Why It Matters

  • Elevated interest rates continue to weigh on commercial real estate (CRE) borrowing costs, refinancing activity, and investment. Continued inflation pressures and elevated Treasury yields can increase financing costs for property owners and developers.
  • Nearly $983 billion in U.S. CRE mortgages are estimated to mature in 2027, underscoring the importance of accessible financing as borrowers face higher debt service costs and potentially more challenging refinancing conditions. (RER Policy Priorities, Capital & Credit)
  • The rapid buildout of artificial intelligence (AI) data centers is adding complexity to the Fed’s inflation outlook. Data center investment is supporting economic growth while straining electricity supply and construction capacity. (Politico, Oct. 28)
  • Higher rates could weigh on housing and other interest-sensitive sectors without substantially slowing spending by well-capitalized technology companies. (Politico, Oct. 28)

The FOMC’s final scheduled policy meeting of 2026 will take place Dec. 8–9, when officials will release an updated Summary of Economic Projections.

RER and Broad Coalition Urge Congress to Direct ENERGY STAR Funding to DOE

The Real Estate Roundtable (RER) led a broad coalition of organizations representing real estate, consumer products, manufacturing, retail, technology, and energy efficiency advocates in a letter to congressional appropriators Thursday, urging Congress to provide FY 2027 funding for ENERGY STAR directly to the Department of Energy (DOE) as it assumes leadership of the program from the Environmental Protection Agency (EPA). (Coalition Letter, Oct. 29)

Coalition Advocacy

  • Federal funding is currently set to expire on December 11. When Congress reconvenes after the midterms, it is expected to consider FY’27 spending legislation through this coming Sept. 30.
  • The coalition urged Congress to continue directed FY’27 appropriations for ENERGY STAR, specifically requesting that program dollars be provided to DOE to align federal funding with the agencies’ new responsibilities.
  • The issue attracts support across the ideological spectrum. In addition to major real estate organizations, signatories range from the American Gas Association and the National Association of Manufacturers, to the U.S. Green Building Council, to the national association representing all state energy offices.
  • The letter emphasized that appropriating funds directly to DOE would strengthen congressional oversight, ensure that expenditures reflect DOE’s lead implementation role, and stabilize the program’s continuity during the transition period.
  • The coalition called for at least $33 million in FY’27 funding, consistent with the amount appropriated last year.  (Bill text (page 85) | Roundtable Weekly, Jan. 9)

ENERGY STAR Transition to DOE

  • In August, DOE and EPA released a transition plan outlining how DOE will assume leadership and core operations of ENERGY STAR, with the transition expected to be completed by July 2027. (Roundtable Weekly, Sept. 11)
  • DOE’s Office of Critical Minerals and Energy Innovation (CMEI) will oversee the program, including its information technology portfolio, Portfolio Manager, and related datasets. (Roundtable Weekly, March 6 | Roundtable Weekly, Sept. 11)

Why It Matters

  • ENERGY STAR has helped American families and businesses save more than $500 billion in energy costs since 1992. The coalition emphasized that the voluntary public-private partnership supports energy affordability, competitiveness, and broader national energy objectives. (Coalition Letter, Oct. 29)
  • RER and its coalition partners have consistently advocated for preserving ENERGY STAR as a voluntary federal program, supporting DOE’s new leadership role and urging Congress to maintain adequate funding and oversight. (Roundtable Weekly, April 17 | Roundtable Weekly, April 3)

RER and our coalition partners will rally congressional appropriators to include ENERGY STAR funding in FY’27 spending legislation considered during the upcoming lame duck session.

RER Releases 2026 Annual Report

The Real Estate Roundtable (RER) is pleased to share our 2026 Annual Report: A Framework for Growth: Advancing Smart Policy for Tomorrow’s Living and Working Spaces, highlighting RER’s advocacy over the past year and priorities for strengthening investment, expanding housing supply, ensuring affordable and reliable energy, enhancing homeland security, and supporting economic growth. (Full Report)

Roundtable Leadership

  • This year’s report details how RER’s engagement helped preserve and enhance critical real estate tax rules, eliminate a proposed seven-year forced-sale requirement for certain rental housing, protect ENERGY STAR, shape financial regulatory proposals affecting commercial real estate, and much more. (Introduction)
  • It also underscores the industry’s role in supporting jobs, local tax bases, and retirement security. “Commercial and multifamily real estate remain bedrock pillars of the American economy, directly contributing to job creation, local tax bases, and retirement security,” the report states.
  • The report recognizes Kathleen McCarthy Baldwin’s leadership as chair, including expanded member outreach through Roundtable on the Road, deeper participation across policy committees, and strengthened communications.
  • As Owen Thomas, RER Chair and Chairman and CEO of BXP, begins his tenure, RER will build on this foundation through continued outreach and direct engagement with members across the country, ensuring its advocacy reflects regional conditions and the real-world impact of federal policy decisions.
  • “In an era marked by shifting capital liquidity, rising electricity demand, rapid growth of artificial intelligence (AI) and data centers, evolving energy mandates, and a critical shortage of affordable housing, passive policy adaptation is not an option,” said Jeffrey DeBoer, RER President and CEO. (Read Intro)

Explore the 2026 Report

RER’s FY2026 Annual Report details the organization’s mission and recent activities, and offers potential policy solutions to today’s pressing and far-reaching industry challenges, including:

The publication also includes:

  • Introduction: A review of the year’s impact, leadership transition, and priorities ahead.
  • Member Engagement: Highlights of member participation and engagement with policymakers.
  • Membership: RER’s members, board of directors, and policy advisory committee leadership.

Printed copies of the Annual Report are currently being mailed to members. If you would like additional copies, please email agrenadier@rer.org

Fed Beige Book Highlights Mixed CRE Conditions and Continued Financing Pressures

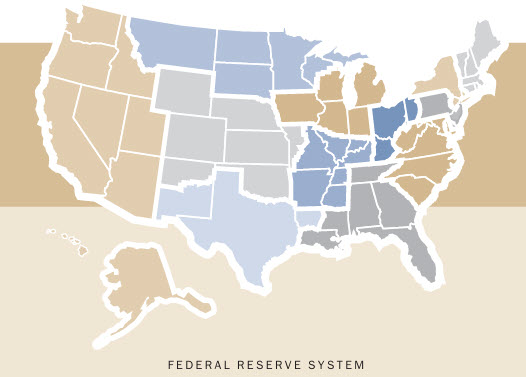
The Federal Reserve’s October Beige Book, released Oct. 14, found that economic activity grew slightly or modestly across most districts, while commercial real estate conditions varied by region. Higher borrowing costs, tighter credit conditions, and rising construction expenses continued to weigh on investment and development. (Beige Book, Oct. 14 | GlobeSt., Oct. 16)

Regional CRE Trends

  • New York: Commercial property sales slowed as rising interest rates reduced demand, despite strong Manhattan office leasing and industrial demand driven by data centers. Banks reported slightly tighter credit standards for commercial mortgages, with concerns over interest rate exposure and refinancing costs. (New York Fed)
  • Chicago: Construction and real estate activity declined slightly, although commercial real estate activity remained unchanged overall. Financial conditions tightened modestly, while major development projects competed for construction capacity and electrical equipment needed for data centers. (Chicago Fed)
  • National Outlook: Nine of the 12 Federal Reserve districts reported slight to moderate economic growth, while three reported little change. Businesses continued to face higher costs from energy, tariffs, and insurance, along with shortages of specialized technical and skilled-trade workers. (Federal Reserve)

Why It Matters

  • Nationally, businesses continued to report higher input costs, including pressure from tariffs, insurance, and energy prices. Several districts also noted continued shortages of specialized technical and skilled-trade workers, which could affect construction costs and development timelines. (Federal Reserve, Oct. 14)
  • Financing pressures and rising development costs remain key challenges for CRE investment. Higher borrowing costs and tighter lending standards can complicate refinancing and property transactions, while labor shortages and competition for construction materials and infrastructure capacity can delay new projects. 

Roundtable on the Road

  • This week, RER President and CEO Jeffrey DeBoer joined Kristen Silverberg, Business Roundtable’s President and COO and incoming President and CEO, for a policy and business panel at Marriott International’s North America (MINA) Conference. The discussion focused on policy issues affecting the economy, job creation and investment.
  • The panel also addressed the upcoming elections and next year’s legislative outlook. DeBoer and Silverberg encouraged business leaders to engage with state and local officials, noting that nearly 50 members of Congress previously served as mayors or governors.

RER will release its Q4 2026 Sentiment Index Report in the coming weeks, providing an updated assessment of commercial real estate executives’ views on market conditions, capital availability, and the outlook for the industry.

Energy Policy Update: Permitting Reform, Data Center Growth and Tax Proposals

A bipartisan group of former senior administration officials is urging Congress to advance permitting reform legislation, citing growing energy demand, infrastructure delays, and threats to U.S. economic competitiveness. The push comes as new research highlights the economic impact of data center development and Senate Democrats introduce proposals to reshape federal energy and data center tax incentives. (The Hill | Axios, Oct. 21)

Permitting Reform

  • Nineteen former economic and national security officials from five presidential administrations urged congressional leaders to pass bipartisan permitting reform legislation, warning that lengthy approval processes are hindering infrastructure development, economic growth, and national security. (The Hill, Oct. 21)
  • Signatories included former Treasury Secretaries Janet Yellen, Steven Mnuchin, Timothy Geithner, Henry Paulson Jr. and Robert Rubin, along with former Secretary of State Mike Pompeo and seven former chairs of the Council of Economic Advisers.
  • The officials endorsed the bipartisan American Affordability and Jobs Act, introduced Sept. 30 by Sens. Shelley Moore Capito (R-WV), Mike Lee (R-UT), Martin Heinrich (D-NM) and Sheldon Whitehouse (D-RI), which would reform federal environmental review and permitting processes. (Roundtable Weekly, Oct. 2)
  • The officials warned that permitting delays are particularly concerning as artificial intelligence and data center development drive electricity demand. Faster infrastructure approvals could expand electricity supply, reduce reliance on costly on-site generation and help lower consumer energy costs.

RER Advocacy

  • The Real Estate Roundtable (RER) has consistently supported bipartisan permitting reform to strengthen grid reliability, lower energy costs, and accelerate infrastructure investment.
  • In a December 2025 letter to congressional leadership, RER urged passage of the bipartisan SPEED Act (H.R. 4776), emphasizing that duplicative federal reviews delay the delivery of affordable, reliable electricity to homes and commercial buildings. (RER Letter, Dec. 8 | Roundtable Weekly, Dec. 12)

Data Center Economic Impact

  • A new U.S. Chamber of Commerce study found that data centers generate substantial economic activity, employment, and local tax revenue, underscoring their role in supporting communities and infrastructure investment. (U.S. Chamber of Commerce, Oct. 15)
  • By the Numbers: According to the Chamber’s analysis, economic impacts generated by a typical 50-megawatt data center include:
  • 5,200 jobs annually supported statewide during a two-year construction phase, generating approximately $680 million in economic activity.
  • $114 million in local tax revenue projected over five years in Prince William County, Virginia, with similar benefits estimated for communities in Texas, Georgia, and Ohio.
  • The findings come as lawmakers debate how to accommodate growing data center electricity demand while protecting consumers from higher infrastructure costs.
  • RER has also urged the North American Electric Reliability Corporation (NERC) to develop clear, workable grid reliability standards that reflect the distinct responsibilities of data center owners, operators, and tenants. (Roundtable Weekly, Sept. 18)
  • Meanwhile, congressional Democrats plan to ramp up oversight of the Trump Administration’s efforts to avoid federal environmental standards for data centers if they take control of the House and/or Senate after the midterms. (PoliticoPro, Oct. 22)

Data Center Tax Proposals

Sen. Ron Wyden (D-OR)
  • Senate Finance Committee Ranking Member Ron Wyden (D-OR) released draft legislation Friday that would impose an excise tax on data center operators and eliminate several federal tax incentives for data center investment, including bonus depreciation, Opportunity Zone benefits and research and development tax credits. (Press Release | Senate Finance Committee Summary | Draft Legislation, Oct. 23)
  • The proposal builds on Wyden’s August white paper, which also called for restrictions on certain data center investments through real estate investment trusts (REITs). (Roundtable Weekly, Aug. 7)
  • The proposed changes would create tax penalties specifically targeting data centers by excluding them from longstanding incentives available to other capital investments. (Roundtable Weekly, Aug. 7)

Clean Energy Tax Incentives

  • Sen. Wyden (D-OR) also outlined plans to restore wind and solar tax credits and expand the Inflation Reduction Act’s Direct Pay Program if Democrats regain control of the Senate. (Politico, Oct. 22)
  • A new Senate Finance Committee Democratic staff report found that nearly $2.5 billion in direct payments went to tax-exempt entities during the program’s first two years, supporting renewable energy and other clean energy investments. (Sen. Wyden Press Release, Oct. 22)

The November elections will shape prospects for permitting reform, data center regulation and federal energy tax policy, with several proposals potentially returning to the agenda during the lame-duck session or the next Congress.

Treasury Proposes Single-Family Investment Rules as Administration Pursues Housing Affordability Measures

President Donald Trump signed an executive order on Thursday, aimed at reducing mortgage costs and supporting manufactured housing development. Separately, Treasury proposed rules implementing restrictions on institutional purchases of single-family homes, while HUD expanded financing eligibility for build-to-rent communities. (The Hill | White House, Oct. 22)

Executive Order

  • The Oct. 22 executive order directs the Federal Housing Finance Agency (FHFA) to establish a mortgage insurance cancellation pilot through Fannie Mae and Freddie Mac, subject to safety and soundness and other requirements. The pilot would proactively identify eligible borrowers and apply to mortgages originated after the program begins. (White House EO | Politico, Oct. 22)
  • To reduce refinancing costs, the order directs FHFA to expand alternatives to lender’s title insurance for eligible refinances, with savings passed through to borrowers.
  • The order also establishes a federal task force on manufactured housing to recommend ways to streamline approvals, reduce duplicative requirements and expand manufactured and factory-built housing production. Recommendations are due within 180 days. (Reuters, Oct. 22)

Treasury’s Proposed Housing Rules

  • Beginning Jan. 7, 2027, large institutional investors generally may not purchase—or enter into contracts to purchase—single-family homes unless the transactions qualify for a statutory exception. The law’s definition includes entities engaged in the single-family housing business with direct or indirect investment control over at least 350 homes. (Treasury Press Release, Oct. 22)
  • The proposal outlines how exceptions would apply to build-to-rent, renovate-to-rent and homeownership programs, including standards for substantial rehabilitation, and financial assistance to help renters purchase homes. (PoliticoPro, Oct. 22)
  • Treasury also proposes clarifications addressing passive investment, ownership and property-control arrangements, certain debt-related transactions, and transfers between large institutional investors.
  • Treasury said its approach seeks to accommodate different investment, construction and property-management structures while avoiding unnecessary disruption to housing supply, homebuilding, rehabilitation and capital formation.
  • Rep. Maxine Waters (D-CA), Ranking Member on the House Financial Services Committee, welcomed Treasury’s proposal but urged the department to ensure the rules protect homeownership opportunities for families and prevent investors from circumventing the restrictions. (Rep. Waters Press Release, Oct. 22)
  • The Real Estate Roundtable (RER) welcomes member input as it prepares comments on Treasury’s proposed investor rules and their implications for housing supply and private investment. Comments are due 30 days after publication in the Federal Register.

Build-to-Rent Financing

  • HUD announced Oct. 14 that build-to-rent communities—including single-family homes, duplexes and triplexes—are now eligible for FHA-insured financing under the same general terms as traditional multifamily rental developments.
  • Effective immediately, the policy expands financing options for new construction and the acquisition or refinancing of recently developed rental communities. (HUD Press Release, Oct. 14)

Government Sponsored Enterprises (GSEs)

  • Treasury Secretary Scott Bessent said Tuesday that the administration expects to pursue an overhaul of Fannie Mae and Freddie Mac over the next two years, setting a new timeline for addressing their government conservatorship, which began during the 2008 financial crisis.  (Politico Pro, Oct. 20)

Sec. Bessent said the administration’s priority is ensuring that any changes do not increase mortgage rates relative to Treasury bonds. (Politico Pro, Oct. 20)

Tax Policy Roundup: Lame-Duck Outlook, Opportunity Zones and Data Center Proposals

The November elections will shape the prospects for year-end tax legislation, with a crowded lame-duck agenda leaving limited room for a bipartisan package. Treasury and the IRS are also advancing guidance affecting real estate investment, while lawmakers continue to pursue new limits on data center tax incentives.

Lame-Duck Outlook

  • Lawmakers will return to Washington with just 24 legislative days to address government funding beyond Dec. 11, the annual defense policy bill and other expiring programs. Those negotiations could provide a vehicle for a limited tax package. (Politico, Oct. 13)
  • Potential provisions could include renewing the Work Opportunity Tax Credit, improving IRS administration, and making targeted corrections to the 2025 tax law. A narrow bipartisan agreement appears more achievable than a broader tax bargain, with cost and competing party priorities remaining obstacles. (WilmerHale, Oct. 14)
  • Control of the next Congress will influence whether lawmakers negotiate a year-end agreement or defer major decisions until 2027. Another Republican reconciliation bill remains uncertain, with Senate Majority Leader John Thune (R-SD) acknowledging the difficulty of securing sufficient votes. (Politico, Oct. 13 | Thomson Reuters, Oct. 15)
  • Senate Minority Leader Chuck Schumer (DNY) stated in a recent interview, “The lame duck will be quite different if we win the Senate,” he said. “Same thing if they win the House, and same thing if we win both or neither.” (Politico, Oct. 13)

Opportunity Zones and Tax Guidance

  • OZ deadlines: State nominations for new OZ maps have been extended and are now due Oct. 28, while comments on proposed reporting rules and broader program implementation are due Oct. 26 and Nov. 23, respectively. (Roundtable Weekly, Sept. 25 | Federal Register, Sept. 28 | IRS, Sept. 22)
  • RER advocacy: RER’s Opportunity Zone Working Group met with Treasury and IRS officials in August and has urged clear transition rules that allow existing projects to continue under the permanent program. (Roundtable Weekly, Sept. 25)
  • Treasury and the IRS recently released their 2026–2027 Priority Guidance Plan, outlining 121 tax guidance projects, including rules on Opportunity Zones, business interest deductibility, bonus depreciation and the Section 199A pass-through deduction. (Treasury–IRS Priority Guidance Plan, Sept. 29)
  • These administrative decisions will help determine how provisions of the 2025 tax law operate regardless of congressional action.

Data Center Tax Proposals

  • Sen. Peter Welch (D-VT) urged the IRS to examine whether major technology companies are improperly claiming research and experimentation tax credits for AI data center development. His Oct. 7 letter requests information on claims, enforcement, and potential guidance changes. (Sen. Welch Press Release, Oct. 8)
  • Sen. Welch’s inquiry follows proposals from Senate Finance Committee Ranking Member Ron Wyden (D-OR), Sen. Josh Hawley (R-MO) and House Democrats targeting data center tax treatment. (PoliticoPro, Oct. 14)
  • The proposals include restrictions on OZ eligibility and bonus depreciation; Wyden’s framework also targets certain REIT rents and proposes an operator excise tax. (Roundtable Weekly, Aug. 7 | Roundtable Weekly, Sept. 25 | Axios, Oct. 8)
  • A separate report led by Sen. Elizabeth Warren (D-MA) criticized data center companies’ energy-cost commitments and pursuit of state and local tax incentives. (Sen. Warren Press Release, Oct. 9)

Roundtable on the Road

  • In his prepared remarks, DeBoer highlighted that “[r]eal estate development is not just about buildings; it is a macro-economic engine that provides funding for local and national budgets, creates millions of jobs and structurally supports the long-term retirement goals of everyday Americans through pension funds and institutional portfolios.”

DeBoer also called for policies that reward capital investment, lower housing production costs, accelerate commercial-to-residential conversions, remove regulatory barriers, and expand private investment in housing and community redevelopment.

RER Calls for Coordinated Community Reinvestment Act (CRA) Rules; HUD Outlines Manufactured Housing Plan

This week, The Real Estate Roundtable (RER) urged all three federal banking agencies to adopt clear, harmonized Community Reinvestment Act (CRA) rules to reduce compliance costs and support capital investment in affordable housing and underserved communities. (Letter, Oct. 13)

CRA Rulemaking

  • In the Oct. 13 letter, RER called for the Office of the Comptroller of the Currency (OCC), Federal Deposit Insurance Corporation (FDIC), and Federal Reserve to adopt clear, harmonized CRA rules. The OCC and FDIC have jointly proposed changes without parallel Federal Reserve action. (Letter, Oct. 13)
  • Enacted in 1977 to combat redlining, the CRA encourages banks to meet the credit needs of their entire communities, including low- and moderate-income neighborhoods.
  • RER supports continued efforts to modernize CRA rules but cautioned that finalizing changes without parallel Federal Reserve action could replace the historically uniform interagency framework with materially different regulatory regimes. (Letter, Oct. 13)

Why It Matters

  • Affordable housing and community development projects frequently rely on multiple banks providing construction loans, permanent financing, tax credit investments, and other forms of capital.
  • A divided CRA regime could make identical loans receive different treatment, weaken investment incentives for some lenders, complicate mergers and syndicated transactions, and make the flow of capital into underserved markets less predictable.
  • RER also raised concerns about a potential 1.25% of Tier 1 capital benchmark for wholesale and limited-purpose banks, which would need to be met within their assessment areas before qualifying activities elsewhere could receive CRA consideration. (Letter, Oct. 13)
  • The benchmark could concentrate investment in heavily banked markets while disadvantaging strong projects in smaller metropolitan and rural communities.
  • RER recommended uniform rules, coordinated implementation and consistent treatment of multibank transactions. (Letter, Oct. 13)

RER Advocacy

  • RER urged the agencies to coordinate transition schedules, examinations and interpretive guidance, and apply consistent standards to multibank housing and community development transactions. (Letter, Oct. 13)
  • Existing requirements should remain in place until all three agencies jointly propose and finalize a harmonized framework.

Manufactured Housing

  • The plan calls for updated energy efficiency standards, design and installation rules for chassis-free homes, and a performance-based code for larger factory-built residential structures. HUD will also develop guidance and resources addressing zoning, appraisal, lending, and insurance. (HUD, Oct. 7)
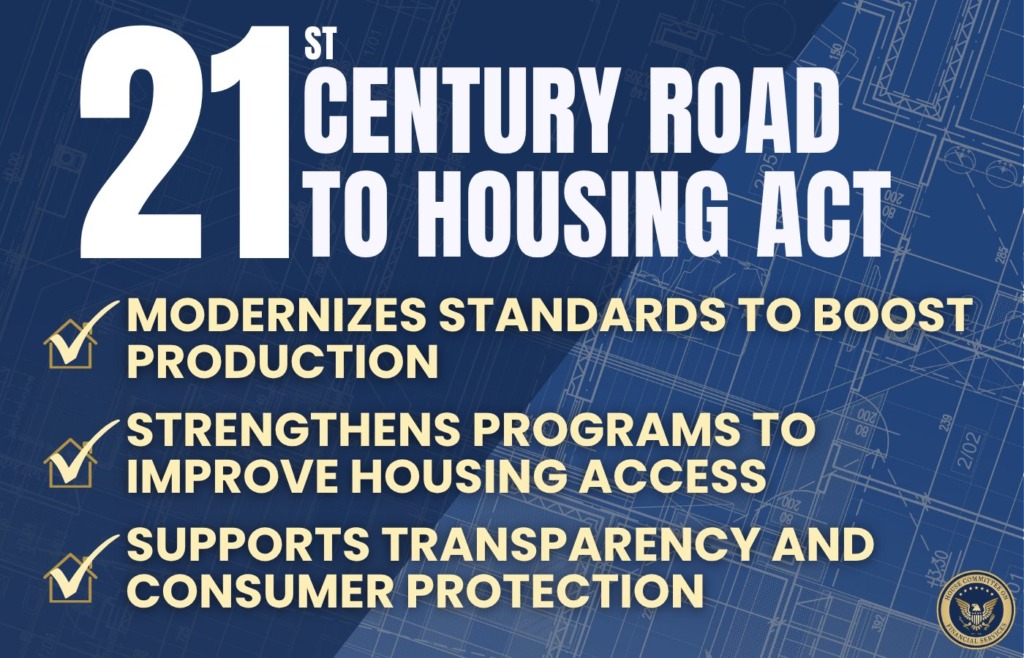
  • The ROAD Act eliminates the requirement that manufactured homes be built and remain on a permanent steel transport frame—a relic of the mobile home era. The change could reduce construction costs by $5,000–$10,000 per home, by some estimates, allow more flexible designs, and reduce local zoning barriers. (RER’s Housing Fact Sheet, July 2026)

RER will continue working with banking agencies and stakeholders to advance rules that support community investment and provide certainty for real estate financing.

Fed Signals Another Rate Hike as Regulators Advance Capital Reforms

Minutes from the Federal Reserve’s Sept. 15-16 meeting, released Oct. 7, indicated that most policymakers believe another interest rate increase would likely be appropriate by year-end. The minutes follow recent remarks by Federal Reserve Vice Chair for Supervision Michelle Bowman, who said she expects regulators to finalize the revised Basel III capital framework by year-end, while pointing to early results from recent leverage ratio reforms. (Federal Reserve, Sept. 18 | Federal Reserve, Oct. 1 | American Banker, Oct. 1 | Federal Reserve, Oct. 7)

Fed Outlook

  • Most Federal Open Market Committee (FOMC) participants indicated that another rate increase would likely be appropriate before year-end, following the Fed’s unanimous decision in September to raise its benchmark rate by 25 basis points, bringing the target range to 3.75%-4%. Officials cited persistent inflation, resilient economic activity, and diminished labor market risks in support of additional tightening. (Federal Reserve, Oct. 7 | Wall Street Journal, Oct. 7 | Associated Press, Oct. 7)
  • Credit and Housing. Several participants pointed to easier bank lending standards, while a few noted that elevated mortgage rates continued to weigh on housing activity. Treasury yields rose roughly 35 basis points across the 2- to 10-year range between meetings, while residential mortgage rates increased slightly more than the 10-year Treasury yield. (Federal Reserve, Oct. 7)
  • Regulatory Reform. Bowman said the Fed’s recalibration of the enhanced supplementary leverage ratio (eSLR) has expanded large banks’ balance sheet capacity and improved Treasury market intermediation. Dealers’ Treasury positions increased from approximately $600 billion before the changes to more than $700 billion by the end of April, demonstrating how adjustments to capital requirements can support market liquidity. (Federal Reserve, Oct. 1 | Bloomberg Law, Oct. 1)
  • Capital Reforms. Regulators are expected to finalize revised risk-based capital requirements under Basel III and accompanying changes to the global systemically important bank (G-SIB) surcharge before year-end. The proposals, released in March, would reduce aggregate capital requirements for the largest U.S. banks by an estimated 2.4% and revise the treatment of mortgages and mortgage servicing assets to better align capital requirements with risk. (Roundtable Weekly, March 20 | Bloomberg, March 19 | Federal Reserve, Sept. 18)

Why It Matters

  • Another potential rate increase, combined with elevated Treasury yields, could extend borrowing and refinancing pressures for commercial real estate (CRE) owners. Nearly $983 billion in CRE mortgages are estimated to mature in 2027, increasing the importance of accessible financing as borrowers seek to refinance existing debt. (Federal Reserve, Oct. 7 | RER Policy Priorities, Capital & Credit)
  • At the same time, appropriately calibrated capital requirements could strengthen banks’ capacity and incentives to provide CRE financing. While the eSLR changes primarily address Treasury market intermediation, the revised Basel III framework could ease certain regulatory constraints on lending and support market liquidity as borrowers navigate elevated financing costs. (Roundtable Weekly, March 20 | Federal Reserve, Sept. 18 | Federal Reserve, Oct. 1)

Roundtable Advocacy

  • The Real Estate Roundtable has consistently advocated for appropriately calibrated, risk-based bank capital requirements that maintain financial stability without unnecessarily limiting CRE lending. RER opposed the original 2023 Basel III proposal, warning that higher capital requirements could reduce credit availability, increase financing costs, and constrain investment in commercial and multifamily real estate. (Roundtable Weekly, March 20)
  • In a June 18 coalition letter, RER and other national real estate organizations urged regulators to preserve the revised proposal’s improvements while making targeted changes to avoid unnecessarily constraining CRE financing. Recommendations included more risk-sensitive treatment of CRE and multifamily loans, mortgage servicing, and securitizations, along with changes to prevent disproportionate capital charges on common financing arrangements such as mezzanine loans and preferred equity. (Coalition Letter, June 18)

RER will continue engaging with federal regulators and industry partners as the Basel III reforms move toward finalization, advocating for capital requirements that preserve credit availability, support housing and commercial real estate investment, and maintain a stable and liquid CRE finance market.

New Senate Legislation Takes Aim at Wall Street but Threatens to Disrupt U.S. Real Estate

Legislation introduced in the House and Senate on Sept. 24 aims to fundamentally reform the private equity industry, but the expansive legislation could cause major disruption to U.S. real estate values and markets.

The newly revised Stop Wall Street Looting Act, introduced by Sen. Elizabeth Warren (D-MA) and seven other Democratic senators, as well as a coalition of progressive House members, would raise the tax rate on REIT investors, end capital gains treatment for carried interest, and greatly restrict the deductibility of interest on real estate borrowing. (Senate Banking Committee, Sept. 24 | Bill Text)

State of Play

  • Sponsors seek to rein in investment by private funds. The bill authors seek to build on their successful effort this summer to expand the government’s role in regulating private investment in single-family rental housing. The legislation would impose restrictions on the activities of private funds, including their acquisitions, distributions, and business operations such as outsourcing jobs or closing facilities. (Section-by-Section Summary, Sept. 24)
  • Legislation’s reach extends beyond Wall Street. The legislation would have far-reaching consequences for REITs, REIT investors, and real estate generally. While the sponsors highlight a specific case involving REIT ownership of health care-related property, the bill would raise the tax rate on all REIT investors by repealing the 20% deduction for qualified REIT dividends (Section 199A). (Section-by-Section Summary, Sept. 24)
  • Carried interest. The bill also incorporates the Carried Interest Fairness Act (S. 445), introduced by Sen. Tammy Baldwin (D-WI). The Carried Interest Fairness Act would recharacterize all carried interest income as ordinary income rather than capital gains. (Section-by-Section Summary, Sept. 24)
  • Interest deductibility. The bill would restrict business interest deductions under Section 163(j) for certain businesses controlled by private investment funds if the business has a rate of leverage (debt-to-equity ratio) greater than 50%. The proposal would calculate leverage using the adjusted basis of a business’s assets rather than market value, potentially overstating the leverage on appreciated real estate. Qualifying businesses that meet the bill’s conditions would also lose access to the existing real estate exception from the Section 163(j) limitation. (Section-by-Section Summary, Sept. 24)
  • Health care real estate and fund fees. Other provisions would prohibit federal health care payments to certain entities that sell or pledge assets to REITs and modify rules governing taxable REIT subsidiaries that operate health care properties. Additionally, it would impose a 100% tax on certain fees, often called “monitoring” or “transaction” fees, paid by fund-controlled companies to private fund managers. (Section-by-Section Summary, Sept. 24)
  • Outlook for the bill. While action on the legislation is unlikely in the near term, the sponsors will likely seek to include some or all of the provisions in tax legislation next year if control of either chamber changes.

Why It Matters

  • Taken together, the proposed changes could affect a broad range of real estate businesses and investors beyond private equity funds. Eliminating the Section 199A deduction for qualified REIT dividends and changing the tax treatment of carried interest would increase tax burdens and discourage investment in real estate partnerships, REITs, and development projects. (RER Carried Interest Fact Sheet, Jan. 2026)
  • Restrictions on interest deductions could create additional financing challenges for real estate owners by increasing after-tax borrowing costs, reducing property values, and complicating the refinancing of maturing debt. Because debt is a fundamental source of financing for commercial real estate investment and development, the changes could also constrain capital availability and discourage new investment. (RER Policy Priorities, Tax)

Roundtable Advocacy

  • The Real Estate Roundtable (RER) has consistently opposed proposals to tax all carried interest as ordinary income, emphasizing that carried interest reflects the entrepreneurial risk and “sweat equity” contributed by general partners to real estate ventures. RER has warned that such changes could affect 2.2 million real estate partnerships and 9.7 million partners nationwide. (RER Carried Interest Fact Sheet, Jan. 2026)
  • Beyond carried interest, RER has advocated for preserving the Section 199A deduction for pass-through businesses and qualified REIT dividends, as well as the real estate exception from Section 163(j). In an October 2025 letter to Treasury and the IRS, RER urged regulators to allow real estate businesses to revisit prior Section 163(j) elections to access bonus depreciation benefits restored under the 2025 tax law. (RER Letter, Oct. 17, 2025)

RER will continue working with policymakers to oppose tax provisions that could undermine real estate investment, financing, and development, while advocating for policies that support capital formation and the stability of U.S. real estate markets.